

Why Des Moines Is Winning America’s Housing Race While Los Angeles Falls Behind
Regulation and land availability separate the nation’s strongest and weakest housing markets
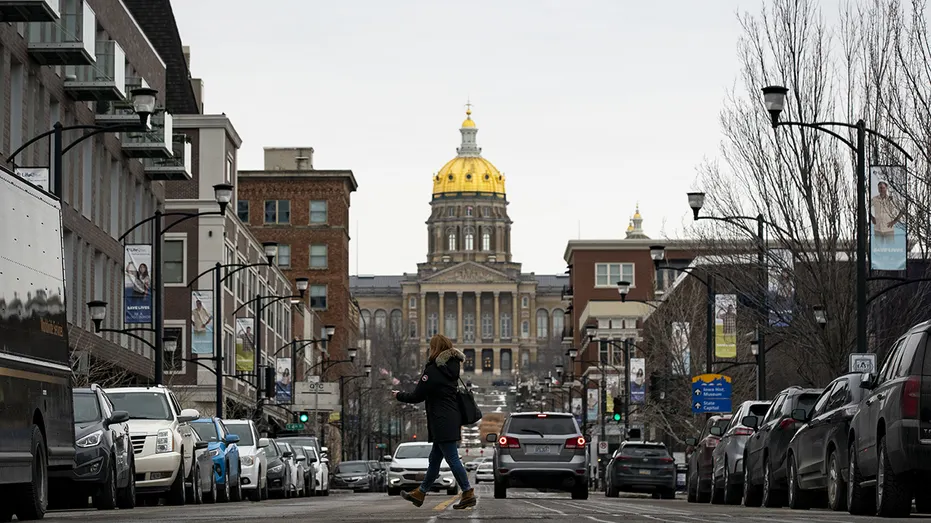
A comprehensive evaluation of the 100 largest metropolitan areas in the United States found a sharp geographical divide in the nation’s housing supply crisis. Differences in municipal zoning policies, permitting timelines, and land availability are separating markets that can add homes from those struggling to keep pace.
Realtor.com scored major housing markets by measuring current residential affordability alongside the pace at which homebuilders are adding new inventory. Joel Berner, senior economist at Realtor.com, said the methodology was intended to examine how local conditions are changing rather than rely only on static price points.
“It’s really a balanced look at the present and the future for how things are affordable now and how they might be affordable in years to come,” Berner said.
Des Moines-West Des Moines, Iowa, received the highest overall score, earning an A+ grade. Raleigh, North Carolina; Columbia, South Carolina; Houston, Texas; and Indianapolis, Indiana, followed among the five strongest-performing markets.
The national market is carrying a cumulative housing deficit estimated at more than 4 million homes. Single-family housing completions averaged under 700,000 units annually between 2009 and 2019, well below the long-term historical average of roughly 1 million units per year.
That shortfall followed more than a decade of underbuilding after the 2007–2008 subprime mortgage crisis and the Great Recession, and intense demand during the COVID-19 pandemic further exacerbated the structural deficit.
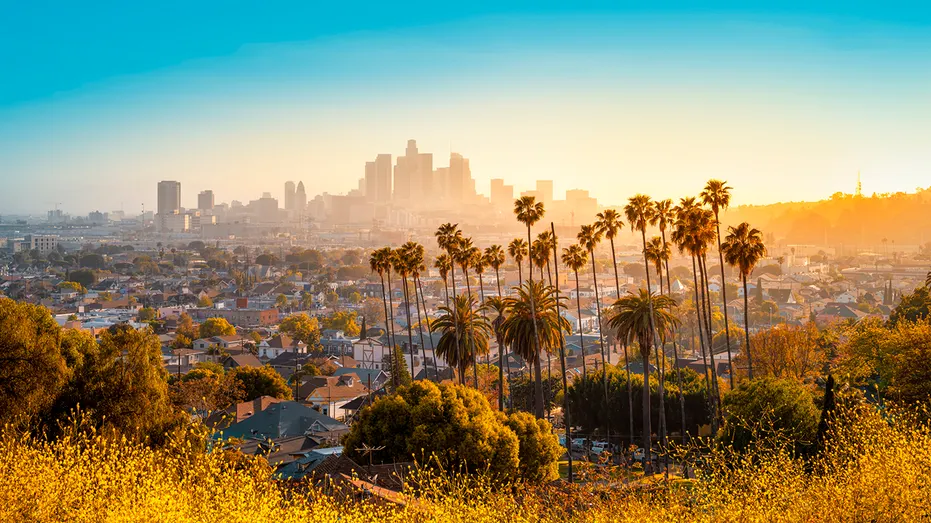
Los Angeles, California, posted the lowest score among the 100 markets and received an F. Providence, Rhode Island; New York City; Honolulu, Hawaii; and Boston, Massachusetts, made up the rest of the bottom five.
Mortgage costs added pressure to the existing shortage. To curb elevated post-pandemic inflation, the Federal Reserve raised its benchmark federal funds rate 11 times between March 2022 and July 2023, taking the target range to 5.25%–5.50%, a 22-year high.
Average rates on 30-year fixed-rate mortgages climbed from under 3% in early 2021 to more than 7.7% in late 2023. Existing homeowners holding low fixed-rate mortgages then avoided listing their properties, creating a widespread “lock-in effect” and shifting buyer demand heavily toward new construction.
Residential builders, however, were dealing with their own bottlenecks. “Builders are getting squeezed on both sides,” Berner said. “Their costs are going up, whether it’s materials, labor or the cost of regulation. … And on the demand side, they’re seeing depressed buyer activity because of high mortgage rates and low buyer affordability.”
National Association of Home Builders statistics show that government regulations account for roughly 23.8% of the final sales price of an average new single-family home. The figure includes land development costs, environmental reviews, impact fees, and zoning compliance.
Many top-performing metropolitan areas are in the Midwest and Sun Belt, where local regulatory environments encourage construction to match population and economic growth. Their administrative processes and land-use policies also support faster construction turnaround times.
“They have local government facilitating new projects, not getting in the way, not having really restrictive zoning laws, having quick permitting processes,” Berner said. “And these are places with strong job markets that are growing really fast, and the cities are allowing builders to absorb that increasing demand for homes in these growing cities by building a lot of them.”
Land availability gives many Sun Belt and Midwestern urban areas additional flexibility. Abundant expandability across surrounding terrain allows sustained suburban expansion while also encouraging urban residential density.
Coastal centers including Los Angeles, New York, Boston, and Honolulu face severe natural geographic barriers, high land acquisition costs, and complex regulatory frameworks. California’s Environmental Quality Act, or CEQA, is among the rules that can add years to approval timelines.
“Those places really have some advantages that the coastal cities don’t,” Berner said. “Land is much more available. … They’re also incentivizing these builders to produce dense urban housing as well as the kind of suburban developments that the developers have been working on for a number of years.”
Berner said municipal leaders addressing the nationwide housing imbalance should focus directly on regulatory governance. For local officials trying to improve long-term housing affordability and supply metrics, changing local regulatory frameworks is the most direct lever available.
“I think the first thing they should do is look at their local zoning ordinances,” Berner said.

One Comment