

30-Year Mortgage Rates Surge to 7.28%, Highest Since November 2023 as Treasury Yields Spike
A jump in the 10-year Treasury yield to 5.23% drove the sharpest weekly increase in home loan costs this year, deepening the affordability squeeze for buyers.
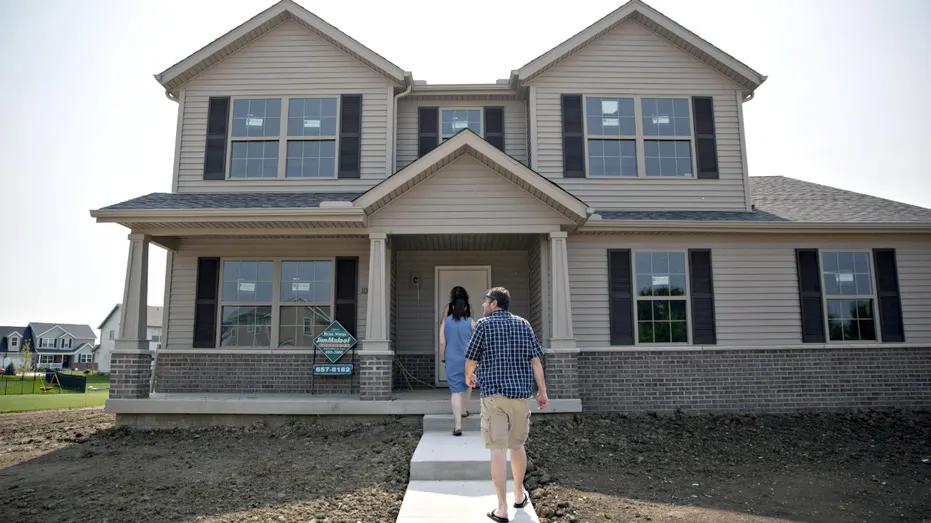
The cost of financing a home purchase in the United States jumped sharply this week, with the average rate on a 30-year fixed mortgage climbing to 7.28% from 7.03%, according to Freddie Mac’s Primary Mortgage Market Survey released Thursday. The surge pushes borrowing costs to their highest point since November 2023 and extends a widening gap with rates from a year ago, when the benchmark loan averaged 6.34%.
Shorter-term financing followed the same trajectory. The average rate on a 15-year fixed mortgage advanced to 6.6%, up from 6.42% the prior week. While 15-year loans typically carry lower rates than 30-year terms, they require significantly higher monthly payments, making them less accessible for buyers already strained by elevated prices.


The immediate catalyst for the weekly spike is a rapid repricing in the bond market. mortgage rates do not move in lockstep with the Federal Reserve’s short-term interest rate decisions. Instead, lenders price 30-year fixed loans primarily off the 10-year U.S. Treasury yield, adding a spread to account for prepayment risk and profit margins. As of Thursday afternoon, the 10-year yield hovered around 5.23%. Historically, the spread between the 10-year Treasury and the 30-year mortgage rate averages roughly 1.7 to 2 percentage points. The current spread has compressed, indicating that while Treasury yields are driving the baseline higher, mortgage-backed securities are facing their own distinct demand pressures.
Treasury yields have been climbing amid shifting expectations about the pace of future Fed rate cuts, persistent concerns over federal deficit spending, and geopolitical volatility that complicates inflation forecasts. When investors demand higher yields to hold government debt, mortgage rates inevitably follow, often within days.
Freddie Mac chief economist Sam Khater noted that despite the steep upward trajectory in borrowing costs, the broader housing market continues to find support from favorable underlying economic conditions. A resilient labor market and steady wage growth have kept a floor under buyer demand, even as affordability metrics deteriorate.
The practical impact of a near full-percentage-point increase over the past 12 months fundamentally alters purchasing power. On a $400,000 loan, the shift from 6.34% to 7.28% adds approximately $250 to a borrower’s monthly principal and interest payment, excluding taxes and insurance. That differential forces many prospective buyers to either lower their target price range or delay entering the market entirely.
This dynamic continues to exacerbate the so-called “lock-in effect,” where existing homeowners who secured rates between 2% and 4% during the pandemic-era refinancing boom refuse to sell, knowing a new purchase would mean trading a low rate for one above 7%. The resulting inventory shortage prevents home prices from falling proportionally with rising rates, creating an affordability squeeze unique to the current cycle compared to previous high-rate environments like the early 1980s, when property values adjusted more rapidly downward.
Lenders and real estate professionals are increasingly relying on temporary buydowns—where sellers or builders subsidize the buyer’s interest rate for the first one to three years of the loan—to bridge the affordability gap and close transactions. However, these arrangements add upfront costs and do not eliminate the long-term burden if rates remain elevated beyond the buydown period.
Freddie Mac compiles its weekly survey by polling lenders across the country, measuring rates offered to borrowers with strong credit scores and standard down payments. Actual rates available to individual consumers vary based on credit history, loan-to-value ratio, property type, and discount points paid at closing.
The latest reading reflects pricing data gathered through Wednesday, capturing the bond market’s reaction to recent macroeconomic developments heading into the final quarter of the year.

One Comment