France Riots Mirror U.S. Debt Trap, Not Culture War
Why economists warn the same debt crisis is coming in Paris and Washington
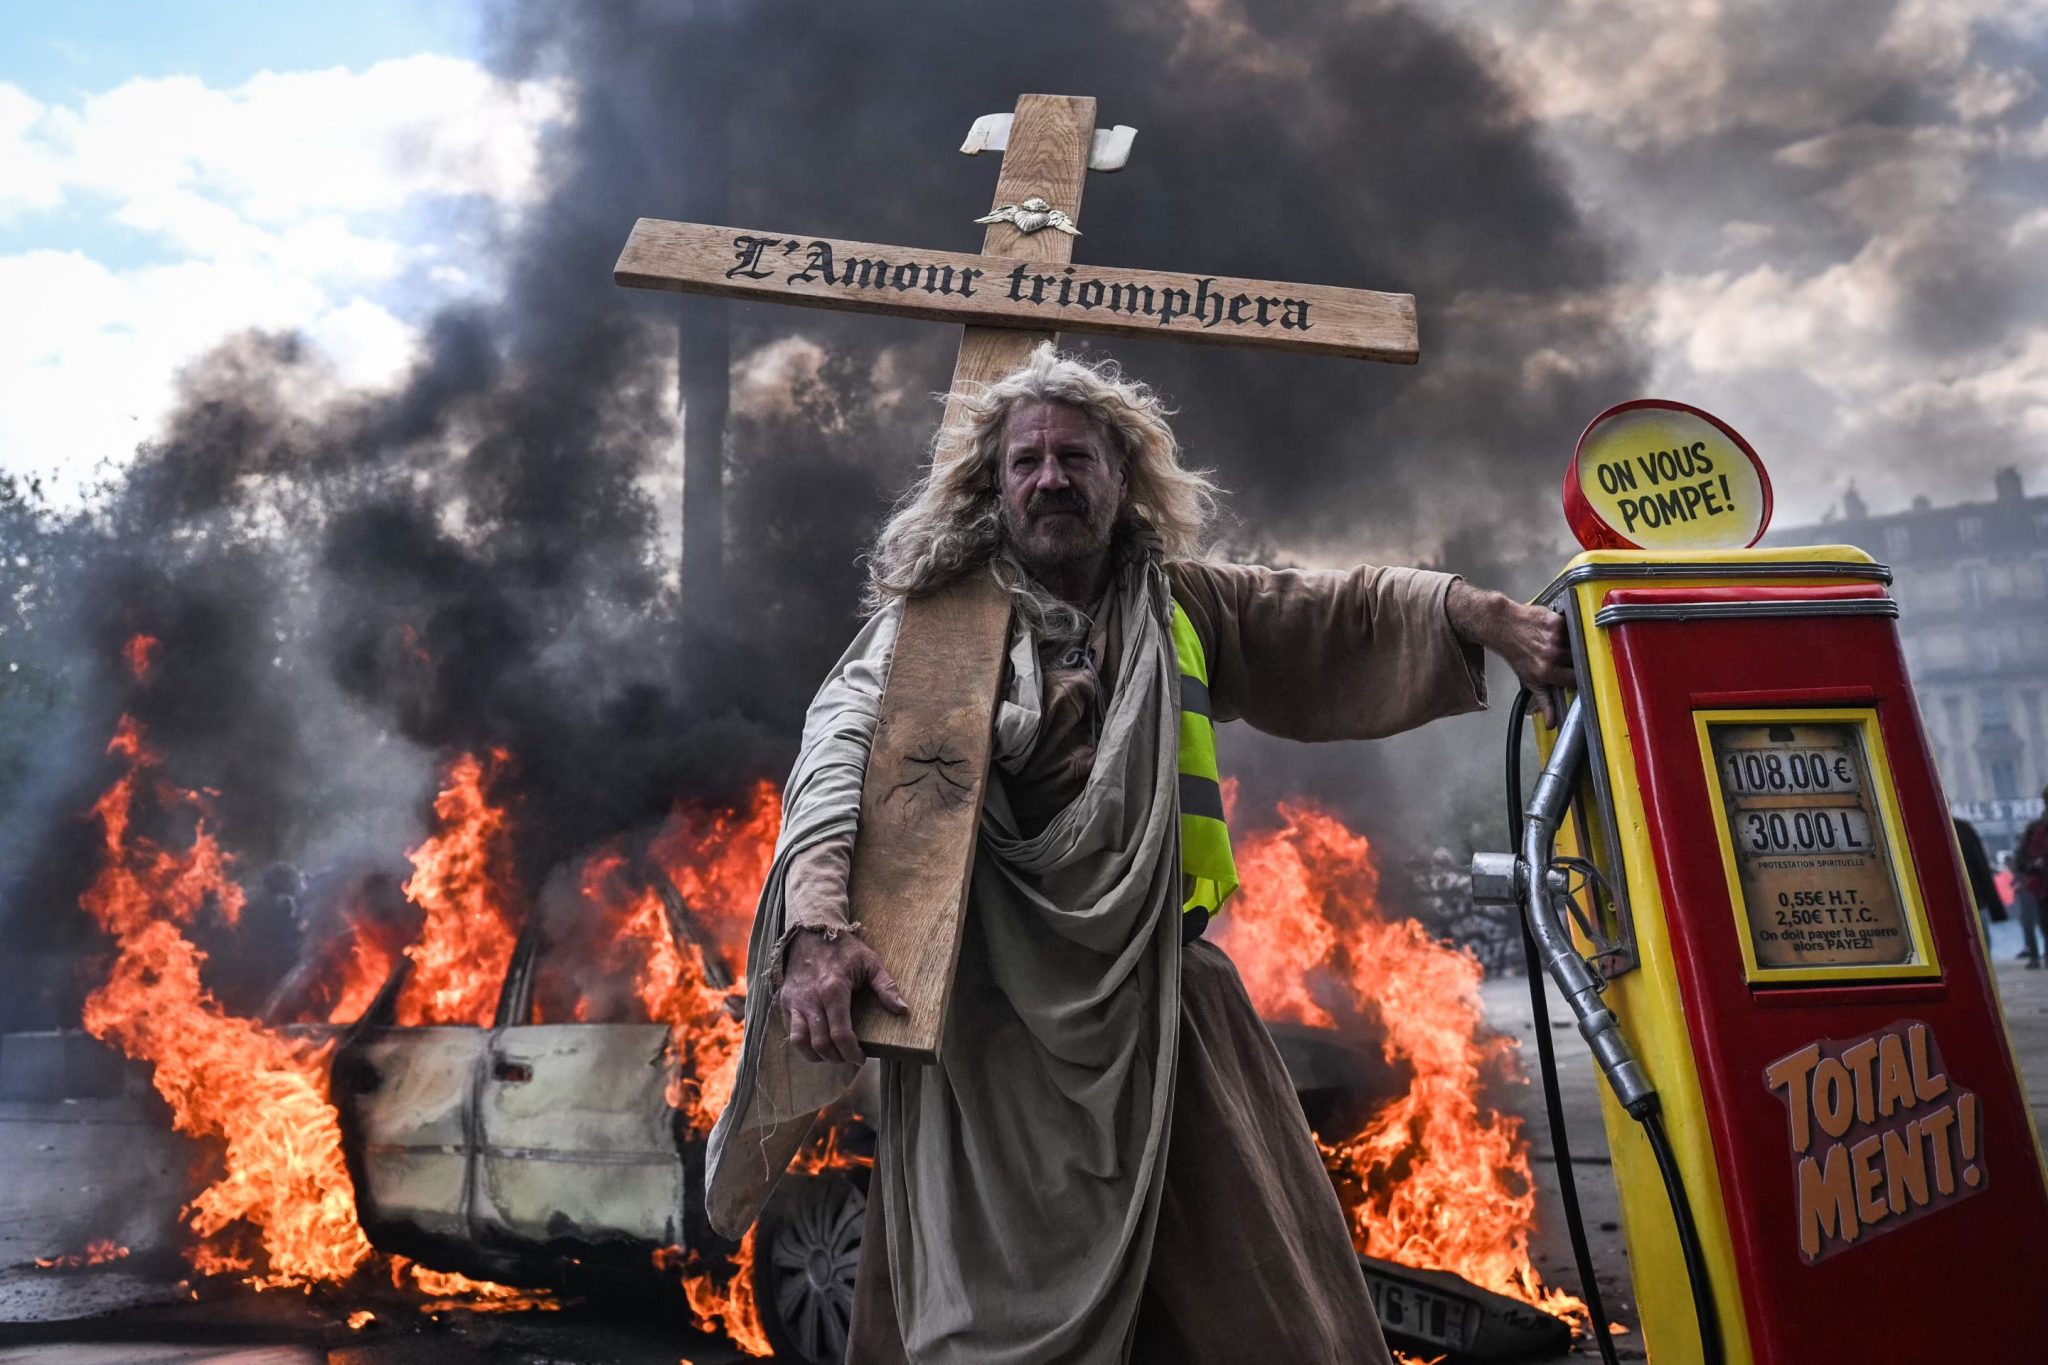
French officials say the blaze that gutted Limoges’ 19th-century city hall was arson. By Sunday the fire was contained, but the cost of the unrest is already staggering: more than 2,400 arrests on Saturday alone, nearly 1,000 police and gendarmes injured, and hundreds of businesses looted across Paris, Marseille and Lyon. Prime Minister Sébastien Lecornu ordered localized curfews on Monday; Interior Minister Laurent Nuñez admitted police “lost control” and offered his resignation. President Emmanuel Macron refused to accept it.
The spectacle is unfolding in a country where inflation runs below America’s. U.S. consumer prices rose 3.7% in the year through September versus France’s 3.4% on the EU-harmonized measure, Fortune’s Jason Ma reported. What makes the U.S. picture look different is growth. GDP expanded 2.2% in the second quarter, unemployment stands at 4.2%, and wages are climbing about 3.0% a year — still below inflation. France expects 0.5% growth this year, with youth unemployment near 20%.
Remove growth from the equation and the two fiscally strained democracies look frighteningly alike.
French public debt has hit a record 119% of GDP. U.S. debt held by the public reached 100.2% of GDP at the end of March. Lecornu’s budget, which would trim the deficit to 5% from 5.4%, heads into its first critical National Assembly vote Tuesday. Washington posted a $1.992 trillion deficit in fiscal 2026, roughly 6.2% of GDP by CBO projections — wider than the deficit France is rioting over.
Bond traders are pricing the risk identically. Bank of America economists Claudio Irigoyen and Antonio Gabriel found French and U.S. 10-year yields tracking nearly in lockstep, driven by the same logic: cheap debt invites larger deficits, and consolidation becomes politically impossible once rates rise. In the U.S., the market sent its warning before the streets did. On Sept. 8 Treasury Secretary Scott Bessent told a Southern Methodist University audience, “I am the house now.” Over the next three weeks the 30-year Treasury yield climbed to 5.69%, levels unseen since 2002, Johns Hopkins economist Steve Hanke and former Comptroller General David Walker wrote in Fortune.
That French anger, meanwhile, began in classrooms. Mid-September saw high-school students in the Paris suburbs walk out over missing teachers, overcrowded rooms and buildings that cannot handle the heat, blaming years of underinvestment. Teachers and unions joined them; fuel prices and the cost of living followed.
Nearly half of French districts had chronic facility problems that disrupted learning. At the start of this school year, 53% of middle and high schools were missing at least one teacher, a SNES-FSU survey of 1,033 schools found. Compare that with the U.S.: at the start of 2024–25, 74% of public schools struggled to fill at least one vacancy with a fully certified teacher, the National Center for Education Statistics reported. France’s secondary teaching force includes 11.1% not fully qualified, per the OECD; the Learning Policy Institute puts the U.S. shortfall at 387,843 uncertified assignments and calls that an undercount.
President Trump offered a different reading. On Truth Social on Oct. 6 he called the unrest “out-of-control mass migration” and claimed it “isn’t about schools, this is about Islam wanting to take over a once great country,” without addressing the fiscal parallels at home. Student demands have not mentioned immigration or religion. UBS Global Wealth Management chief economist Paul Donovan described the weekend’s violence to clients Monday as “a different form of scapegoat economics.”
The cushion holds only as long as growth does. Market veteran Ed Yardeni argued last month the U.S. economy is “less rate sensitive than it has ever been,” propped by wealthy retirees, large deficits and “an extraordinary AI investment boom.” Yet that boom carries its own baggage: tech investment accounts for roughly a third of U.S. GDP growth, according to ING, while 39% of Americans now say AI does more harm than good, up from 31% a year ago, and 79% expect AI to cut U.S. jobs over the next decade, a Bentley-Gallup survey conducted in May found. Among adults under 30, 47% see more harm than good; a June Pew survey found 52% more concerned than excited.
Hanke and Walker end their column quoting MIT economist Rüdiger Dornbusch: “Crises take longer to arrive than you can possibly imagine, but when they do come, they happen faster than you can possibly imagine.”
Generative AI was used for research assistance and/or transcription of this article. The reporter independently reported and verified the factual claims in this article, and a human editor reviewed it before publication.