French Bond Yields Hit 24-Year High as Protests Spread
Student demonstrations over school conditions escalated into nationwide unrest as inflation accelerated to 3.4% and wage growth stalled.
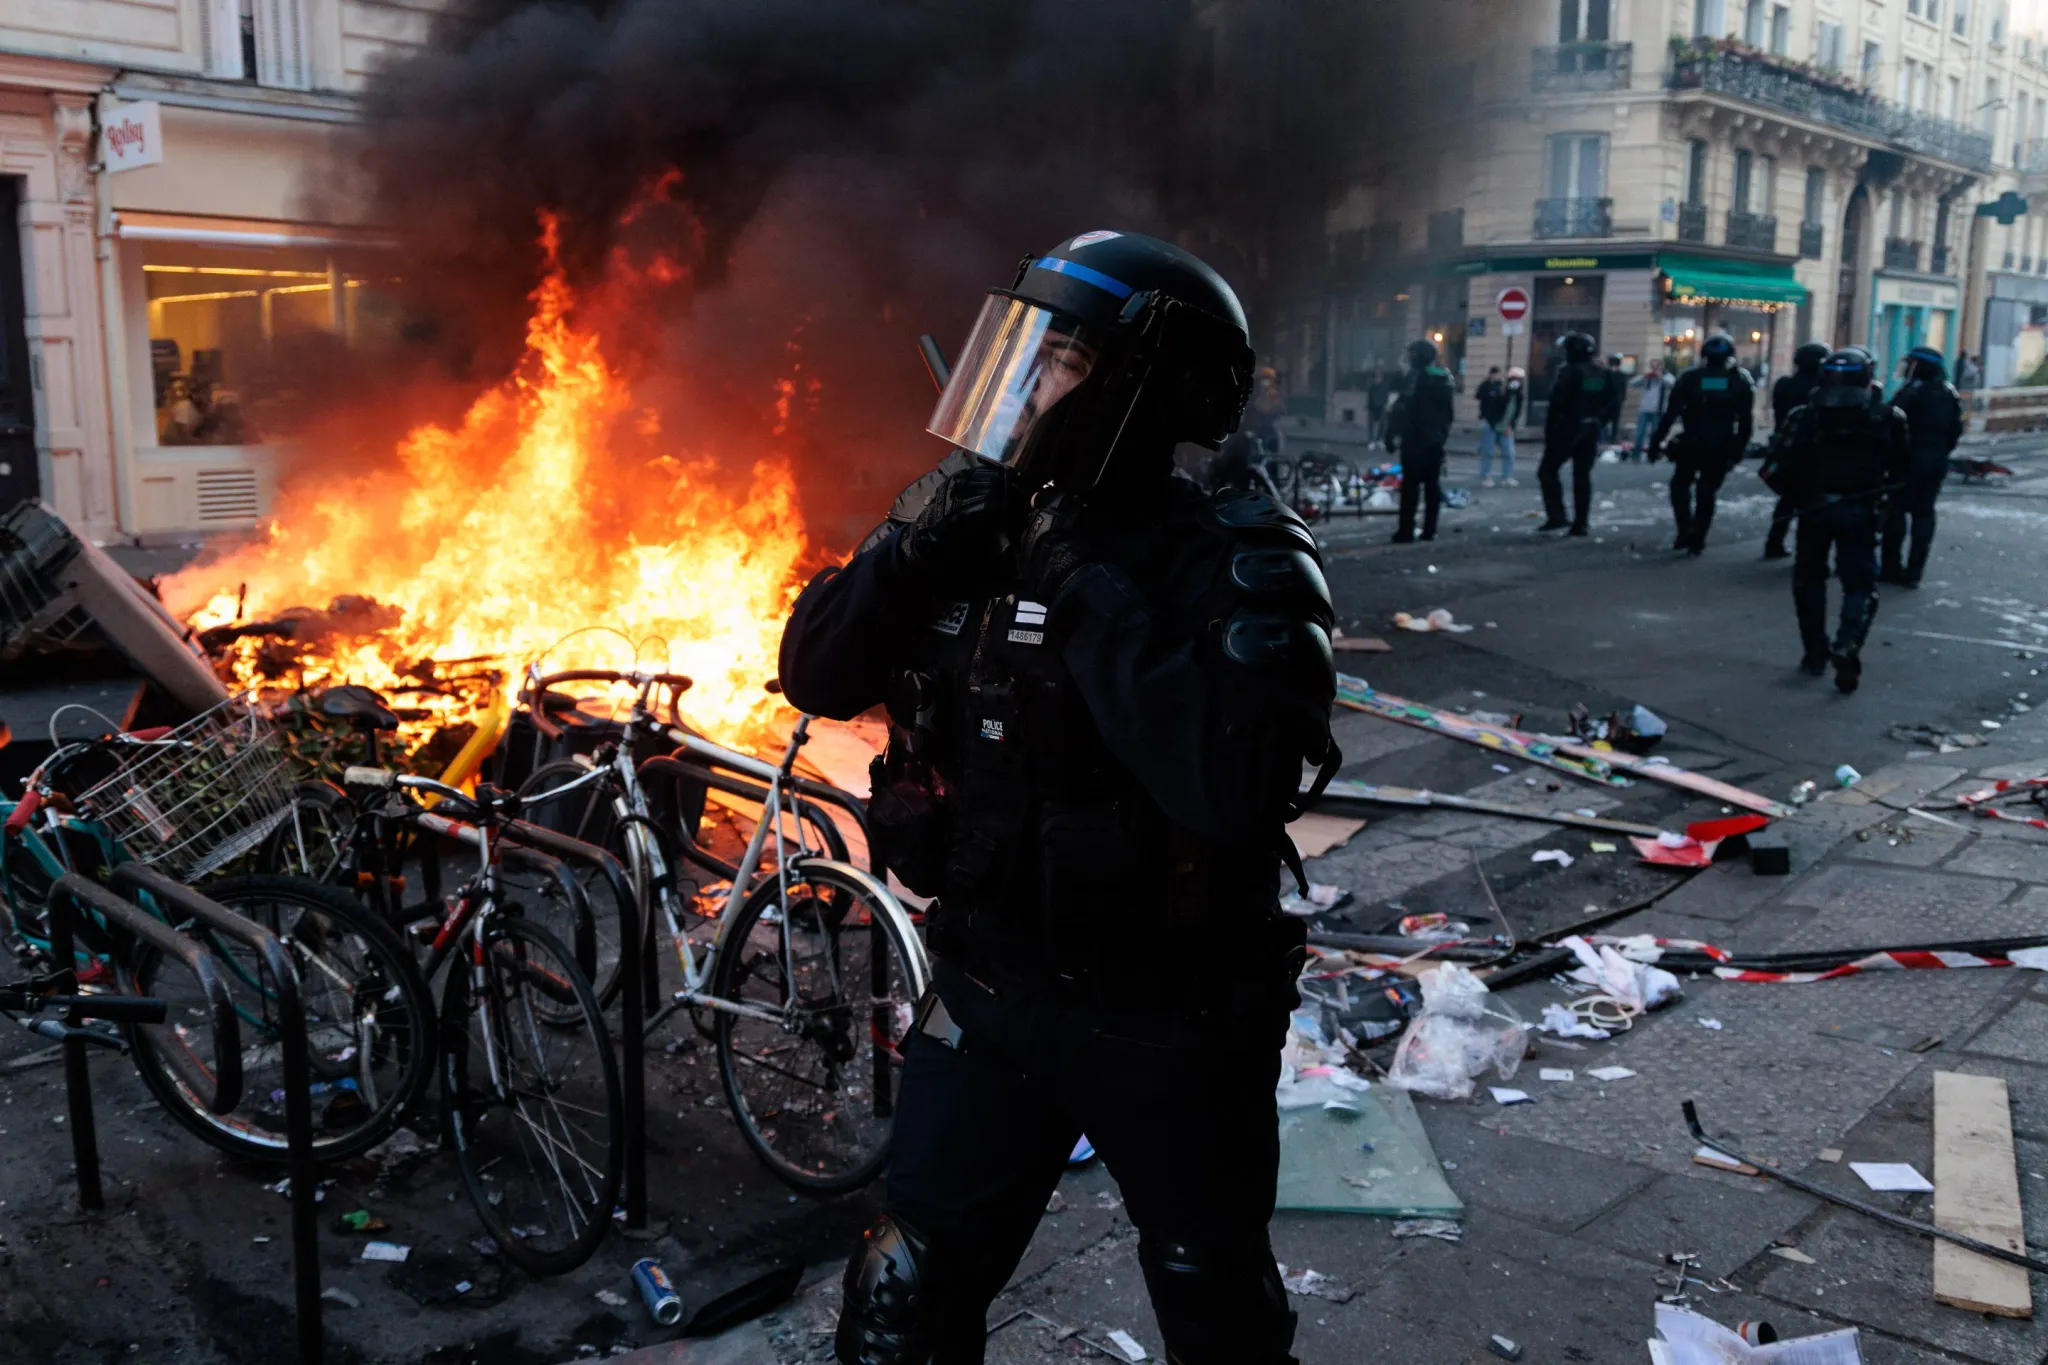
French government bond yields surged to their highest levels in 24 years this month, signaling a loss of investor confidence that parallels the 2011 eurozone debt crisis. The spike coincides with nationwide protests and a sharp acceleration in consumer prices that has pushed the country into stagflation.
Consumer prices climbed 3.4% in September from a year earlier, according to official data. That marks the fastest annual pace since January 2024 and a steep jump from August’s 2.6% rate. Fuel costs have driven much of the increase following the U.S. war on Iran.
Demonstrations began last month when students protested deteriorating school infrastructure, citing run-down classrooms, missing teachers, and buildings unable to handle rising temperatures. Police tactics against those student protestors drew wider crowds. The marches quickly pivoted toward broader economic grievances, specifically the high cost of living.
Wages are not keeping up. The average negotiated wage increase sat at just 1.7% in the second quarter and has remained largely flat for several quarters, according to the Bank of France. Unemployment exceeds 8%, while youth joblessness stands at 20%.
The government slashed its 2026 GDP growth forecast to 0.5% from 0.7%. The economy expanded 0.9% in 2025.
Bond markets have reacted violently to the combination of profligate spending, soaring debt, and sluggish output. Investors see little prospect of fiscal discipline returning before the spring presidential election, where populist candidates from the far right and far left currently lead polling.
Mujtaba Rahman, managing director for Europe at Eurasia Group, wrote in a New York Times op-ed Thursday that the country faces overlapping crises of liberal democracy, fiscal mismanagement, and youth disaffection. “But the fiscal crisis is the most dangerous, underlying many of the country’s woes and threatening to bring it to ruin,” Rahman wrote. “France, truly, is on the brink.”
Affordability pressures are straining other major economies. In the United States, inflation remains a central issue in midterm elections expected to punish Republicans severely. Annual U.S. inflation tracked 3.7% in the latest consumer price index report.
U.S. borrowing costs have also climbed, with bond yields surging past 5%. But American rates reflect a fundamentally different economic reality. Gross domestic product rose 2.2% in the second quarter, with third-quarter growth projected at 3.6%. The national debt has reached $40 trillion, yet the dollar’s status as the global reserve currency and an AI-driven investment boom continue to shield U.S. markets from the type of sovereign risk repricing hitting Europe.
The Federal Reserve hiked interest rates last month and is expected to raise them again. The U.S. jobless rate holds at 4.2%, roughly half the French level, with youth unemployment near 10% and annual wage growth tracking around 3.9%.
“The economy is less rate sensitive than it has ever been because it is more services-heavy, increasingly supported by wealthy and lightly indebted retirees, and stimulated by large fiscal deficits and an extraordinary AI investment boom,” market veteran Ed Yardeni wrote in a note last month. “At the same time, strong demand for capital and weaker growth in national saving may have pushed the neutral interest rate higher. That’s why higher interest rates haven’t produced the widely expected effect of weakening economic growth with a lag, nor do we expect they will.”