

Can London’s Stock Exchange Reverse Its Wall Street Exodus?
LSE 24 and new listing rules target London’s decade-long decline
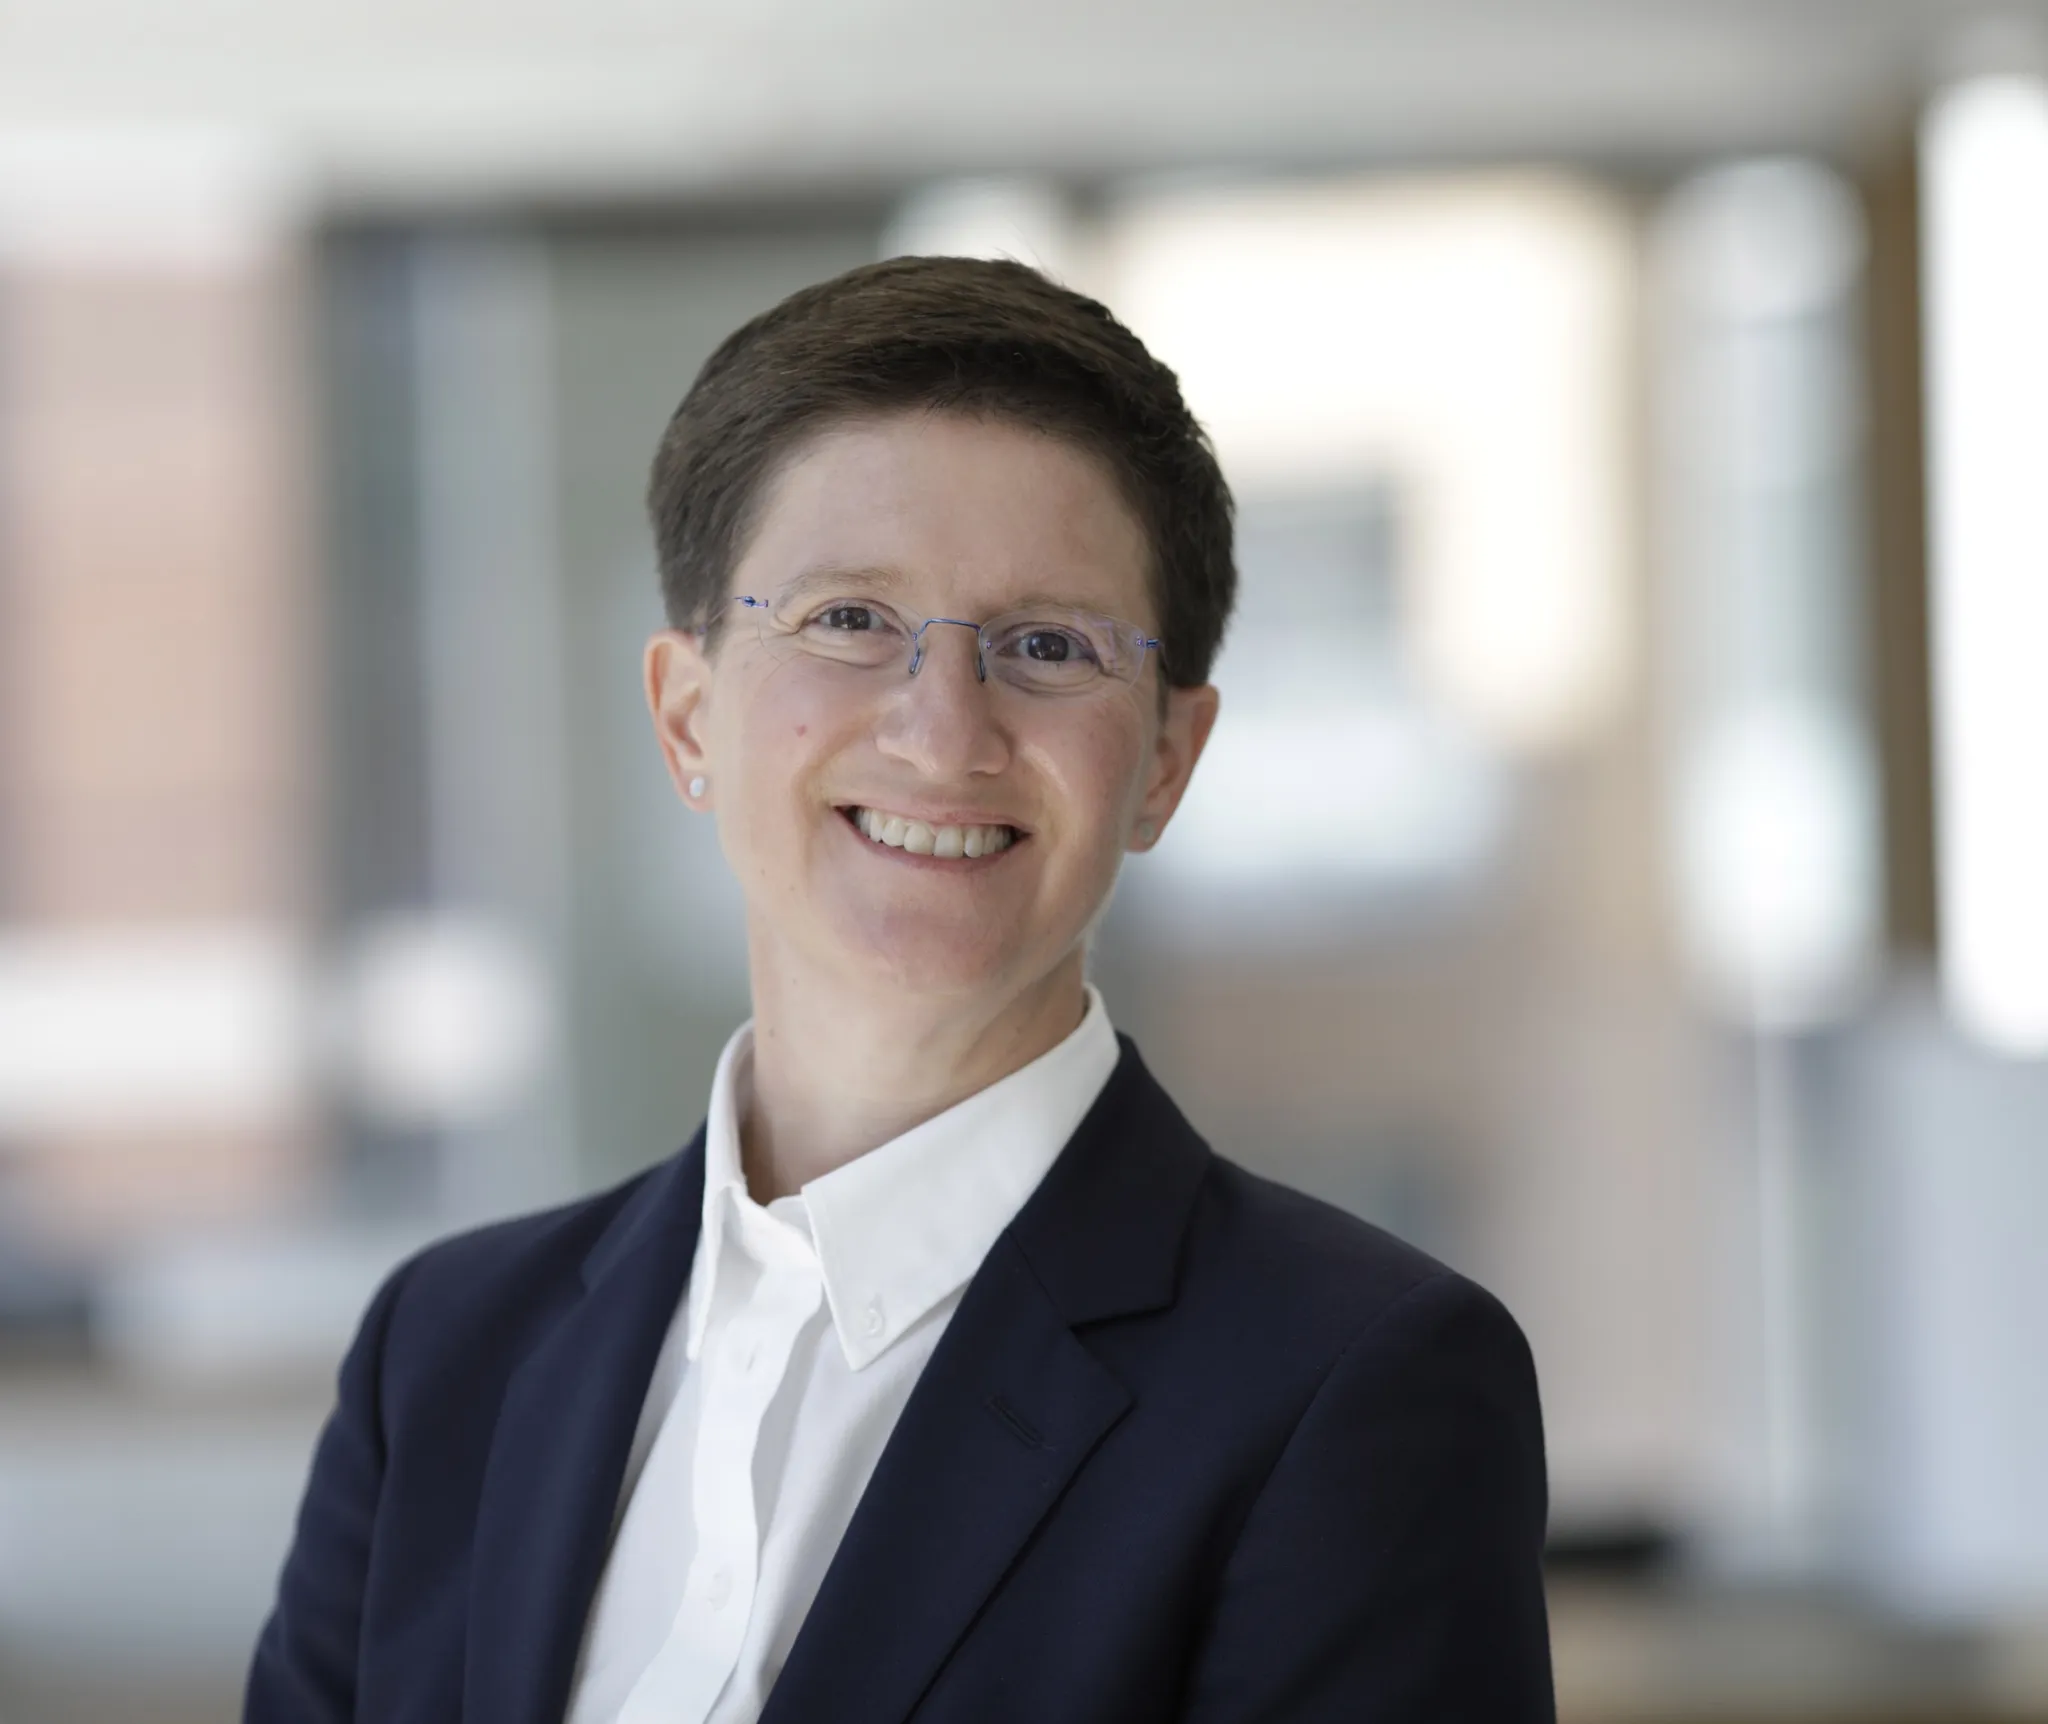
LONDON — London Stock Exchange chief executive Julia Hoggett says the exchange’s primary listing pipeline is at its strongest level since 2005, while EY data shows that U.K. IPO proceeds more than tripled in the first half of 2026 compared with the same period in 2025. London also remained Europe’s largest capital market, hosting more than twice as many equity offerings as its nearest continental rival during the first six months of the year.
The figures arrive as the exchange prepares “LSE 24,” a planned 24-hour trading platform for institutional and retail investors to trade digital versions of traditional stocks. The project is being developed with a newly created Digital Securities Depository and the U.S.-based cryptocurrency exchange Kraken. Client testing is scheduled to begin by the end of this year, with a target launch in the first half of 2027.
London’s regulatory overhaul began in July 2024, when the Financial Conduct Authority (FCA) simplified the listing rulebook by combining the historic “premium” and “standard” segments into one category for commercial companies. The reforms also removed the requirement for shareholder approval of major acquisitions and disposals, previously known as Class 1 transactions, which British companies said left them at a disadvantage in competitive bidding wars.
The same changes legalized more flexible dual-class share structures, allowing founders to retain enhanced voting rights indefinitely under certain conditions. The LSE has also eased regulatory requirements on the Alternative Investment Market (AIM), its junior board for smaller growth companies, and created the Private Securities Market, where private enterprises can trade existing shares intermittently without completing a full public flotation.
Yet LSE data compiled by Statista records a steep decline in the number of companies listed on the exchange, from 2,429 in 2015 to 1,534 as of May 2026, a post-financial crisis low. More than 30 companies have exited or announced plans to leave the London market this year, including asset manager Schroders and budget carrier easyJet, both of which have agreed to U.S. private equity or corporate takeovers.
Earlier departures included building materials giant CRH, which moved its primary listing from London to New York in 2023. Plumbing equipment distributor Ferguson and gambling conglomerate Flutter Entertainment followed, with Flutter completing its primary listing transition to the New York Stock Exchange in May 2024. In late 2023, Cambridge-based semiconductor designer Arm Holdings chose the Nasdaq for its $4.87 billion initial public offering, bypassing London despite intense lobbying by the British government.
Critics such as Octopus Energy founder Greg Jackson have called for the exchange to show more “hustle” to win back global IPOs. Hoggett, who has led the LSE since 2021, rejects the idea of terminal decline and describes the difficulties as part of a global shift in public markets rather than a uniquely British crisis.
Between 1980 and 2000, the United States averaged more than 300 IPOs per year, but that figure had fallen to 90 by 2025. “The U.K. was the last major market to make that shift,” Hoggett said. “I suspect that’s why commentators have mistaken a global structural shift for a specifically British problem.”
Early corporate activity has provided mixed signals. PwC’s U.K. M&A Mid-Year Outlook found that the total value of British mergers and acquisitions more than doubled to £124.2 billion ($167.8 billion) in the first half of 2026 compared with the previous year, even as the overall number of deals declined.
London’s international reach was illustrated by the listing of Uzbekistan’s National Investment Fund earlier this year. The debut raised approximately $603 million and was Uzbekistan’s first international equity offering. It was one of only seven IPOs completed in London during the first half of 2026, however, with those offerings raising a combined $780 million. Over the same period, the U.S. market completed 72 IPOs and raised $128 billion.
Hoggett cautions against comparing markets solely by volume. LSE data covering 21 U.K. companies that listed in the United States since 2014 shows that only four are currently trading above their offering price. Thirteen have delisted, while the remaining four are trading down by an average of 71%.
She also points to an advantage for mid-sized firms under LSE rules: companies in the mid-market can qualify for major domestic stock indexes almost immediately after listing. That can prompt automatic purchases by index-tracking exchange-traded funds (ETFs) and pension funds required to hold those benchmarks. In the United States, a comparable benefit is generally reserved for large-cap companies entering the S&P 500 or Nasdaq-100.
“We need to stop creating these false binaries,” Hoggett said. “Capital markets are a vital, direct driver of growth, jobs, and national prosperity that most countries treat as a matter of economic sovereignty.”
The domestic investment base remains a major constraint. British pension funds once held a significant share of their portfolios in domestic equities, but accounting changes and a shift toward fixed-income assets over the past two decades have sharply reduced local demand for U.K. stocks.
The government’s Mansion House Reforms, launched in 2023, seek to direct billions of pounds from defined-contribution pension funds into unlisted equities and high-growth companies. Hoggett has called for additional structural tax and policy incentives to return domestic capital to the market. The U.K. still applies a 0.5% Stamp Duty Reserve Tax (SDRT) to purchases of British shares, a transaction tax that does not exist in the United States.
She has also noted that pension tax reliefs worth £50 billion ($67.5 billion) annually and Individual Savings Account (ISA) reliefs worth £9 billion ($12.1 billion) annually do not require any part of those funds to be invested in domestic assets.
“If we are going to give you fiscal incentives to invest, we’d like at least a portion of that to be backing Britain,” Hoggett said. “We have a culture focused on protecting people from downside risk rather than exposing them to upside potential.”
Britain continues to produce scale-up businesses despite those capital constraints. Data from the Hurun Research Institute indicates that the country generates more billion-dollar startups than any nation except the United States and China. Britain also took the top position in the 2026 measuresHE Country 100 ranking, which assesses national scientific and academic research ecosystems.
“Most founders put their money, their mortgage, and quite often their marriage on the line to create great companies,” Hoggett said. “We as a society should respect the fact that they’re taking that risk. My job is to continue to make the U.K. ecosystem as effective as possible to make it more straightforward for them to achieve those aspirations.”
One Comment