Tesla-SpaceX Merger Tests Limits of Musk’s Voting Control
SpaceX's 10-to-1 super-voting shares and recent xAI dealings complicate the path to a $3.5 trillion combination.
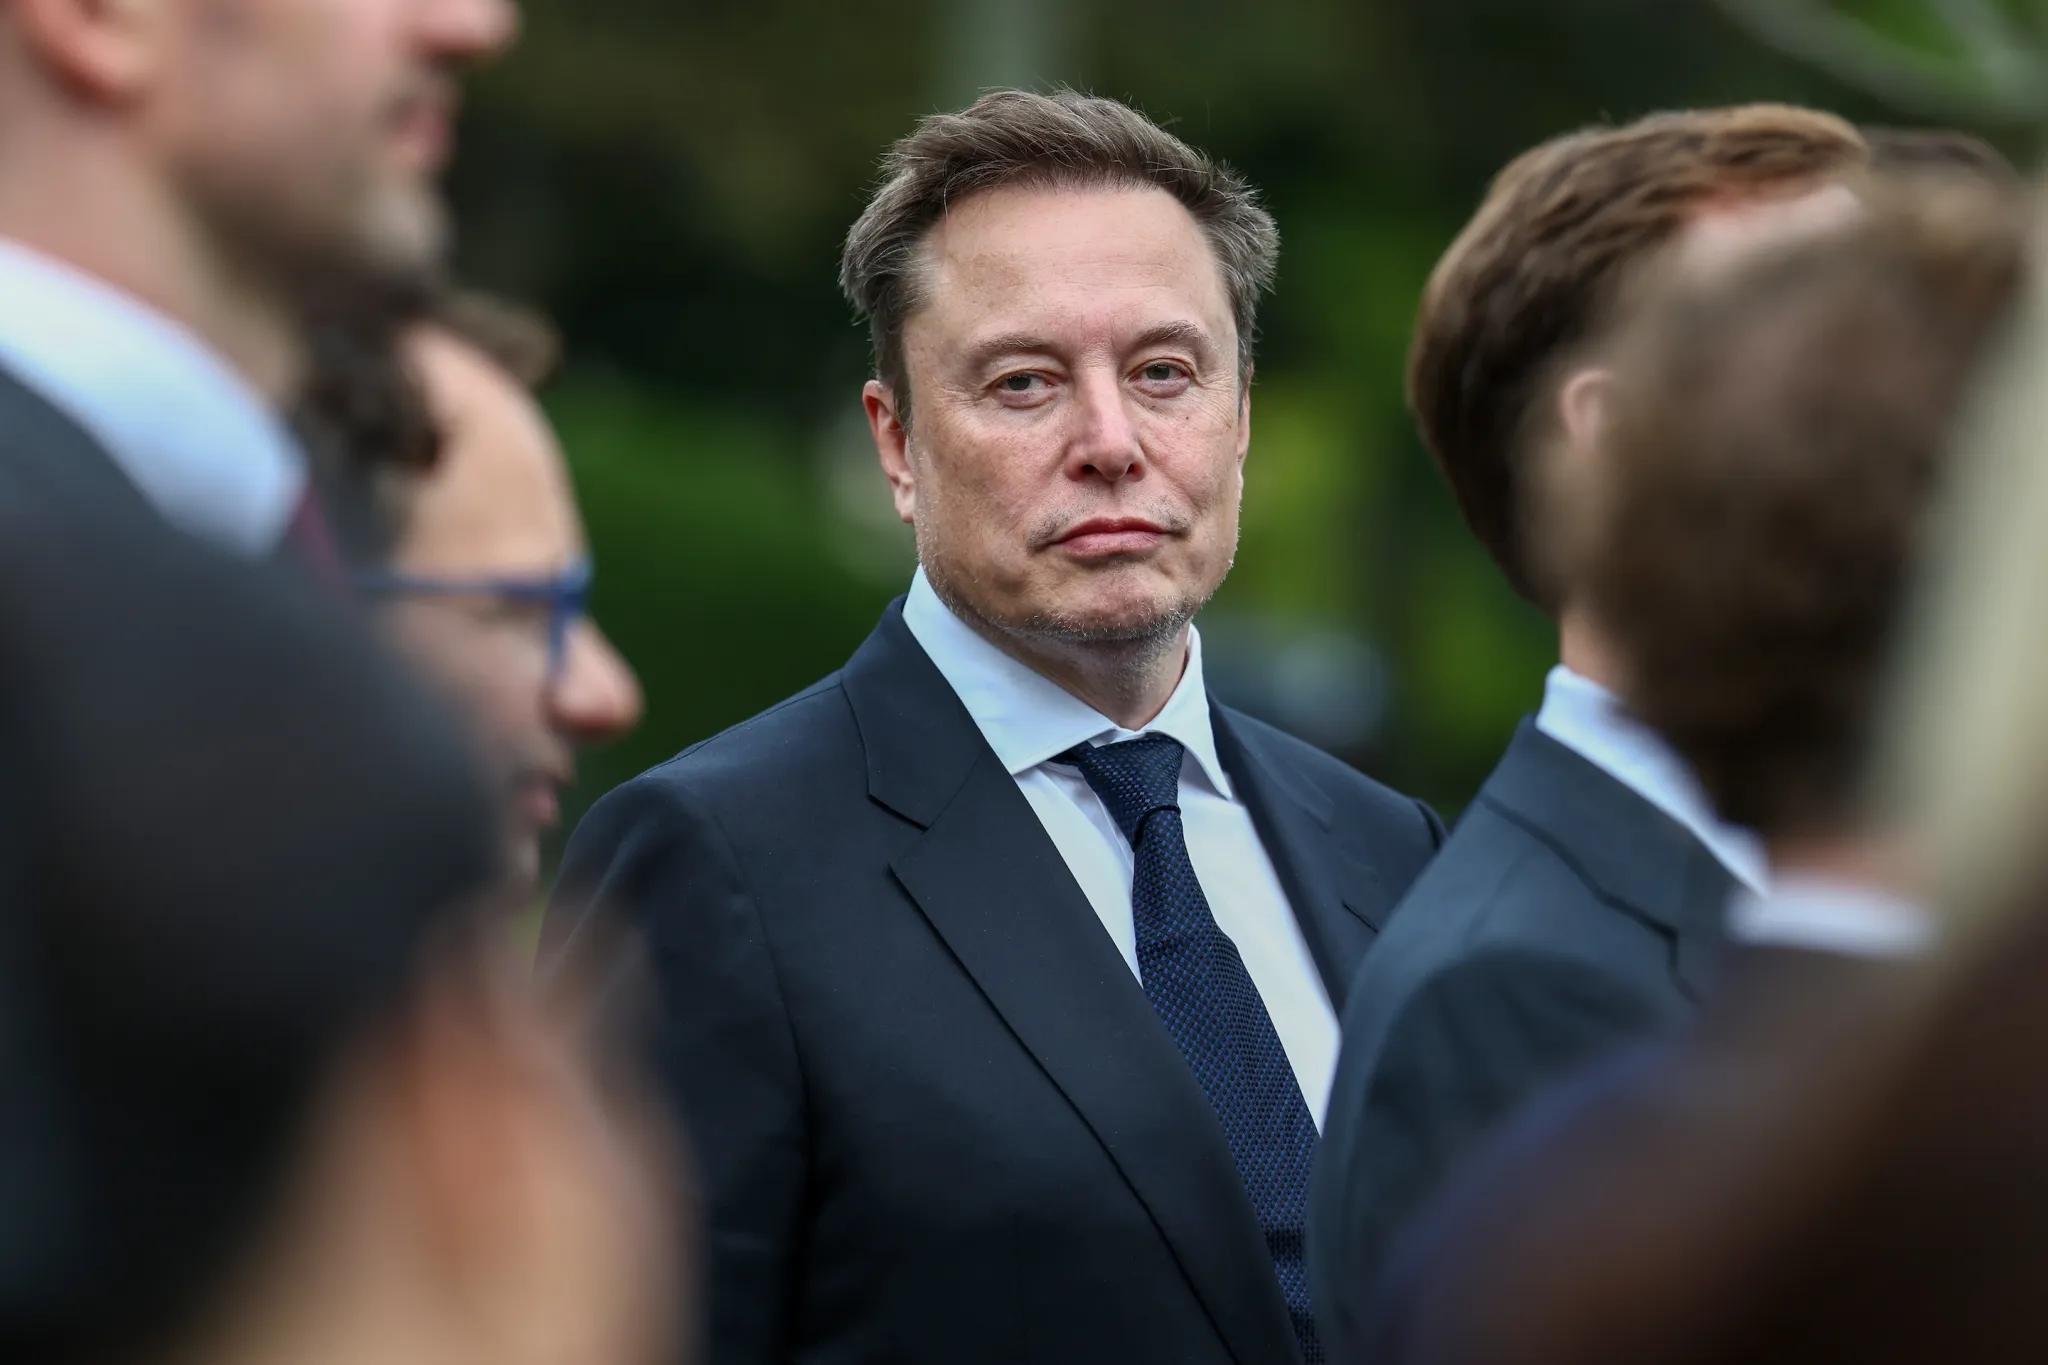
A potential combination of Tesla and SpaceX would force the first real stress test of the dual-class share structure that insulates Elon Musk from outside investors. Independent directors at both companies have formed special committees to explore a merger that, according to Musk, would create an entity valued at roughly $3.5 trillion.
Musk said on SpaceX’s third-quarter earnings call Tuesday that he cannot participate in the talks because he is a “conflicted party.” He described the situation as “tap dancing through a minefield” and cautioned that calling a deal certain would be “overstating it.”
The mechanics of any transaction hinge entirely on how SpaceX priced its shares when it went public under the ticker SPCX on June 12. The company listed at $135 and closed its first day at $161.11, pushing its market value past $2 trillion during the session, according to its IPO filing.
That offering established a multi-class share structure where Class B shares carry 10 votes apiece. Musk owns about 45% of SpaceX but controls roughly 82% of its voting power, Fortune reported. Only Class B holders can remove him as CEO, chairman, or director. The company relies on the “controlled company” exemption to avoid maintaining a majority-independent board or independent nominating and compensation committees.
Combining a publicly traded automaker with a rocket manufacturer governed by these terms creates immediate friction for institutional shareholders. In a May 13 letter, CalPERS and the New York City and New York State comptrollers warned that SpaceX’s setup “would constitute the most management-favorable governance structure ever brought to the U.S. markets at this scale.”
SpaceX reincorporated from Delaware to Texas in 2024. Its charter pushes shareholder claims into mandatory arbitration and limits derivative suits to investors holding at least 3% of the stock—a threshold worth tens of billions of dollars.
Recent transactions between Musk-controlled entities illustrate why proxy advisors and large funds are scrutinizing the proposed tie-up. In November 2025, Tesla shareholders weighed a nonbinding proposal for the carmaker to invest in xAI, Musk’s artificial intelligence startup. About 1.06 billion shares voted for it and 916.3 million against, with more than 473 million abstaining. Because Tesla’s bylaws count abstentions as votes against, the measure failed, Bloomberg reported.
In January, Tesla disclosed a $2 billion investment in xAI anyway. “We’re just doing what shareholders asked us to do, pretty much,” Musk said. Days later, SpaceX acquired xAI in a deal valuing the combined company at $1.25 trillion.
Tesla also conducted more than $573 million in business with Musk-controlled companies in fiscal 2025, including $430.1 million in Megapack battery sales to xAI and $143.3 million in Cybertruck sales to SpaceX, according to an analysis of SEC filings by Transparency Lab. Tesla’s audit committee deemed the deals to be at arm’s length, and the analysis does not allege illegal conduct.
Regulatory precedent offers little comfort to minority shareholders seeking intervention. The Securities and Exchange Commission sued Musk in January 2025, alleging he waited too long to disclose his Twitter stake and cost other shareholders more than $150 million. He settled for a $1.5 million penalty without admitting wrongdoing. U.S. District Judge Sparkle Sooknanan approved the deal in July despite “serious misgivings,” noting the court is “not a rubber stamp” but can reject only settlements that are clearly unreasonable.
Courts have similarly constrained federal agencies attempting to regulate Musk’s corporate conduct. In 2018, he tweeted: “Nothing stopping Tesla team at our car plant from voting union… But why pay union dues & give up stock options for nothing?” The National Labor Relations Board ruled the post was an illegal threat. A Fifth Circuit panel upheld that decision in 2023, but the full court reheard the case in January 2024 and ruled 9-8 in October 2024 that the NLRB had no power to order the tweet removed, citing the First Amendment.
Operational risks compound the governance questions. A TechCrunch analysis of OSHA data found SpaceX’s Starbase site in South Texas recorded 4.27 injuries per 100 workers in 2024—almost six times the average for comparable space-vehicle manufacturers and nearly triple the 1.6 rate for aerospace manufacturing overall. Rival sites run by United Launch Alliance and Blue Origin reported rates near 1.1.
NASA is paying SpaceX more than $4 billion for two crewed Starship landings on the moon. Under those contracts, a high injury rate alone does not meet the definition of a “major breach of safety,” which covers events such as a fatality or a willful or repeat OSHA violation, TechCrunch reported. In January, OSHA cited SpaceX for seven “serious” violations tied to a June 2025 crane collapse at Starbase, with penalties totaling $115,850; SpaceX is contesting them. On May 15, a worker died at the site, prompting an ongoing OSHA investigation.
Musk’s personal wealth remains tethered to SpaceX’s stock performance. His IPO filing showed holdings of about 4.8 billion shares plus 350 million options exercisable at $8.39 each—enough to push his net worth past $1 trillion at the offering price, CBS News reported. Forbes said he regained trillionaire status on Oct. 9, then pegged his net worth at $977.2 billion on Oct. 13 after shares slid. Much of that equity is subject to a one-year lockup.
The SpaceX board set aside 1 billion super-voting shares for Musk that vest only if the company hits market-cap milestones of up to $7.5 trillion and establishes “a permanent human colony on Mars with at least 1 million inhabitants.”
About 4,400 SpaceX employees stood to become millionaires once the stock began trading, the New York Times reported. Fortune profiled workers from top executives to welders whose equity is now worth seven figures or more.
Musk stated that a Tesla-SpaceX combination would require approval from a majority of all outstanding Tesla shares, calling it “quite a high hurdle.” Tesla’s annual proxy, filed Monday, includes no merger proposal.