10-Year Treasury Yield Hits 2002 High: Impact on Mortgages and Savers
Geopolitical risks and AI debt drive borrowing costs higher while boosting saver returns
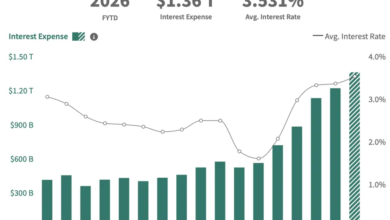
The benchmark 10-year U.S. Treasury yield climbed to 5.34% during Thursday trading, reaching its highest intraday level since 2002 before retreating slightly into Friday. This surge signals a structural shift in borrowing costs driven by converging pressures: geopolitical instability stemming from the Iran war and Strait of Hormuz disruptions, widening federal budget deficits, tighter monetary policy, and increased corporate debt issuance linked to artificial intelligence infrastructure expansion.
For American households, the immediate consequence is more expensive debt servicing. The 10-year note serves as the primary benchmark for 30-year fixed mortgage rates, which have now surged to their highest levels since 2023. Auto loans and fixed-rate student loans follow similar pricing mechanisms tied to longer-dated government debt. Brian Therien, senior analyst at Edward Jones, noted that adjustable-rate products such as credit cards and home equity lines of credit face direct pressure, though these are typically more sensitive to short-term benchmark rates. Consumers seeking new financing should anticipate elevated monthly payments across most loan categories despite continued labor market resilience.
Higher yields simultaneously create opportunities for savers and fixed-income investors who have endured years of suppressed returns. High-yield savings accounts, money market funds, certificates of deposit, and newly issued bonds now offer materially better income generation than earlier in 2026. Peter C. Earle, senior director of research at the American Institute for Economic Research, explained that investors reinvesting maturing holdings can secure stronger yields without assuming corporate credit risk. For long-term bond buyers, a larger portion of expected total return now derives from interest income rather than price appreciation, improving portfolio stability if held to maturity.
Risks remain for those who may need to sell bonds before maturity. Treasury prices move inversely to yields, meaning further rate increases would erode market values for existing holders. Real purchasing power gains also depend on inflation trends and tax treatment; nominal yield improvements do not automatically translate to higher after-tax real returns. The Federal Reserve’s preferred inflation gauge showed cooling in August but remains above target, complicating the outlook for both borrowers and savers navigating this rate environment.
Corporate borrowing costs are rising alongside household expenses, potentially constraining business investment and hiring even as consumer spending holds steady. The September jobs report showed 29,000 positions added, below expectations and suggesting some labor market moderation amid tighter financial conditions. Stock valuations face downward pressure as discount rates climb, while retirement portfolios must balance higher income potential against mark-to-market losses in existing bond holdings.
Treasury yields retreated from Thursday’s peak heading into the weekend, but the underlying drivers—geopolitical risk premiums, fiscal deficits, AI-related capital demands, and monetary tightening—remain active forces shaping the rate trajectory.