The Great Wealth Divergence: Why Younger Americans Are Abandoning the Housing Market for Equities
Escalating seller concessions highlight a buyer's market as equities continue to outpace residential real estate returns.
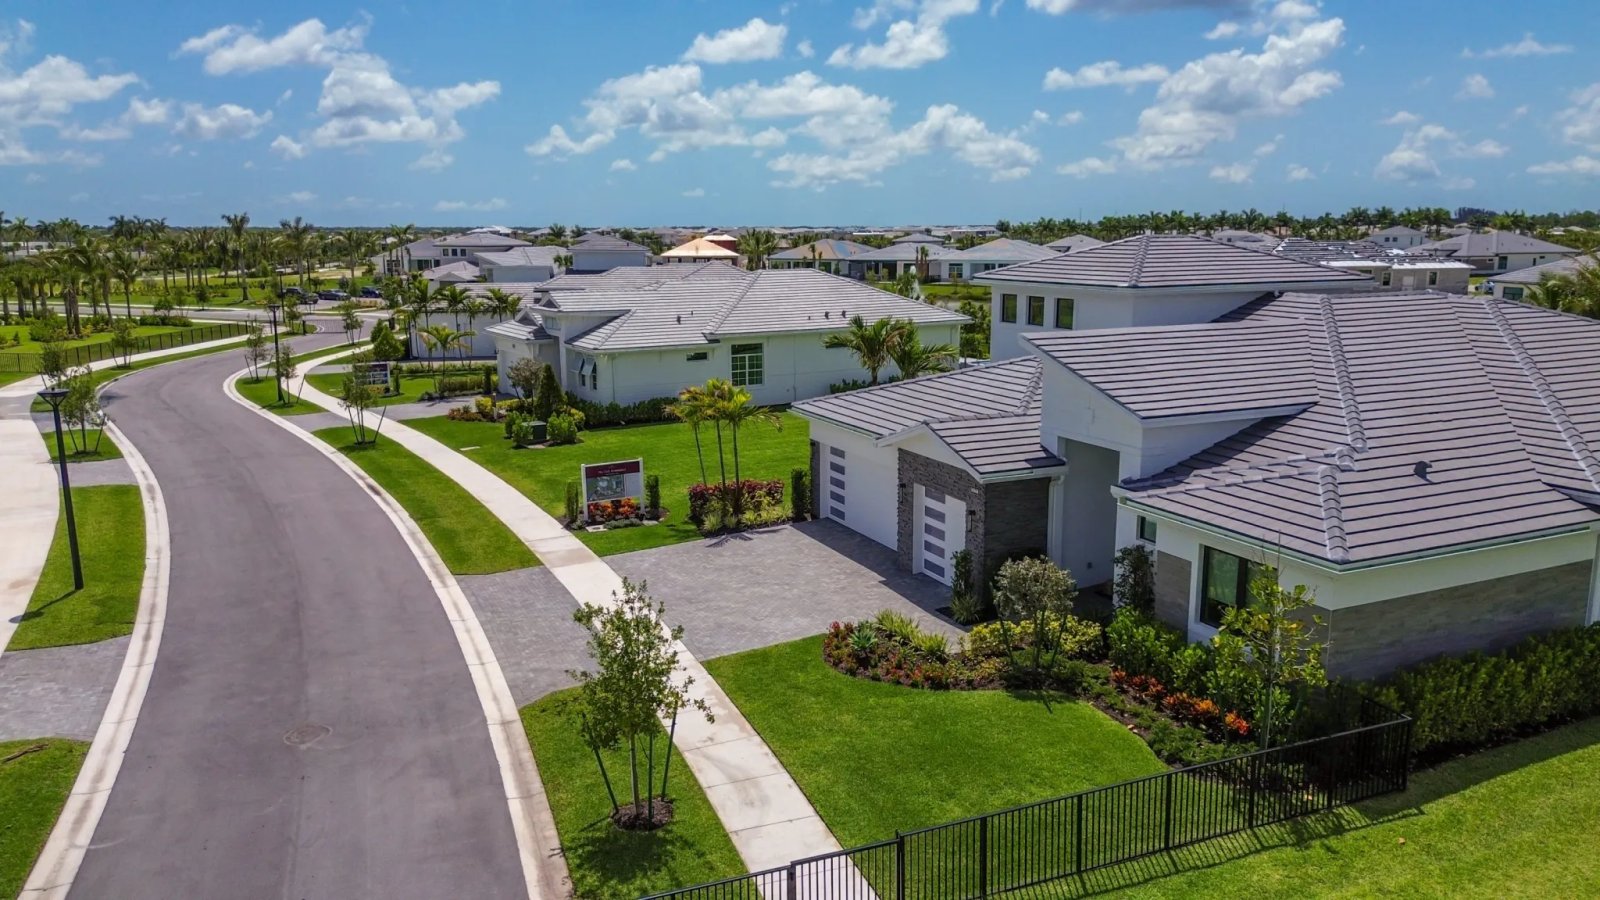
A generational shift in wealth accumulation is underway, driven by a stark divergence between the real estate and equity markets. For younger demographics, the traditional milestone of purchasing a primary residence increasingly looks like a suboptimal financial strategy compared to building a stock portfolio.
Over the last decade, the math has fundamentally altered the calculus of wealth building. Between late 2015 and late 2025, a benchmark of U.S. home prices climbed 87%, while the S&P 500 surged 235%—a gap that widens further when accounting for stock dividends. The recent resurgence of mortgage rates above 7% has only deepened this chasm, diminishing the affordability of real estate while an artificial intelligence-driven rally continues to propel equities to record highs.
Economists Ray Fisman and Michael Luca argue that this disparity exposes a widespread financial miscalculation: the conflation of shelter needs with investment strategy. When a household buys a house, they are simultaneously making a consumption choice and a massive, concentrated bet on a single asset class. The U.S. tax code offers deductions that partially offset this risk, yet the underlying return on investment remains sluggish. In the current year, national home prices have risen just 1.5%, whereas the stock market has advanced 13%, even amid geopolitical instability and fears of a tech bubble.
The allure of real estate has historically relied on the mechanics of leverage. A buyer putting 20% down on a property that appreciates by 10% effectively earns a 50% return on their initial cash outlay. However, this same mechanism brutally amplifies losses during downturns. Financial professionals routinely warn against borrowing vast sums to purchase a single stock, yet that is precisely what a mortgage does to a homeowner’s equity, given that a house is an illiquid and undiversified asset.
The current market dynamic has shifted leverage back toward purchasers. High borrowing costs have paralyzed existing homeowners, many of whom are unwilling to surrender their historically low mortgage rates, creating a severe inventory shortage of existing homes. To attract the limited pool of qualified buyers, sellers are deploying unprecedented concessions.
According to Redfin, concessions appeared in nearly 45% of transactions last month, the highest August figure since 2020. These incentives range from mortgage rate buydowns and repair allowances to direct cash offerings of $10,000 to $20,000. The desperation has reached a point where some real estate agents are sweetening deals with non-traditional perks, including complimentary week-long vacations and all-expenses-paid cruises.
When these concessions are factored into the final transaction price, the effective cost of purchasing a home has dropped, offering pragmatic buyers a rare window of negotiating power. As the S&P 500 continues to outpace residential real estate, the separation of living arrangements from investment portfolios becomes not just a financial preference, but a mathematical imperative. The latest data suggests that while equities weather geopolitical storms with upward momentum, the housing market remains bogged down by structural affordability constraints, leaving buyers with the upper hand for the foreseeable future.