

Property Taxes and Insurance Costs Complicate Moves to Florida and Texas as Charlotte Gains Ground
No-income-tax states face scrutiny as buyers weigh the full monthly cost of owning a home.
Higher mortgage rates, property tax reassessments and rising homeowners insurance premiums are changing where Americans move and reducing home sales across major U.S. metropolitan areas. Florida and Texas still attract buyers with no state income tax, but financial advisors and real estate executives say other costs can erase the savings many expected.
Charlotte, North Carolina, is among the markets receiving relocated households and commercial investment. Ryan Serhant, founder and CEO of real estate firm SERHANT., said buyers are looking beyond the price of a home and the rate on a loan. “New York taught me that real estate is a function of price and rates. It is supply and it is demand,” he said in an interview at the firm’s SoHo headquarters in New York. “As we started expanding the company across the country in 2023, what we learned very, very quickly is that price and rates are only a small piece of what I would call, not even a housing market, but a housing obstacle course.”
Borrowing remains expensive. Mortgage Research Center data put the average 30-year fixed refinance rate at 7.11%, up from 7.07% the previous week, and the 15-year fixed refinance rate at 6.34%. The Federal Reserve raised its benchmark federal funds rate target range by 25 basis points to 3.75%–4.00%, its first increase after a series of meetings at which it held rates steady.
Home prices have nevertheless continued to rise. Redfin reported a 3.7% year-over-year increase in U.S. home prices in August, the fastest annual growth in 12 months. Resale supply remains constrained by the mortgage “lock-in” effect: owners with fixed rates below 4% are reluctant to list their homes.
The costs awaiting buyers vary sharply by location. Governments in states without a personal income tax rely heavily on property assessments and sales taxes to pay for infrastructure, public safety and school districts. Effective property tax rates in Texas frequently average 1.6% to 1.8% of assessed value. In Florida, a sale resets the property’s taxable value to its current market price, removing the statutory assessment caps that long-term owners receive under Save Our Homes.
“People move with two things, and it’s not just their two legs, which politicians like to say, ‘People vote with their feet.’ They move with their wallet, and they move with heart,” Serhant said. “If you think about a state like Florida, for example… And if you think about Texas, people think about no state income tax, but then they start to realize, ‘Oh, how are real estate property taxes determined?’ In Florida, it’s almost 2% of what you pay. That’s a lot.”
Insurance adds another expense. Catastrophic-weather exposure and reinsurer price adjustments have driven premium increases in coastal and wildland-urban interface areas. Multiple primary insurers have left Florida and California or tightened their underwriting rules, pushing some owners toward state-backed insurers of last resort, including Florida’s Citizens Property Insurance Corporation, or into expensive surplus-lines markets.
“And then you start thinking about sales taxes, what insurance costs — what is it like to get homeowners insurance in a coastal city these days? What does it actually cost you per month if you have to get private homeowners insurance?” Serhant said. “God forbid there’s a hurricane, let alone a tornado, let alone an earthquake, let alone a forest fire.”
In New York City, sellers and buyers also face state and city transfer taxes and a progressive “mansion tax” that starts at 1% on sales of $1 million or more and reaches 3.9% for properties valued at $25 million or higher. Proposed and enacted measures, including non-primary-residence surcharges on secondary homes known as pied-à-terre taxes, are intended to raise municipal revenue but risk slowing transactions, particularly in middle-tier residential brackets.
“The conversation where people are moving to is a full package conversation. The pied-à-terre tax hasn’t pushed people out of the city. What it’s done is, it’s frozen people who are in the middle, where that payment does really affect their monthly living costs, their monthly budget,” Serhant said. “If they had a place in New York City as a pied-à-terre, so they could have a nice one-bedroom or two-bedroom in a nice building close to their daughter who now lives in New York, and they want to go to Broadway a couple of times a year, so now, okay, well maybe [they] don’t do that trip anymore.” He said such taxes rarely deter wealthy buyers altogether.
For Serhant, local rules create a broader impediment to moving. “You realize that the game has somewhat been rigged by those who created the obstacle course in the first place, and punishes mobility in favor [of] stability,” he said. He also described a gap between the time horizons of governments and households: “Governments need to take a long-term view. Their constituents do not,” Serhant said. “If I am a dad and I have a kid, I’m thinking, yes, about how I’m gonna raise them over the next 20 years, let’s say, but I’m also really thinking about what I’m going to do with them on Saturday, and my commute to work tomorrow. Government needs to be thinking 10, 20 years down the line: How do I create the greatest place for people to grow up? How do we create the greatest place for us to create opportunities? And I think New York, I think Seattle, I think a lot of parts of California are taking a short-term view on state growth.”
Corporate expansion and domestic migration are increasingly shifting toward secondary mid-Atlantic and Southeastern hubs as major metropolitan areas contend with those costs. Charlotte’s metropolitan region is the second-largest U.S. banking center by assets. It is home to Bank of America’s headquarters and major operational hubs for Wells Fargo and Truist Financial.
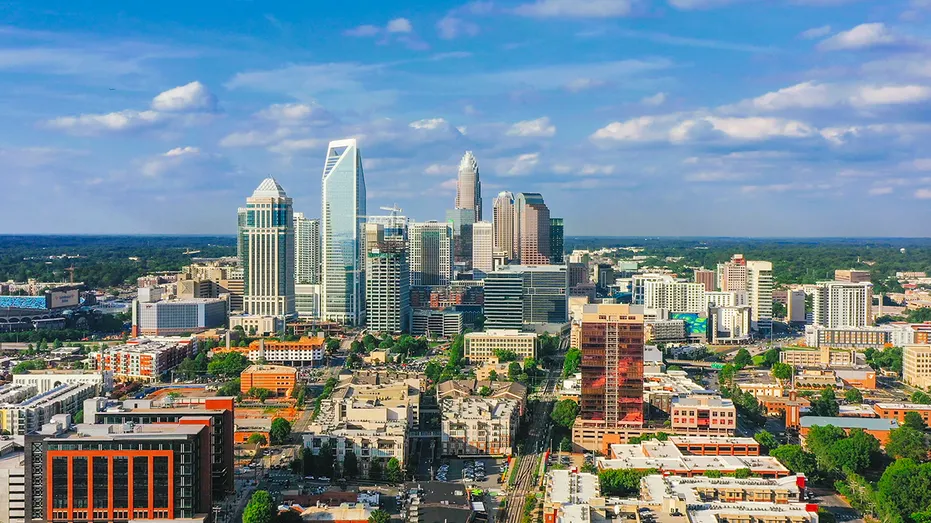
“I think the fastest-growing city of the last year, and one of the first markets that we expanded into three years ago, is Charlotte, North Carolina,” Serhant said. “The Carolinas, I feel, are oftentimes overlooked in the news because they don’t get the clicks. And a lot of the news is written by people who live on the East Coast or the West Coast in the major cities.”
Remote and hybrid work have loosened the connection between jobs and central business districts, allowing people with capital or wages to compare housing across the country by local costs and municipal amenities. “You buy based on the street corner, you buy based on that restaurant, that school, so on and so forth,” Serhant said. “And so investors and people who have the ability to move are now thinking about stretched markets. They don’t necessarily need to come to your city for a job. They don’t necessarily need to go to that state for grade schooling. They don’t necessarily need to go to that market and pay higher property or income taxes. They can be almost anywhere.”
Municipalities offering lower overall property tax friction, stable insurance markets and infrastructure investment are capturing a growing share of national residential liquidity. Serhant said other fundamentals remain central to sustained population movement: “They forget about what really drives the country, which is incredible job growth, great access to education and security,” he said. “Policy tends to affect everything else and get the headlines, but people move heavily for those three things.” North Carolina has enacted phased corporate income tax reductions targeting a 0% rate by 2030, while its local property tax assessments remain stable relative to Florida and Texas.


One Comment