Berkshire Hathaway Bets Big on U.S. Homebuilders Under Greg Abel
Under new CEO Greg Abel, the conglomerate acquired Taylor Morrison and nearly doubled its stake in Lennar amid soaring mortgage rates.
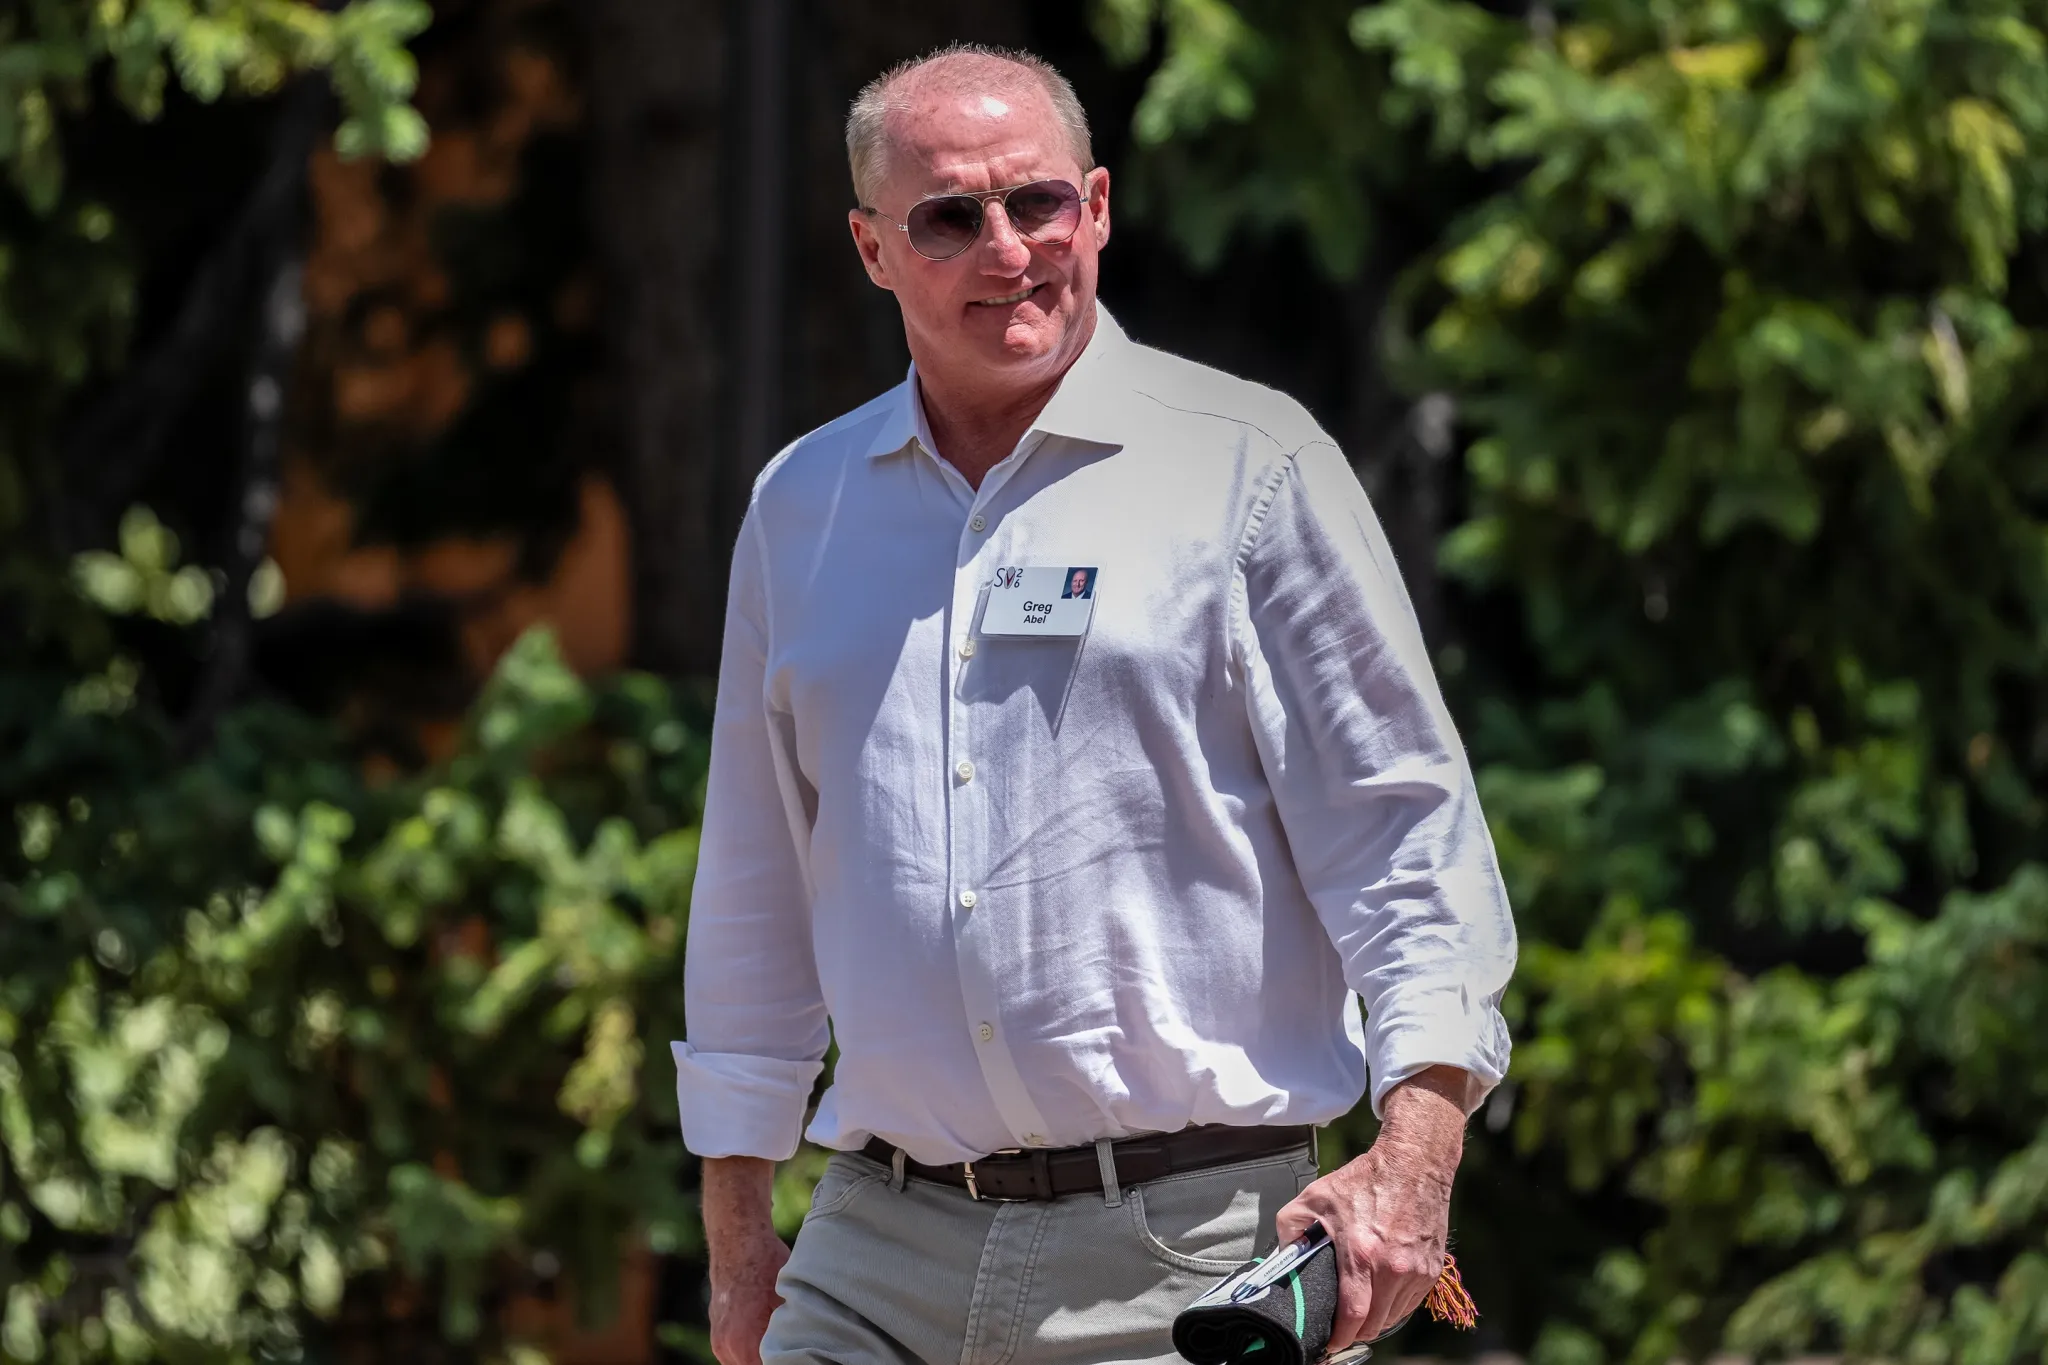
Greg Abel is reshaping Berkshire Hathaway’s housing empire just months into his tenure as CEO, executing a rapid consolidation strategy that has turned the conglomerate into one of America’s largest residential builders despite a punishing interest rate environment and eroding industry margins.
Since succeeding Warren Buffett on Jan. 1, Abel has directed three major capital deployments into homebuilding. The centerpiece was a $6.8 billion cash acquisition of Taylor Morrison, the nation’s sixth-largest builder, which closed in July after factoring in roughly $8.5 billion in total enterprise value including debt. Weeks later, Mungo Homes — an arm of Berkshire’s Clayton Properties Group — absorbed South Carolina-based McGuinn Homes. By the third quarter, Berkshire had nearly doubled its equity stake in Lennar, the country’s second-largest homebuilder, increasing holdings by 94% to own approximately 11% of the company, according to SEC filings and calculations by housing research firm ResiClub.
The aggressive accumulation marks a distinct strategic shift for Berkshire. While Buffett historically favored modular and manufactured housing through Clayton Homes — acquired in 2003 during a post-recession downturn — Abel is moving decisively into traditional site-built construction. Integrating Taylor Morrison with Clayton Properties instantly vaulted Berkshire to the fourth-largest site-built homebuilder in the United States, trailing only D.R. Horton, Lennar, and PulteGroup.

Buying heavily into residential construction right now requires absorbing severe near-term headwinds. The average 30-year fixed mortgage rate reached 7.28% by Oct. 1, according to Freddie Mac data, climbing above 7% in late September for the first time since January 2025. Elevated borrowing costs have frozen existing homeowners in place due to the lock-in effect, forcing buyers to rely almost entirely on new construction while simultaneously crushing their purchasing power.
Lennar illustrates the financial strain facing even top-tier operators. To maintain sales velocity, the Miami-based builder has cut net effective prices more aggressively than any major competitor this cycle. Its average sales price sits 24.2% below its 2022 peak. Incentives and direct price reductions account for roughly two-thirds of that decline, with the remainder driven by a deliberate pivot toward smaller, entry-level floor plans.
That pricing pressure has severely compressed profitability. Lennar reported a 15.8% gross margin for its fiscal third quarter ended Aug. 31 — its weakest third-quarter performance since 2009. Net earnings plummeted to $284 million from $591 million a year earlier. Shares ended the third quarter nearly 50% below their October 2024 high. Since the end of 2019, Lennar stock has gained just 44.2%, drastically underperforming the S&P 500’s 138.6% return and lagging behind D.R. Horton, PulteGroup, and Toll Brothers, which have each surged more than 150% over the same period.
Wall Street remains broadly skeptical. Consensus analyst ratings on Lennar currently sit at underweight, and several major quantitative funds reduced their exposure during the exact quarter Berkshire expanded its position. Lennar CEO Stuart Miller acknowledged on the company’s latest earnings call that conditions had deteriorated further since June.
Much of Lennar’s vulnerability stems from its heavy concentration in Sun Belt markets catering to first-time buyers. During the pandemic migration boom, states like Texas, Florida, Arizona, and Georgia drove unprecedented demand. That entry-level Sun Belt segment has since become one of the weakest pockets of the national market, burdened by oversupply in certain subdivisions and buyers who no longer qualify for financing at current rates.
Abel has signaled that Berkshire’s underwriting does not depend on a quick macroeconomic reversal. Speaking on CNBC’s Squawk Box on Sept. 2, he characterized the immediate outlook as a “bumpy road” but framed the acquisitions around a five- to 10-year horizon. “When we looked at housing and housing specifically in North America, we were taking a very long-term view, that American dream will continue to exist,” Abel said.
Berkshire’s ability to deploy billions into cyclical industries during periods of distress relies on its massive liquidity reserves, which exceeded $300 billion in cash and short-term investments heading into 2026. Unlike leveraged private equity firms or developers reliant on floating-rate credit facilities, Berkshire can absorb years of depressed margins without refinancing risk.
Clayton Homes already generates substantial revenue from originating and servicing mortgages for manufactured home buyers. Combining that financing infrastructure with Taylor Morrison’s site-built operations gives Berkshire vertical integration capabilities that few competitors possess, allowing it to offer proprietary lending products directly to buyers struggling to secure conventional mortgages.
The Federal Reserve held its benchmark interest rate steady at its September policy meeting, leaving the trajectory of mortgage rates tethered to broader inflation data and Treasury yields rather than imminent central bank relief. Builders entering the winter selling season face continued affordability constraints with no clear catalyst for a sudden rebound in buyer traffic.