Weil Gotshal Is Dissolving While Solvent to Escape Dewey’s Fate
The recommendation is not yet a decision, and the firm intends to wind down outside bankruptcy, collecting its bills as it goes.
The firm that steered Lehman Brothers through the largest bankruptcy in American history is planning its own ending without entering bankruptcy court. Harvey R. Miller and Shai Waisman of Weil, Gotshal & Manges were the names on Lehman’s 2008 filing, which listed $639 billion in assets and $613 billion in debt. On Wednesday, Weil’s management committee recommended to the partnership that the firm pursue an orderly wind-down. No partner vote has been held.
What is being recommended is not a bankruptcy filing but a solvent shutdown, and the difference is the whole design. Weil generated about $2.1 billion in revenue last year, remains debt-free with relatively few liabilities according to the Wall Street Journal, and is still collecting outstanding client bills, which is what would fund a wind-down conducted outside court. Restructuring advisory firm AlixPartners has been brought in to advise on the process. Davis Polk & Wardwell is advising on the restructuring, through restructuring partner Brian Resnick and managing partner Neil Barr, who have guided major law firm mergers. Associates and staff were told they will keep receiving pay for 90 days and receive bonuses at the end of 2026 if they stay through year-end. “Following a careful review of strategic alternatives, the Firm’s Management Committee has recommended to the partnership that the Firm pursue an orderly wind-down,” Weil said in a statement, adding that during the process over the coming months “the firm will continue serving clients with the dedication and excellence that have defined it since its founding.”
Average profit per equity partner at Weil was about $5.4 million, according to the American Lawyer figures cited by Reuters. At Kirkland & Ellis and Wachtell, Lipton, Rosen & Katz, the figure was more than $10 million. A Weil equity partner earns roughly half what a counterpart at those firms earns, and the lateral market prices that gap every week. Weil’s revenue had not vanished, which is what makes the arithmetic worth stating: a partnership has no way to hold its partners once the numbers turn against staying. Columbia Law School’s analysis of the Dewey collapse describes the mechanism: when a highly profitable partner leaves, the remaining profits per partner decline mechanically, which increases the incentive for the next partner to leave. “Law partners cannot be bound to the firm by noncompetes, and so the entire business abruptly folds, with no hope of reorganization, even if revenues had declined only modestly.” Yale professor John Morley’s research on law firm failures makes the same point from the other side, that departures change the incentives facing everyone who remains, and consultant Kent Zimmermann of the Zeughauser Group has noted that firms with greater profits can destabilize competitors even when the weaker firm is only perceived as weaker.
The departures that broke Weil map onto the firms that could pay the gap. Corporate chair Michael Aiello, who ran a department of roughly 600 lawyers and sat on the management committee, left for Cravath, Swaine & Moore with five mergers and acquisitions partners. Paul Weiss took private equity partner Christopher Machera, global private equity co-head Doug Warner, and securities-litigation partner Caroline Zalka, who sat on the management committee. Sullivan & Cromwell took London co-managing partner David Avery-Gee and corporate partner Sarah Flaherty, with former corporate co-managing partner Michael Hickey expected to follow. Davis Polk, the firm now advising Weil’s restructuring, took appellate litigator Drew Tulumello and Chantale Fiebig. Sidley took corporate co-managing partner Lyuba Goltser, and Simpson Thacher took a private funds group led by Murray Cox. By one count about 40 Weil partners left in 2026 before this week, and Bloomberg Law has reported at least seven management committee members leaving or lined up to leave since late 2024. The leadership question compounded the losses: private equity partner Ramona Nee, announced in March as the successor to Barry Wolf, who has led the firm for 16 years, told colleagues in September she would not take the job, and Semafor reported she has held talks with Simpson Thacher. Cravath’s private equity head Peter Feist did return to Weil in September as United States private equity co-head. The exits continued anyway.
Weil tried to buy its way out of the arithmetic with scale, and the attempt failed in public. Merger talks with Willkie Farr & Gallagher would have created a firm with more than $4 billion in revenue, nearly double Weil’s standalone $2.1 billion. The talks collapsed late last week, after the firm had denied in September that it was in any merger discussions at all. Other firms in Weil’s position chose the merger road and survived it: Shearman & Sterling combined with Allen & Overy in 2024 to form A&O Shearman, and Cadwalader, Wickersham & Taft merged this year with Hogan Lovells. Weil’s talks died on the same night the Wall Street Journal reported the October wave of exits, which left the firm with a management committee recommendation instead of a merger partner.
Dewey & LeBoeuf is the precedent Weil’s exit is designed not to repeat, and the numbers show why the distinction matters. Dewey was created by a 2007 merger into a firm of more than 1,300 lawyers in 26 offices. It filed for Chapter 11 in Manhattan on 28 May 2012, five years later. Its filing papers put about $315 million owed to more than 5,000 creditors against $13 million in cash and about $255 million in accounts receivable and ongoing work. JPMorgan Chase led a bank syndicate behind a $75 million revolving credit line. By the end of May 2012 about two-thirds of its roughly 320 partners had left, and regulators sued to take over pension plans they said were underfunded by $80 million. A firm that enters bankruptcy court hands its ending to a trustee and a judge. Dewey’s partners paid for that ending twice over: the estate first sought up to $103.6 million from former partners, and the approved liquidation plan eventually took $71.5 million from about 400 of them out of their 2011 and 2012 earnings, with a maximum contribution of $3.5 million per partner.
The doctrine that made Dewey’s ending so expensive for its departed partners has since lost much of its force, which is part of why Weil’s chosen route is available at all. Under the unfinished-business doctrine, profits on work begun at a dissolved firm were treated as property of the old firm’s estate, so a new firm that hired a fleeing partner could face demands years later for fees on work it had itself performed. In June 2014, Judge Charles R. Breyer ruled that the trustee of the defunct Heller Ehrman firm was not entitled to profits on unfinished work its former partners took elsewhere, writing, “A law firm never owns its client matter.” Courts in New York reached similar results in Dewey-related cases. Weil’s out-of-court wind-down avoids a trustee altogether. No estate will be assembled to sue its departing partners or their new firms. One tension remains on the record: John Bringardner of the financial analytics firm Debtwire told City AM the firm “may file for Chapter 7 bankruptcy in an attempt to reject its office leases,” which would put a court back into the ending for the narrow purpose of shedding rent.
Several pieces of Weil’s ending are still unannounced, and they are the pieces clients and staff are waiting on. No partner vote has been held, so the wind-down remains a recommendation rather than a completed act, and the firm’s Hong Kong practice has no public disposition. In London, where the firm counts about 45 partners and 200 lawyers, associates were told they would receive a 90-day payout with operations winding up on 31 December, according to the trade outlet Non-Billable, a date Weil itself has not confirmed. In the United States, capital markets head Alex Lynch advised junior associates to look for new jobs while continuing their active client work. Former Weil associate Gabriel Shapiro, now chief executive of MetaLeX Labs, put the mood of the firm’s alumni on X in one sentence: “My old law firm is falling apart.”
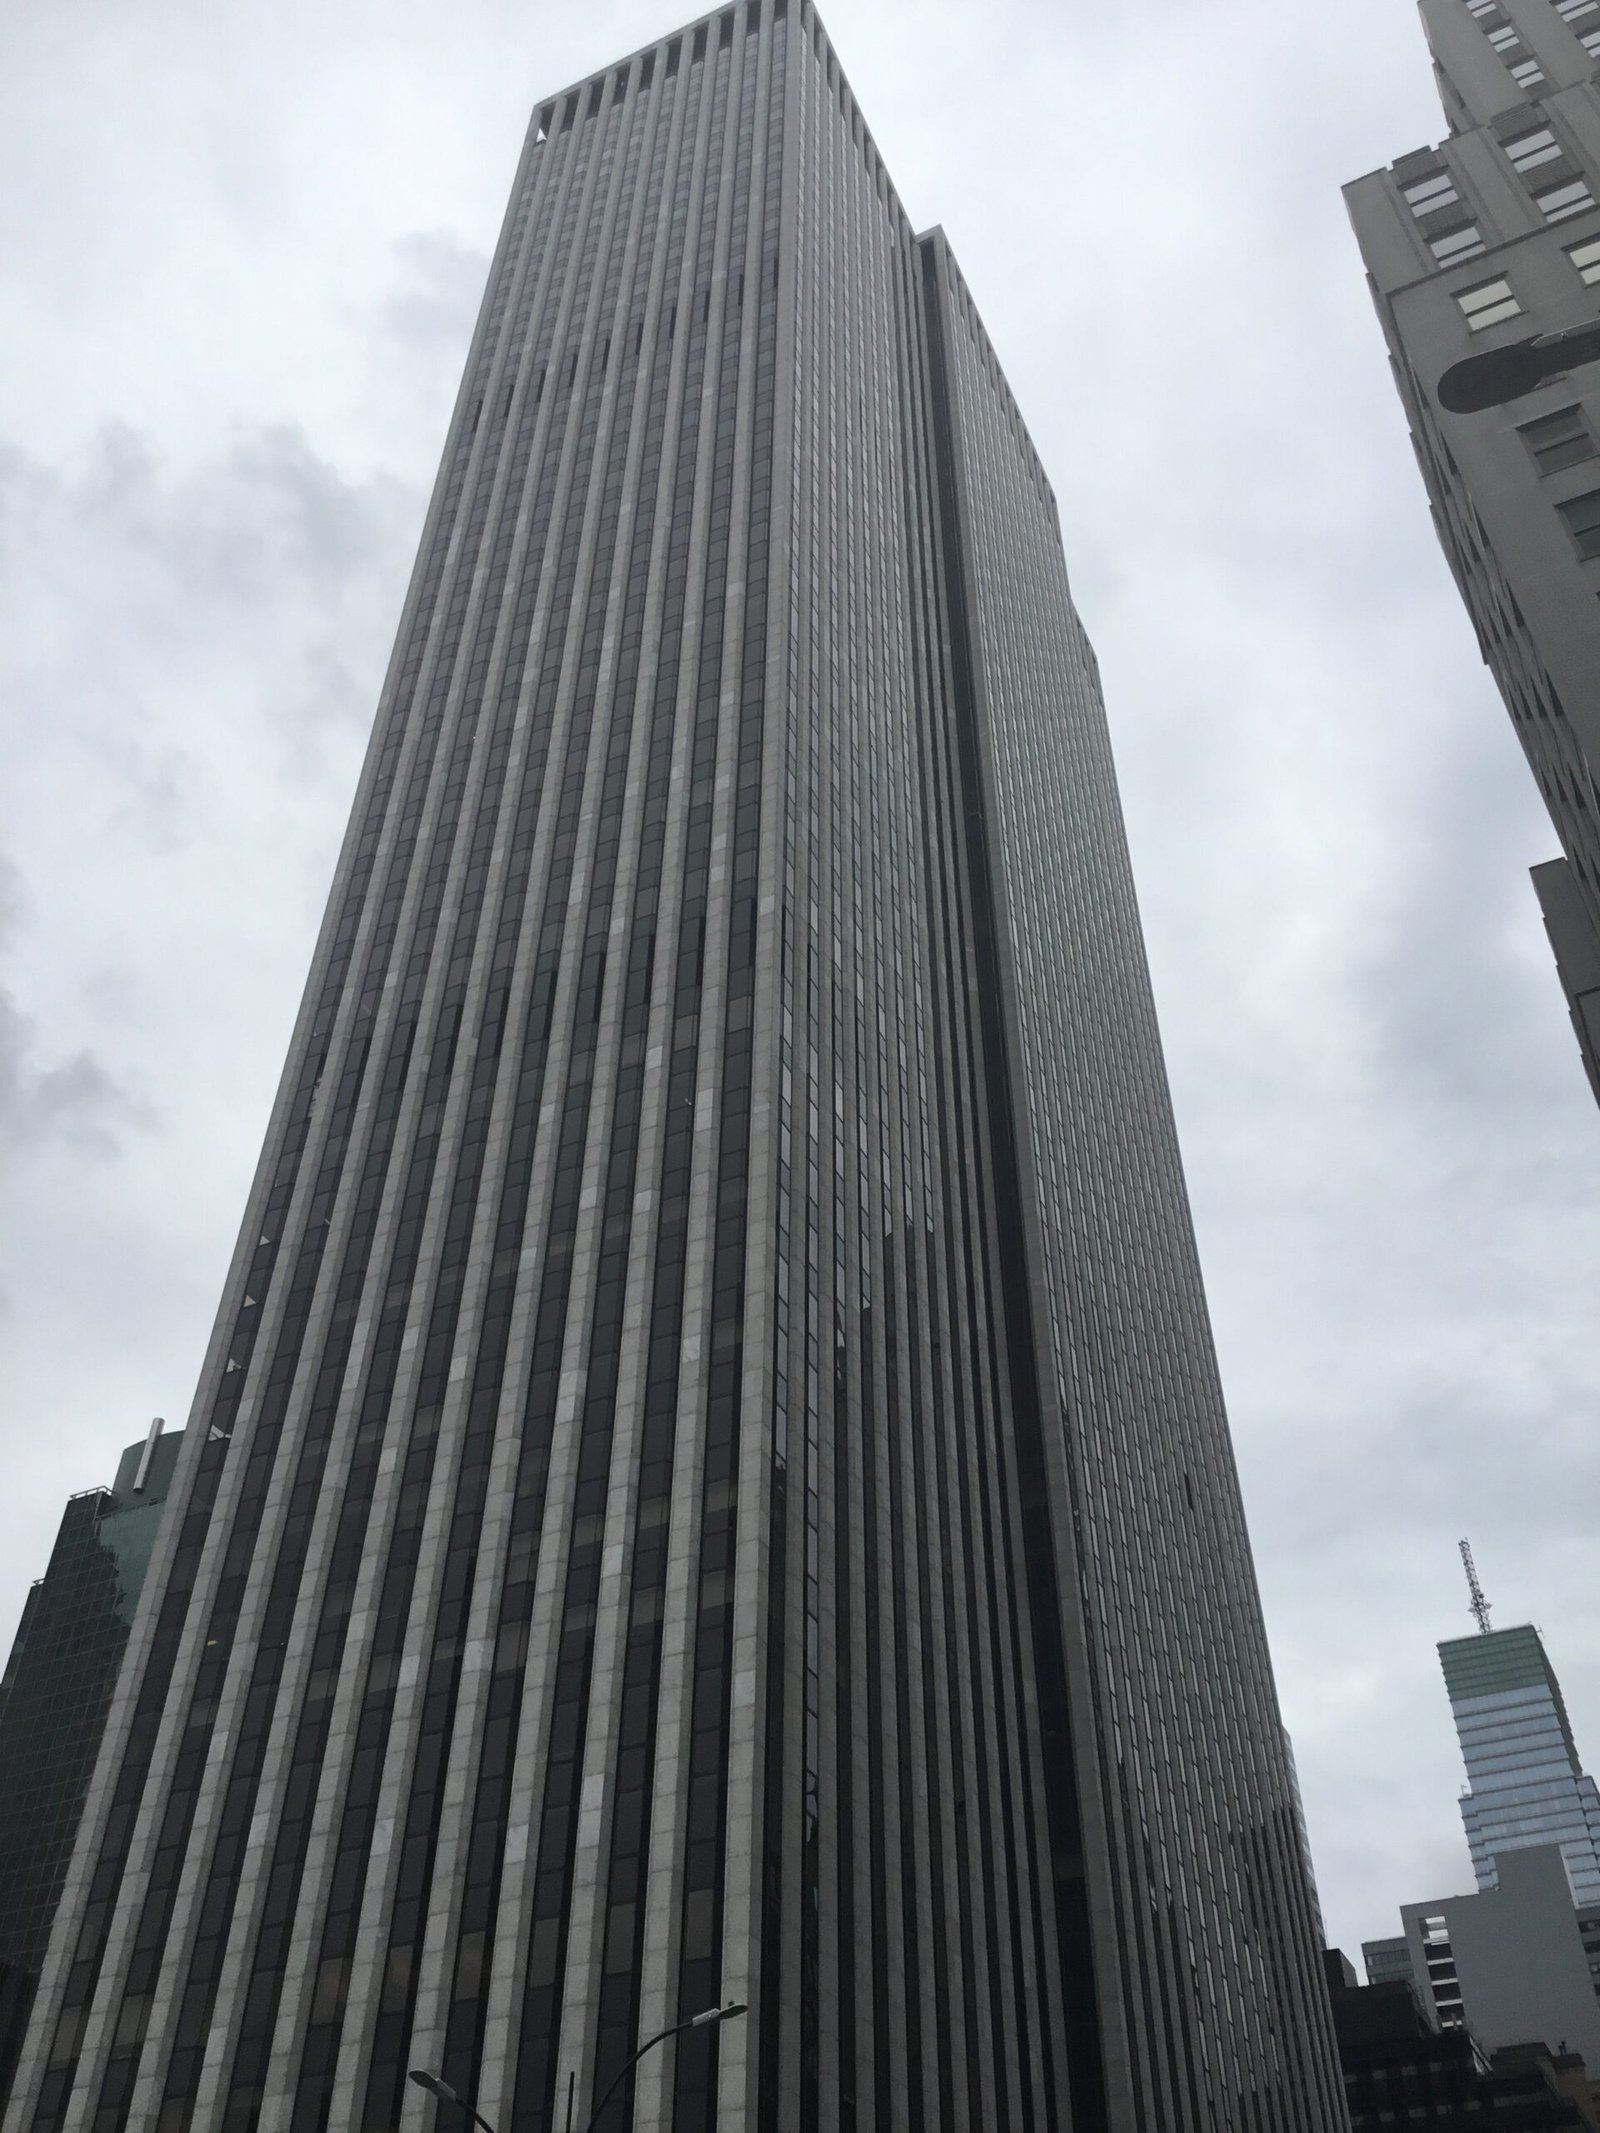
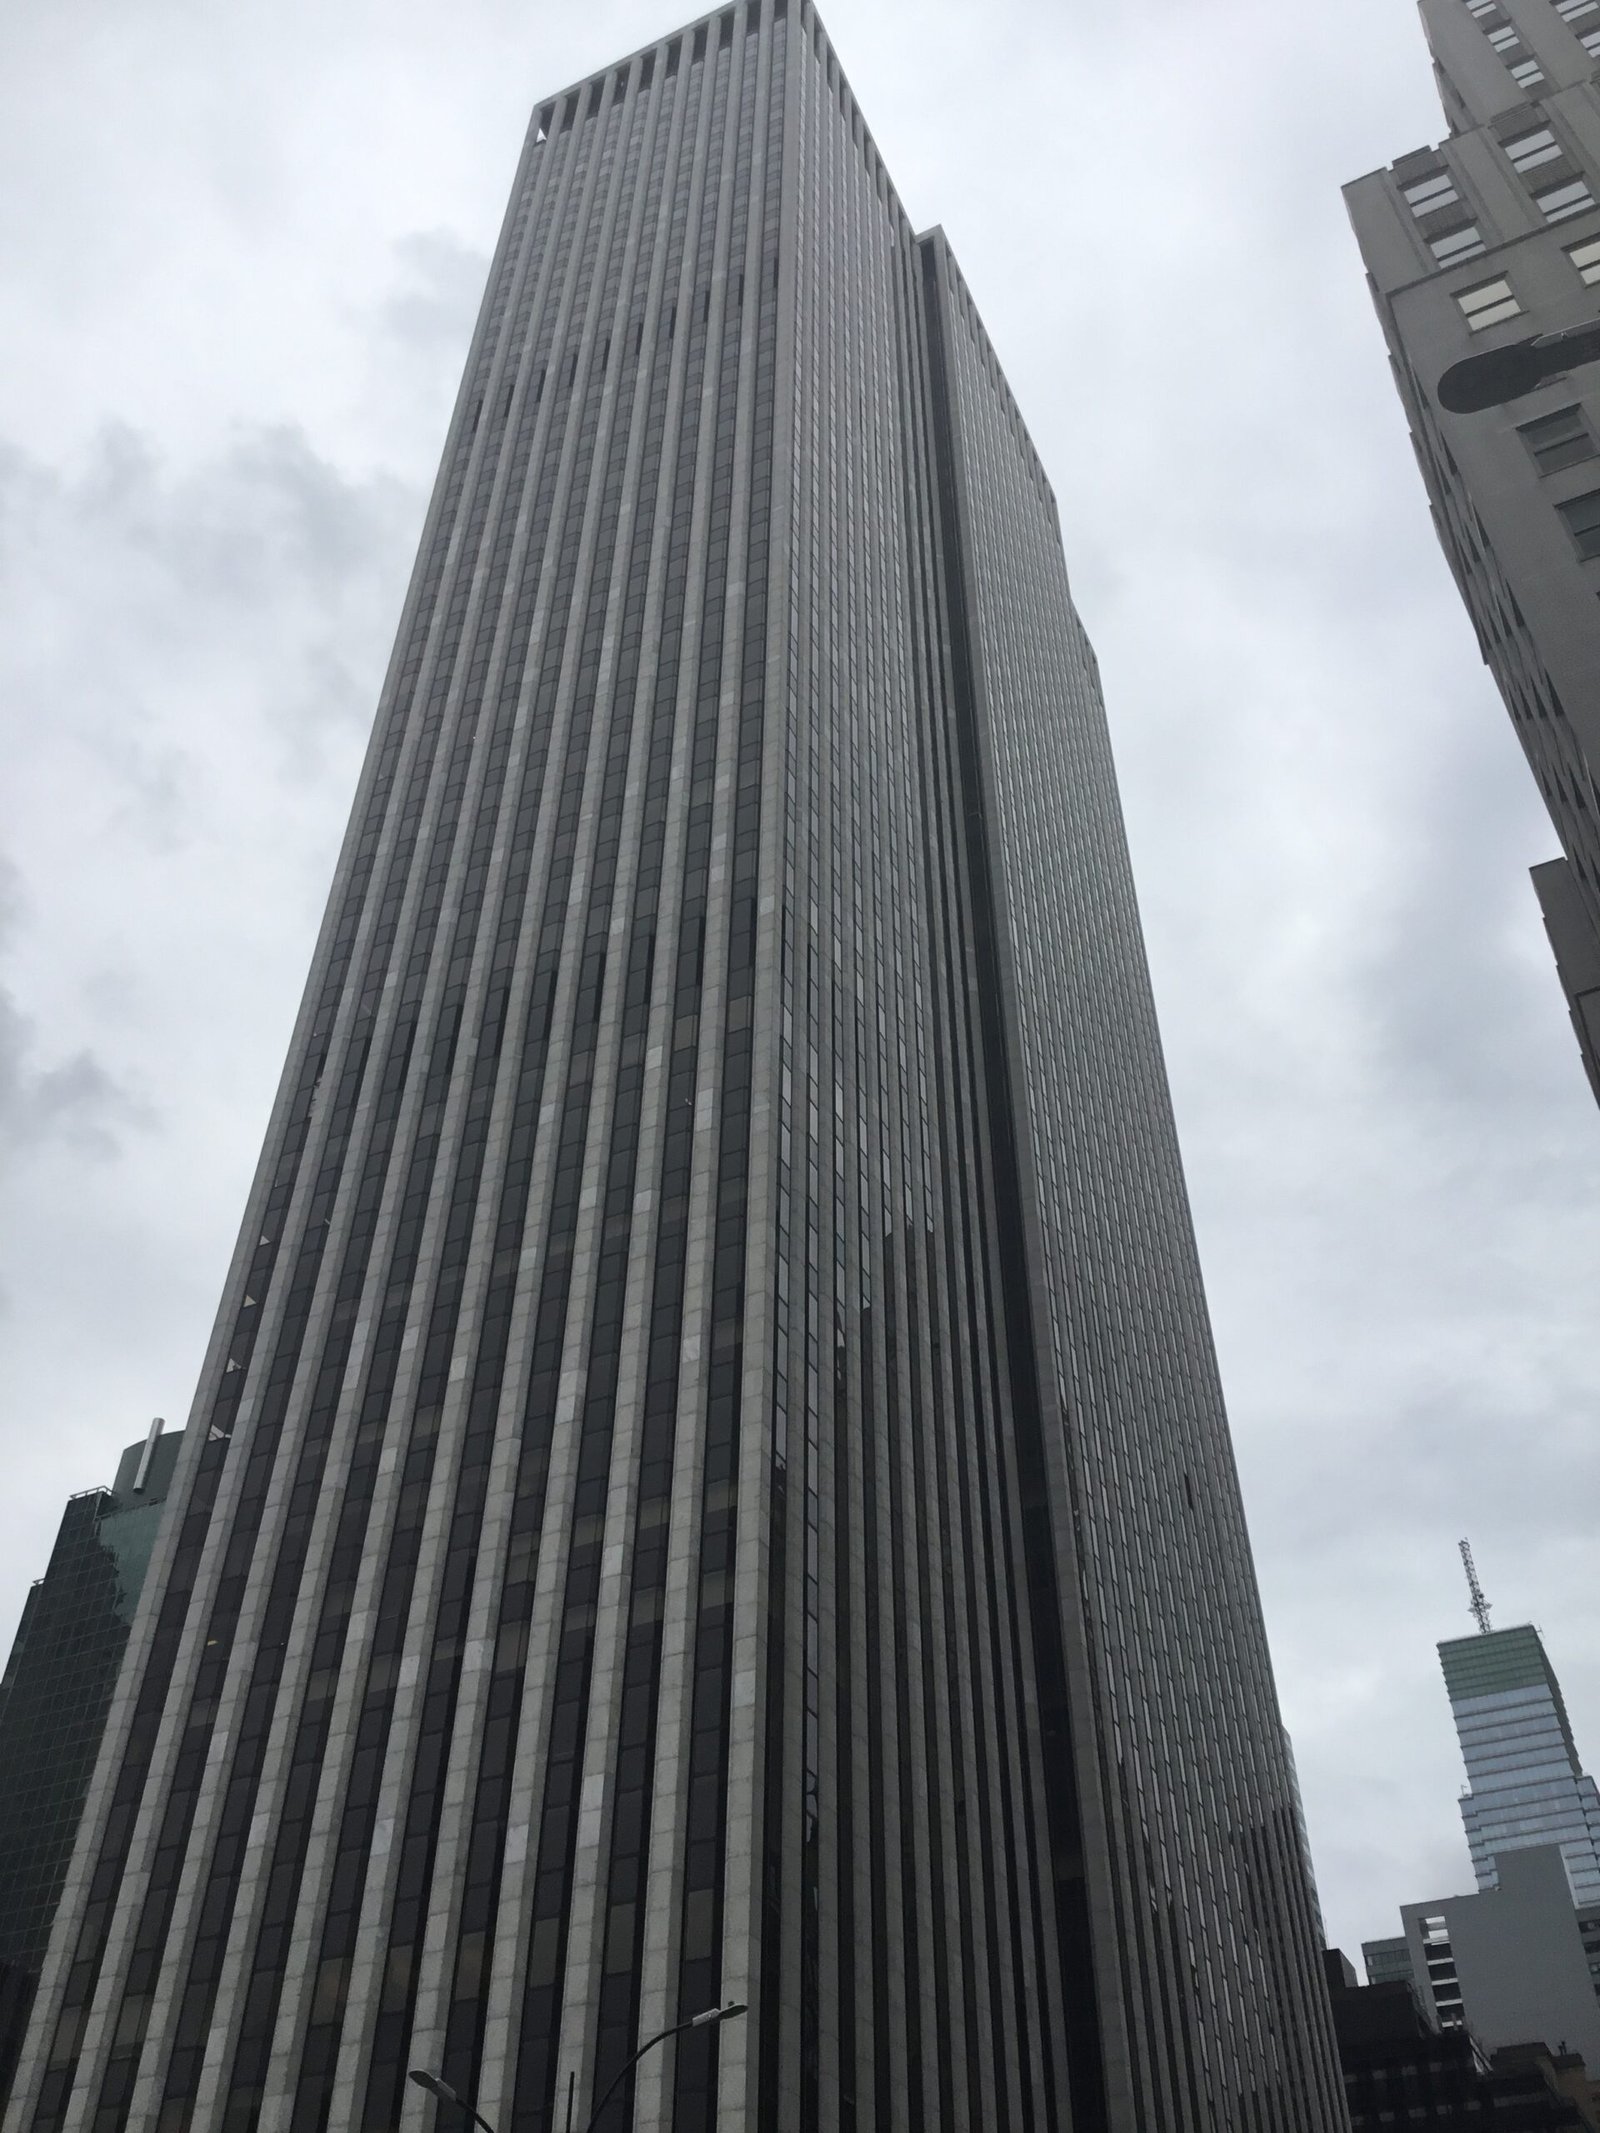
Weil leases about 380,000 square feet at the General Motors Building at 767 Fifth Avenue, a lease the Journal calls among the firm’s biggest liabilities, and real-estate experts told the Journal the space should be easy to lease again, possibly at a higher rent than Weil pays. Pension obligations are also under review by the firm’s advisers. Outstanding client bills are still being collected.