Social Security 2032 Insolvency: Who Pays to Fix It?
Policy experts converge on high earners absorbing the cost of the 2032 trust fund shortfall, but clash over whether to cut benefits or lift the payroll tax cap.
The wealthiest Americans are poised to absorb the financial shock of Social Security’s looming insolvency, regardless of whether Congress chooses to slash benefits or raise taxes. That rare point of agreement emerged from a policy debate that otherwise exposed an unbridgeable divide over the program’s fundamental purpose.
Romina Boccia, director of budget and entitlement policy at the Cato Institute, and Teresa Ghilarducci, a labor economist at the New School for Social Research, clashed during an NPR Open To Debate forum over whether the federal retirement system should be phased out. Yet when pressed on who would bear the cost of stabilizing the program, both economists pointed directly to high earners.
The convergence is driven by math rather than ideology. The Social Security trust fund faces depletion by 2032 under current law, according to projections from the program’s trustees. Once reserves are exhausted, the system will only be able to pay roughly 75% to 80% of scheduled benefits using incoming payroll tax revenue. Because lower-income retirees rely almost entirely on those checks for survival, policymakers across the political spectrum recognize that any structural fix must extract resources from those with the greatest capacity to absorb either higher levies or reduced payouts.
Boccia envisions extracting that value through benefit reductions for affluent retirees. She argues the current system functions as a bloated wage-replacement engine that directs its largest checks to individuals best positioned to fund their own retirements. Workers and employers currently split a 12.4% payroll tax, but those funds do not accumulate in personal accounts. Instead, they immediately finance payments to current beneficiaries, a structure Boccia contends drains capital from younger workers trying to buy homes, raise families, or build independent wealth.
Her proposed alternative would replace the earnings-related formula with a flat, universal anti-poverty benefit. Middle- and upper-income workers would retain more of their paychecks to invest privately, while the government guarantees a baseline income floor for the elderly.
Ghilarducci rejects that framework, arguing it misidentifies the program’s core function. Social Security operates less as a traditional pension and more as comprehensive family insurance, distributing funds to disabled workers, survivors, and dependent children alongside retirees. Crucially, those payments are indexed to inflation and guaranteed for life—features the private sector has consistently failed to replicate at scale.
Kent Smetters, faculty director of the Penn Wharton Budget Model, underscored the technical difficulty of replacing that guarantee. Private markets struggle to offer true inflation-adjusted annuities. Most commercial products provide nominal payouts or fixed annual increases that frequently lag actual price growth. At a sustained 2% inflation rate, Smetters noted, purchasing power erodes by roughly 40% over a 25-year retirement. Stripping Social Security down to a poverty-prevention tool, Ghilarducci warned, would sever the middle class from the only reliable inflation hedge available to them.
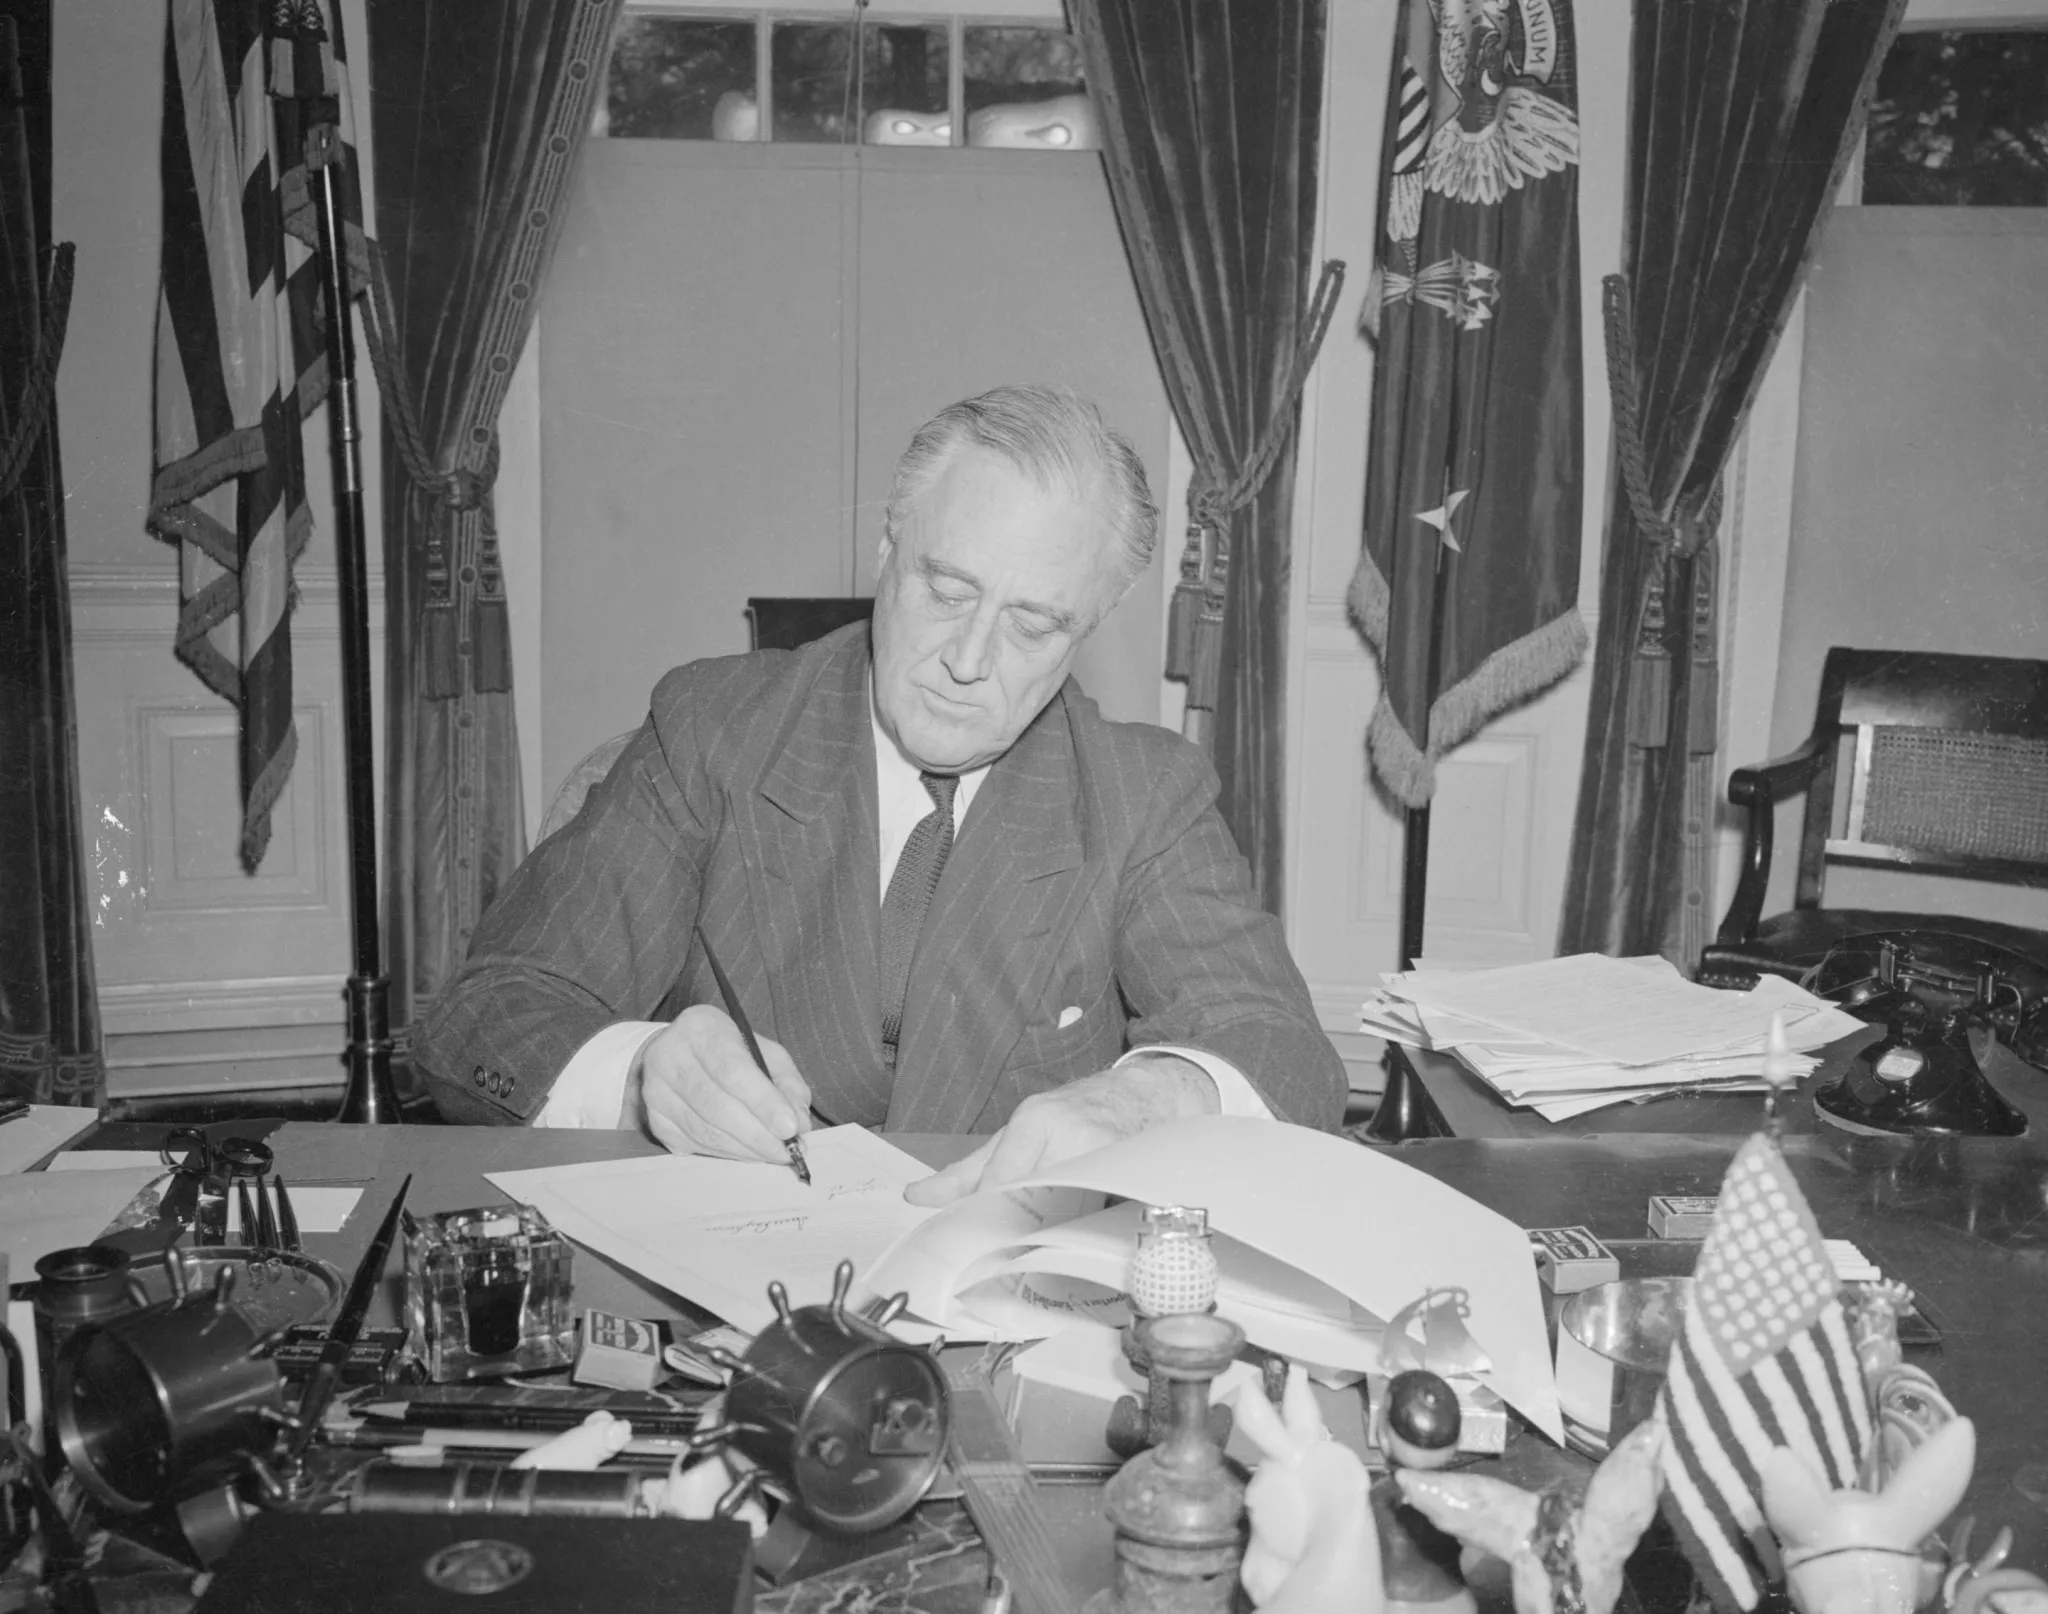
This ideological collision is not new. It mirrors a foundational tension embedded in the program since Franklin D. Roosevelt signed the Social Security Act in 1935. The architects of the New Deal needed to redistribute wealth without triggering constitutional challenges or political backlash against outright welfare. Their solution was a hybrid: a progressive benefit formula that replaced a higher percentage of pre-retirement wages for low earners, funded by a flat payroll tax that mimicked a private insurance premium. The design gave the program the political durability of an earned right while functioning economically as a redistributive safety net.
That duality sparked a famous 1972 clash between Nobel laureate Milton Friedman and Wilbur Cohen, former secretary of Health, Education, and Welfare. Friedman advocated shrinking the program into a targeted poverty-relief mechanism funded by progressive general revenues. Cohen defended the broader, contributory model, warning that programs exclusively targeting the poor inevitably become impoverished themselves. Boccia’s modern proposal essentially revives Friedman’s logic, while Ghilarducci channels Cohen’s defense of universalism.
Transitioning away from the current model carries severe macroeconomic friction. Smetters acknowledged that shifting toward private savings could eventually expand the broader economy by increasing domestic capital formation. However, he cautioned that the transition period demands double payment: funding current retirees while simultaneously building new private accounts for younger workers. “Somebody has to pay,” Smetters said. “There’s no free lunch.” Future generations might inherit higher wages and a larger capital base, but those alive during the multi-decade shift would shoulder the immediate burden.
Public opinion already leans heavily toward one side of that ledger. An AARP and National Academy of Social Insurance survey found that 85% of respondents—including 75% of Republicans—support maintaining or increasing benefits even if it requires higher taxes. Furthermore, 73% of those surveyed, including 60% of Republicans, specifically endorsed applying payroll taxes to income above $400,000. Currently, the Social Security wage base caps taxable earnings at $176,100 for 2025, meaning income above that threshold escapes the 12.4% levy entirely.
Bipartisan legislative momentum reflects those polling numbers. Ohio Republican Senator Bernie Moreno recently joined Democratic Senator Elizabeth Warren to advocate lifting the payroll tax cap, while House Appropriations Committee Chair Tom Cole, an Oklahoma Republican, signaled openness to revenue increases to secure the program’s solvency.
Ghilarducci tied the urgency of that revenue discussion directly to recent fiscal policy, pointing to 2025 tax legislation that reduced liabilities for top earners. “Congress made a choice in 2025 when they chose tax cuts for the very wealthiest part of America,” she argued, suggesting those legislative decisions could simply be reversed to fund the trust fund shortfall. Boccia countered that reducing future obligations, rather than raising taxes, remains the only path to economic growth robust enough to benefit all demographics.
The 2025 Old-Age and Survivors Insurance (OASI) Trustees Report confirmed that without legislative intervention, automatic benefit cuts will trigger upon trust fund exhaustion in the early 2030s, cementing the timeline for congressional action.