How Private Jet Tax Breaks and Infrastructure Grants Shift Costs to Commercial Airline Passengers
Restored 100% bonus depreciation and $1.3 billion in airport grants accelerate a widening gap between what commercial passengers and private flyers pay to use U.S. airspace.
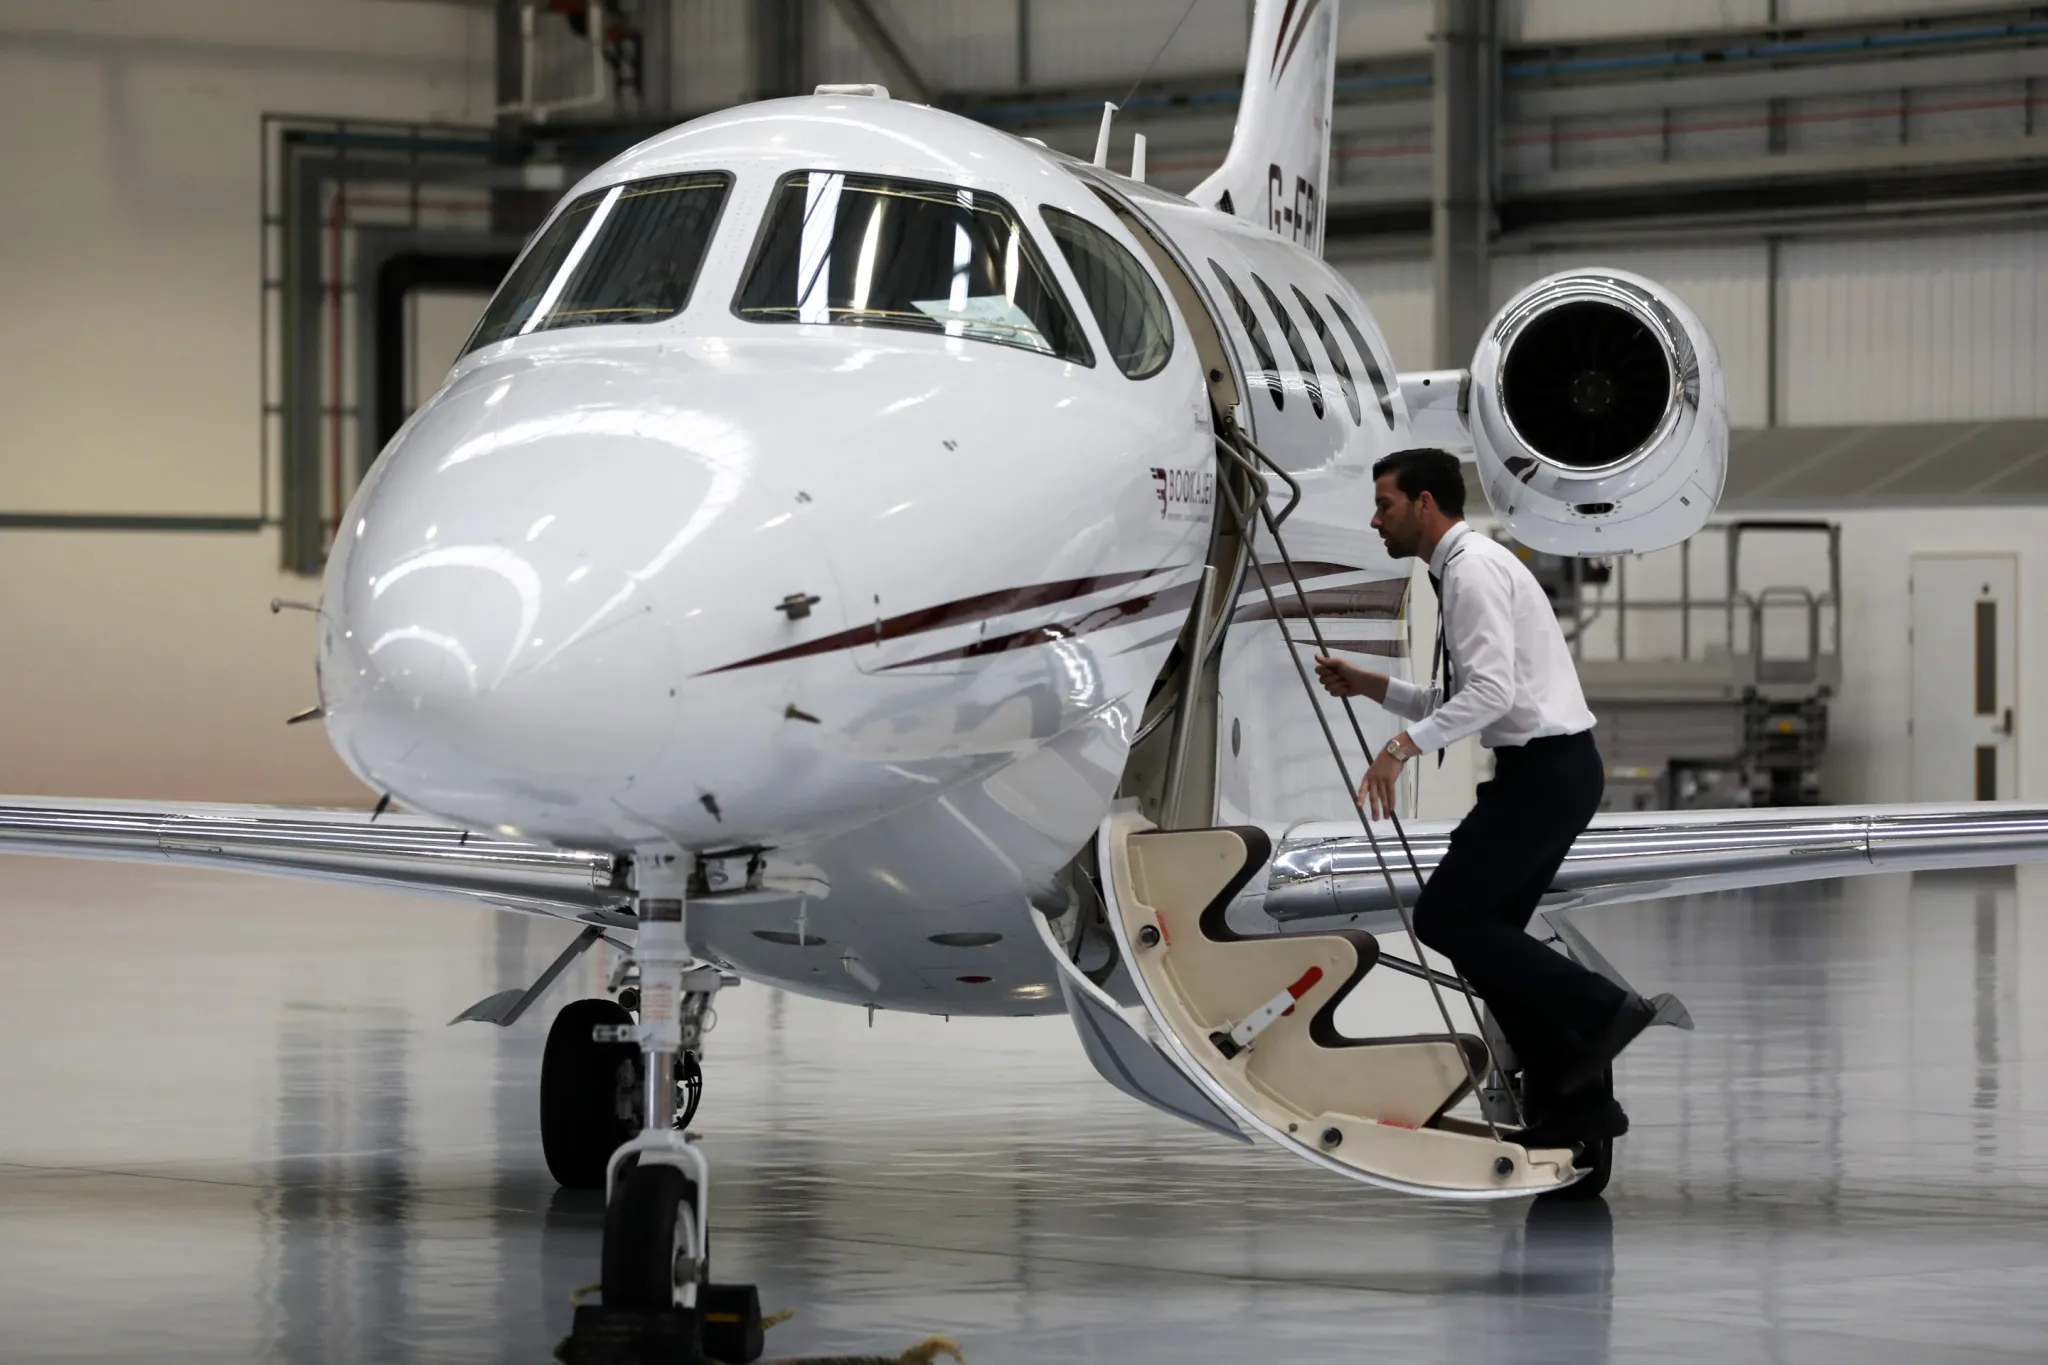
Commercial airline passengers are effectively subsidizing the private aviation industry through a tax structure that levies heavy fees on economy tickets while granting sweeping deductions, sales tax exemptions, and infrastructure funding to owners of multimillion-dollar aircraft.
Every time a traveler purchases a commercial airline ticket in the United States, 7.5% of the base fare is immediately routed to the federal government to fund the national airspace system. Additional passenger facility charges and security fees push the total tax burden on a standard ticket even higher. Private jet operators bypass this ticket-tax mechanism entirely. Instead, they pay fuel taxes and landing fees—a funding model that leaves a massive gap between the cost of operating the Federal Aviation Administration and the revenue generated by its heaviest users.
Noncommercial private jets account for roughly 7% of all flights managed by the FAA, according to Department of Transportation data. Yet these same flights contribute just 0.6% of the taxes flowing into the trust fund that finances the agency. The Institute for Policy Studies quantified this disparity in a September report, framing the structural imbalance as a direct subsidy benefiting an estimated 256,000 individuals globally who hold a combined $31 trillion in wealth.
The financial mechanics driving private jet acquisitions have accelerated sharply following recent changes to the federal tax code. President Donald Trump’s One Big Beautiful Bill Act restored 100% bonus depreciation for qualifying business assets, including private aircraft. This provision allows eligible buyers to deduct the entire purchase price of a jet in the year it enters service, rather than amortizing the cost over several years.
For ultra-high-net-worth buyers, the math transforms an aircraft from a transportation expense into a tax-shielding asset. A buyer acquiring a $40 million jet at the top marginal federal income tax rate of 37% could reduce their tax liability by up to $14.8 million in the first year alone, depending on their specific taxable income and business-use calculations. Global private jet sales reached $40.3 billion in 2025, climbing nearly 24% over five years despite elevated oil prices and broader inflationary pressures.
Industry executives say the tax incentives have fundamentally altered purchasing behavior. Justin Crabbe, CEO of the private jet marketplace Jettly, noted that corporations frequently acquire $75 million aircraft primarily to eliminate tax obligations rather than to fulfill immediate travel needs. To maintain the legal requirement that the asset be used for business purposes, buyers often place the aircraft into charter service to generate revenue, even when personal or corporate flight demand does not justify the purchase.
Beyond federal depreciation rules, state-level tax policies compound the advantage. Eight states, including Alaska, Oregon, New Hampshire, New York, and Massachusetts, offer full or near-total sales tax exemptions on private aircraft. In Massachusetts, where residents pay a 6.25% sales tax on everyday items like bicycles and automobiles, the aircraft exemption is projected to cost the state $25.3 million in foregone revenue this fiscal year, according to the Massachusetts Budget and Policy Center. State Sen. Michael J. Barrett introduced legislation to repeal the exemption last year, but the measure remains under review by the Legislature’s revenue committee.
Preserving these tax advantages requires sustained political capital. The National Business Aviation Association, which represents 10,000 member companies and professionals, spent a combined $3.4 million on federal lobbying across 2024 and 2025. Trade groups argue that the tax breaks sustain manufacturing jobs and support the broader general aviation ecosystem.
The NBAA has also aggressively contested state-level taxation efforts. When Washington state passed a 10% luxury tax on aircraft valued over $500,000 in May 2025, the association urged operators to mobilize against it. A repeal bill was signed into law before the tax ever took effect. During a similar 2021 dispute in Massachusetts, the group warned lawmakers that applying the state’s 6.25% sales tax to aircraft would drive general aviation operations to neighboring jurisdictions.
Federal lawmakers are currently debating provisions that could further insulate private aviation from local tax enforcement. The House version of the pending ALERT Act, an air-safety bill racing toward passage before the midterm elections, contains language blocking state and local officials from using aircraft-tracking data to identify and tax private jets. The Senate version of the bill strips out this specific tracking prohibition.
The subsidy extends beyond tax policy into physical infrastructure. Through August, the federal government awarded nearly $7.6 billion in Airport Infrastructure Grants. Approximately $1.3 billion of that total flowed to smaller airports with little or no scheduled commercial passenger service—facilities that predominantly cater to general aviation and private charters. More than $1.1 billion funded projects with a strong likelihood of directly benefiting private jets, including runway extensions and hangar construction.
Air traffic control resources face similar allocation pressures. Controllers must manage separation and sequencing for a single-passenger private jet exactly as they do for a commercial airliner carrying 400 people. Crabbe estimates that roughly half of all private flights involve an empty aircraft repositioning for its next pickup, known in the industry as a deadhead leg, meaning taxpayers finance air traffic management for planes generating no passenger revenue.
The FAA continues to process grant disbursements for the current fiscal cycle as Congress negotiates the final text of the ALERT Act ahead of the November midterms.