Nvidia Lines Up $500B to Turn AI Compute Into an Asset Class
Wall Street giants will channel pension and sovereign wealth into GPU-backed debt to break the hyperscaler monopoly on compute.
Nvidia has enlisted Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to build financing platforms capable of mobilizing more than $500 billion for artificial intelligence infrastructure, according to the company. The August arrangement attempts to reclassify short-lived computing hardware as long-term infrastructure debt, a financial engineering maneuver designed to let smaller competitors purchase the same chips that hyperscalers are hoarding.
The core question driving the deal is not who builds the best model. It is who can borrow cheaply enough to buy the GPUs required to run them.
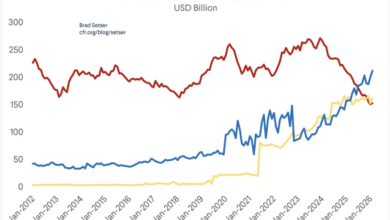
The five largest American hyperscalers are on track to spend $730 billion on capital expenditure in 2026. A shrinking proportion is coming from their own balance sheets; they are expected to finance up to a third of it with debt. When the most profitable companies in history have to borrow to stay in the race, startups and mid-tier firms face a structural wall.
Project finance has historically funded power plants, toll roads and airports — assets built to last decades against foreseeable demand. Graphics processing units depreciate rapidly. AI compute demand fluctuates unpredictably. Returns remain unproven. Yet Nvidia’s partners are pitching pension funds, insurers, sovereign wealth funds and household savings on the premise that server racks can function like bridges.
Critics flagged circular financing risks, where a chipmaker’s money returns as chip orders. That does not apply here. Nvidia and its six partners are not lending their own money. The capital comes from third parties. Rather than artificially boosting demand, the structure lowers the cost of supply for a wider bench of competitors beyond the hyperscalers.
This financial architecture exposes a widening gap between the United States and its rivals. Eurozone households hold about 10 trillion euros (about $11 trillion) in bank deposits, yet European institutional investors routinely buy U.S. tech bonds instead of backing domestic startups. Progress on long-stalled capital-markets integration would do more for European competitiveness than another round of gigafactories.
China faces a different bottleneck. State-directed spending poured concrete efficiently but struggled to match capacity to demand. Chinese media reported last year that as much as 80% of newly built computing capacity sat unused following a policy-driven building spree. The Stanford HAI AI Index 2026 estimates that private investment in AI in the U.S. last year was more than 23 times that in China.
America’s bond markets, private credit funds and asset managers are already hunting for exactly this kind of yield. No other country converts the savings of pensioners into risky, long-lived assets at this scale.
For half a century, software was asset-light. Code could be written once and distributed to billions at negligible marginal cost. AI reversed that dynamic. The latest systems require factories, advanced chips, substations and enormous supplies of electricity, turning technology into heavy industry.
The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.
This story was originally featured on Fortune.com