Giving While Living: Why Families Are Shifting Wealth Transfers Before Death
How AI and human advisors help families navigate emotional wealth transfers before death
Families across the United States are increasingly abandoning the traditional model of posthumous inheritance in favor of distributing assets while the older generation is still alive. This strategy, known as “giving while living,” allows parents and grandparents to witness the impact of their wealth, test family values alignment, and provide financial assistance when younger relatives face acute economic pressures such as housing affordability or student debt.
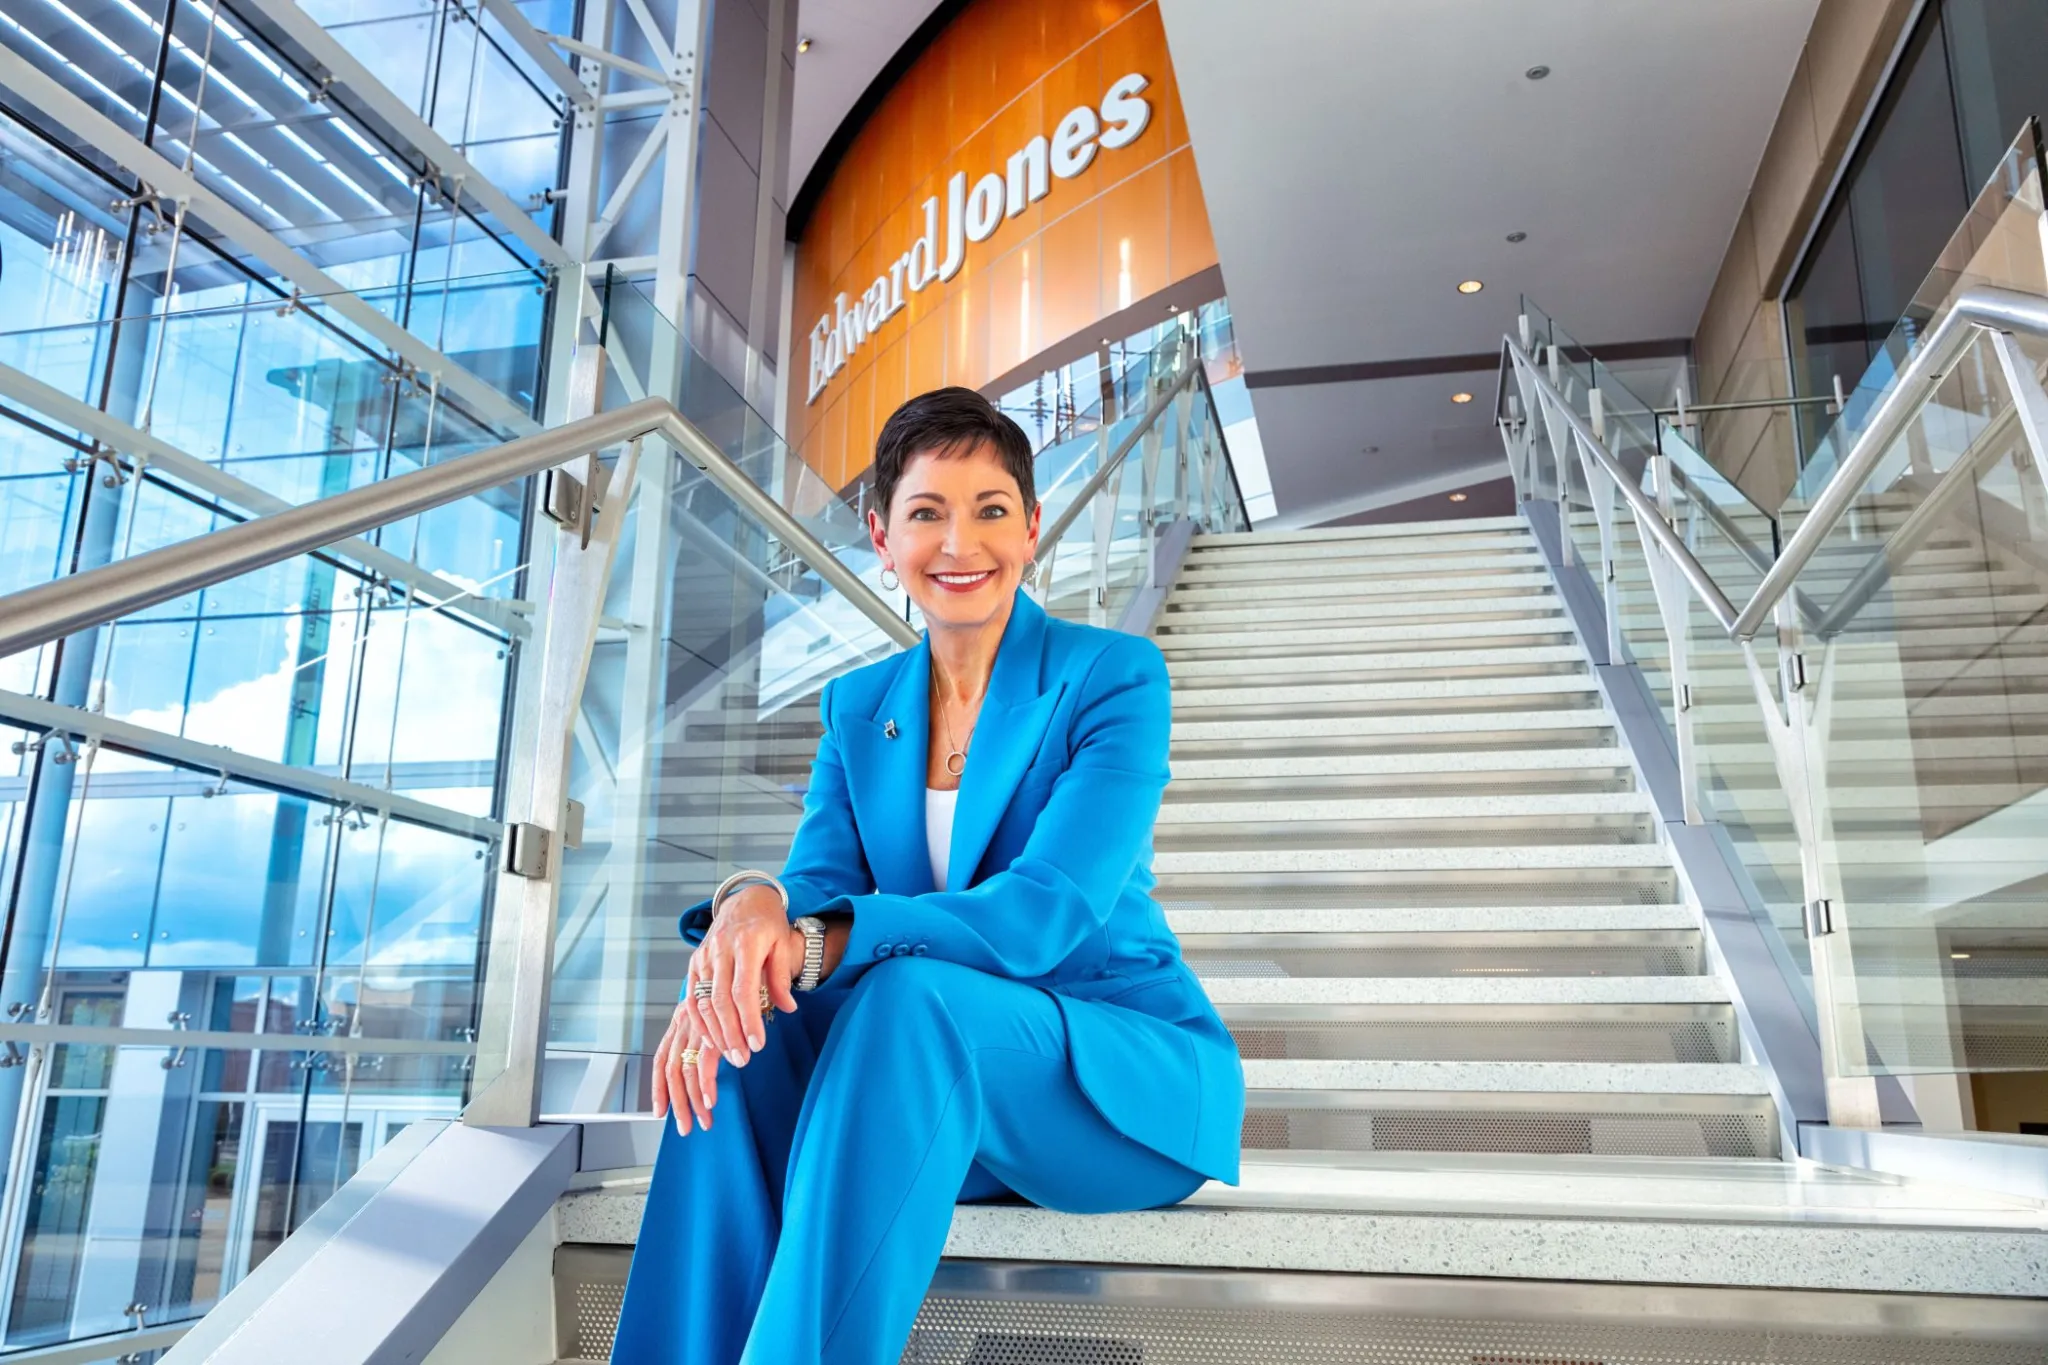
Penny Pennington, CEO of Edward Jones, reports that a significant portion of the firm’s 9 million clients are now establishing gifting arrangements and trusts designed for lifetime distribution rather than estate settlement. The shift represents a fundamental change in how American families view intergenerational wealth transfer, moving from a static bequest model to an active, monitored process that prioritizes emotional connection and practical utility over tax efficiency alone.
The primary driver for many families is risk mitigation regarding beneficiary behavior. In cases where one child demonstrates financial responsibility while another struggles with spending habits, equal post-death inheritances can be counterproductive. Lifetime gifting allows benefactors to provide smaller, controlled amounts to financially vulnerable heirs, observe how the funds are managed, and adjust future distributions accordingly. This approach transforms inheritance from a potential windfall into a teaching mechanism, reducing the likelihood that assets will be squandered immediately upon receipt.
Beyond behavioral testing, current economic conditions have made earlier transfers a necessity for many middle-class families. With median U.S. home prices remaining elevated relative to wage growth, down payment assistance has become a common form of living gift. Similarly, families are using these transfers to subsidize children who have chosen lower-paying but socially valuable careers in education, healthcare, or public service. Unlike traditional inheritances that arrive decades after career choices are made, living gifts enable younger generations to pursue meaningful work without facing immediate insolvency.
Despite the clear advantages, execution remains difficult due to persistent communication barriers. Research commissioned by Edward Jones indicates that more than one-third of Americans do not plan to discuss wealth transfer with their families at all. Even among those who intend to pass on assets, confidence in structuring these arrangements remains low. Money conversations frequently trigger anxiety rooted in generational trauma; individuals who experienced scarcity during formative years often struggle to articulate financial intentions, creating silence that complicates even well-intentioned gifting plans.
Financial advisory firms are responding to this communication gap by integrating artificial intelligence tools that track client sentiment alongside portfolio performance. Edward Jones has deployed AI systems to analyze thousands of advisor-client conversations, identifying recurring life events that trigger financial decisions. Recent data revealed 700 discussions about emergency pet surgery and 3,000 conversations regarding planned RV trips within a single month. These insights allow advisors to understand the emotional context behind monetary requests, facilitating more productive family dialogues about giving.
Contrary to predictions that AI would displace human financial advisors, the technology appears to be reinforcing the need for personalized guidance. Clients frequently use AI platforms to gather preliminary information but continue seeking human verification before making emotionally charged decisions about family wealth. Firms like LPL Financial and Edward Jones are leveraging this hybrid dynamic, using machine learning to surface relevant scenarios while relying on advisors to navigate the complex interpersonal dynamics that algorithms cannot resolve.
Edward Jones continues to expand its AI-driven conversation tracking capabilities, with all client interactions securely stored to build longitudinal profiles of evolving financial priorities and family circumstances.