US Q2 GDP Revised Up to 2.2% as Data Center Boom and Consumer Spending Defy Headwinds
AI infrastructure investment and leisure spending drive 2.2% expansion as traditional sectors contract
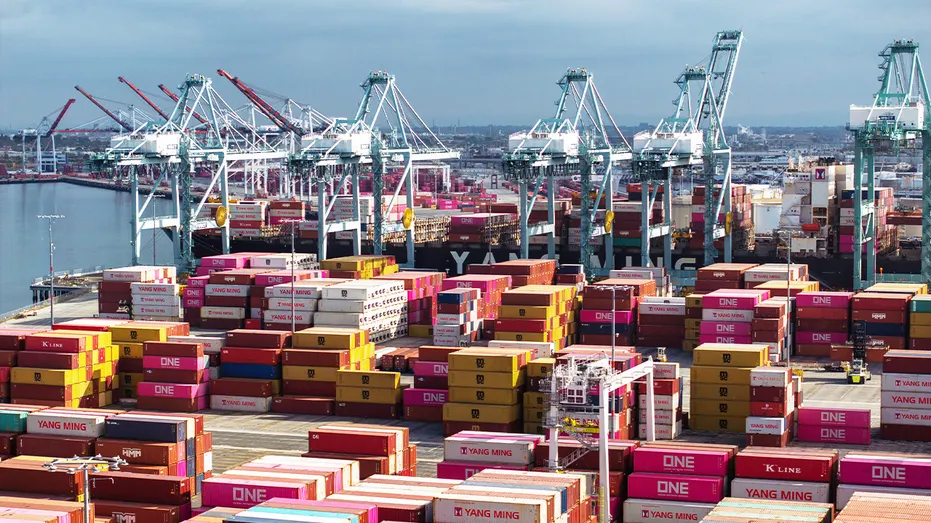
The U.S. economy expanded at a 2.2% annualized rate in the second quarter of 2026, surpassing prior estimates and defying expectations that trade friction and geopolitical instability would significantly drag on growth. The Commerce Department’s final reading, released Wednesday by the Bureau of Economic Analysis (BEA), marks an acceleration from the 2.1% pace recorded in the first quarter and tops the 1.5% consensus forecast among economists polled by LSEG.
This upward revision underscores a critical divergence in the current expansion: while traditional sectors like retail and transportation are contracting, capital-intensive industries tied to artificial intelligence infrastructure and leisure services are generating enough momentum to offset broader headwinds. The data suggests the economy is undergoing a structural rotation rather than a uniform slowdown, with growth increasingly concentrated in specific high-investment and high-consumption niches.
Real final sales to private domestic purchasers—a measure of underlying demand that strips out volatile inventory swings and government spending—surged 4.6% in the quarter. This metric was revised up by 0.4 percentage points from earlier estimates, signaling that household and business appetite for goods and services remains robust despite persistent inflation and tighter credit conditions. consumer spending revisions were led by recreation services, recreational goods, and vehicles, indicating that discretionary budgets have proven more resilient than many models predicted.
On the investment side, nonresidential structures emerged as a primary growth engine, driven largely by data center construction and commercial healthcare facilities. This reflects the tangible capital expenditure phase of the AI buildout, which has moved beyond software development into physical infrastructure. Unlike previous tech cycles that boosted GDP primarily through intangible intellectual property products, the current wave is registering heavily in fixed asset formation, providing a more durable contribution to headline growth even as other business investment categories soften.
Sector-level breakdowns reveal the uneven nature of this recovery. Real estate, rental leasing, information services, durable goods manufacturing, and finance and insurance were the leading positive contributors. Conversely, transportation, warehousing, retail trade, and nondurable goods manufacturing acted as significant drags. This bifurcation complicates the Federal Reserve’s policy calculus, as aggregate GDP strength masks underlying weakness in goods-producing and logistics-heavy industries that are typically more sensitive to interest rates.
Treasury Secretary Scott Bessent has pointed to these figures as evidence of impending economic acceleration, arguing that supply-side constraints are gradually easing. However, independent analysts caution that the 2.2% print may represent a ceiling rather than a floor. EY-Parthenon chief economist Gregory Daco projects full-year 2026 growth near 2.5%, noting that without ongoing shocks from trade policy, energy costs, and immigration restrictions, growth could have approached 3% with inflation closer to the Fed’s 2% target. The current trajectory, therefore, reflects resilience within a constrained environment rather than unimpeded potential.
For monetary policymakers, the revised GDP report arrives alongside mixed inflation signals. While the Fed’s preferred PCE gauge cooled slightly in August, it remains elevated above target. The central bank raised rates by 25 basis points earlier this month to a range of 3.75%–4%, its first hike in three years. Market pricing for the October meeting has since shifted; the CME FedWatch tool now indicates a 58.5% probability that the Fed will hold rates steady next month, up from a near-even split just days ago and a 70.9% chance of a hike one week prior.
<img src="https://nile1.com/wp-content/uploads/2026/09/1790790053_462_fed-chair-kevin-warsh-jackson-hole-2026-003.jpg" alt="Federal Reserve Chair Kevin Warsh in Jackson Hole” />
The recalibration in rate expectations hinges less on backward-looking GDP data and more on forward-looking inflation dynamics and labor market stability. Private payrolls rose by 90,000 in September according to ADP, beating forecasts and reinforcing the narrative that employment remains supportive of consumption. Yet analysts warn that wage growth continues to lag inflation, suggesting that consumer resilience may be drawing down savings or increasing leverage rather than stemming from real income gains.
Trade flows also present a nuanced picture. Imports rose during the second quarter, contributing negatively to the GDP calculation under standard accounting methods but reflecting sustained domestic demand for foreign-produced capital equipment and consumer goods. Exports increased as well, though not enough to fully offset the import surge. This dynamic highlights how strong domestic absorption can paradoxically reduce headline GDP growth even as it signals underlying economic vitality.
Looking ahead, the durability of Q2’s growth drivers faces mounting tests. Data center investment is expected to remain elevated through year-end, but its multiplier effect on broader productivity remains uncertain. Meanwhile, the consumer spending that buoyed the quarter must contend with cumulative price pressures and the delayed impact of higher borrowing costs. With first-half 2026 growth averaging approximately 2.15%, the economy has established a stable but unspectacular baseline that leaves little margin for error as fiscal and monetary policies navigate competing risks.