UK Fintechs Pay Apple’s Premium While EU Rivals Tap Free
No competing wallet has launched on British iPhones despite contactless tech driving 39% of national payments.
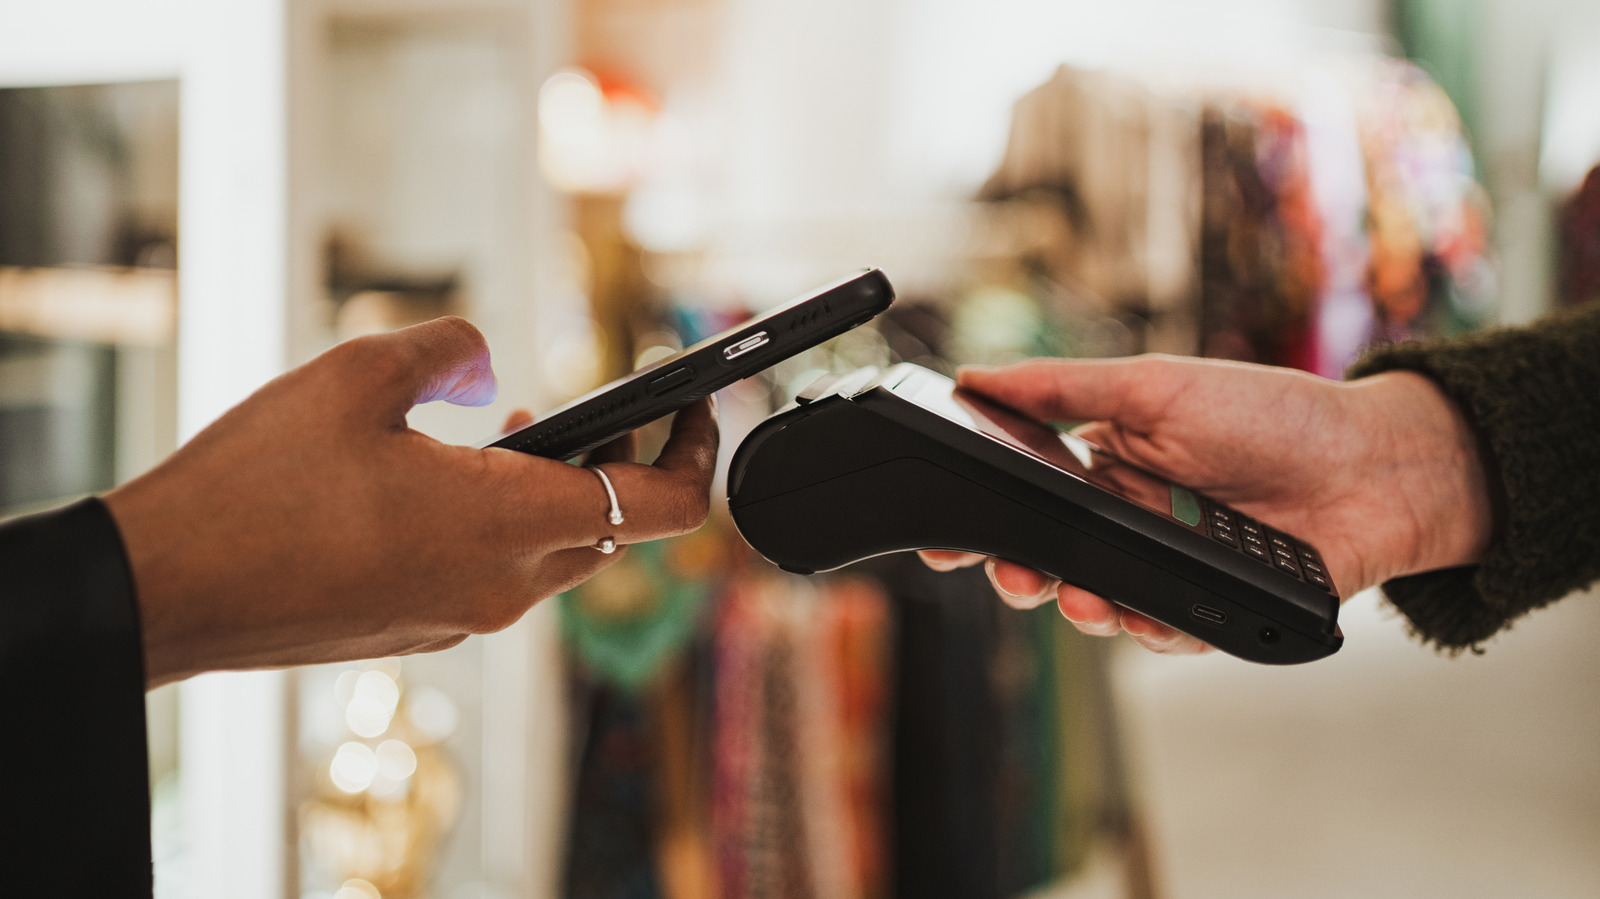
British financial technology firms are paying fees to access iPhone hardware that their European competitors secured for free two years ago. The Competition and Markets Authority (CMA) is now moving to close that gap, proposing rules that would force Apple to open its near-field communication (NFC) chip to third-party wallets without the pricing structure currently locking UK developers inside Apple Wallet.
The regulator’s intervention targets a specific market failure. Contactless transactions account for 39 percent of all payments in the UK, according to the CMA, yet no independent firm has launched a competing wallet product on British iPhones. In the European Union, where Apple struck a binding commitment with antitrust authorities in 2024 to avoid fines reaching 10 percent of its global annual turnover, developers gained direct NFC access alongside iOS features like Face ID authentication starting with iOS 18.1. British developers technically have similar technical access today, but the commercial terms keep them tethered to Apple’s ecosystem.
That tether threatens a sector employing more than 360,000 people, the CMA noted. Rather than dictate exact prices, the regulator plans to establish principles requiring “substantially lower” charges and push Apple to support the main contactless standards used internationally. The CMA stated its evidence shows neither technology raises inherent security concerns.
Apple disputes that assessment. In a statement provided to Engadget, the company said it already enables developers globally to offer secure contactless transactions directly within apps through its NFC and Secure Element platform, covering in-store payments, transit passes, car keys and event tickets. “We do not believe the CMA should require Apple to adopt an approach with lower privacy and security protections,” Apple said, adding it will “continue to engage constructively to reach an outcome that is in the best interest of our users.”
The divergence between London and Brussels highlights how post-Brexit regulatory autonomy creates fragmented compliance requirements for Big Tech. Companies operating across Europe previously aligned with single directives from the European Commission. Now they face parallel proceedings. The Digital Markets Act forced Apple’s hand in Europe; the CMA is relying on domestic competition law to extract the same concession, but through a slower, consultation-heavy process.
For consumers, the immediate consequence of the current setup is limited choice at checkout. UK iPhone users default to Apple Wallet because no alternative exists. Android users, by contrast, have been able to set competing banking or fintech apps as their primary tap-to-pay provider for years.
The public consultation closes November 17, 2026. A final decision will follow after the CMA assesses responses.