

The Family Safety Net: How America’s Sandwich Generation Is Quietly Filling the Gap Left by Policy
How the sandwich generation is quietly absorbing the costs of childcare, housing, and eldercare that policy has not addressed
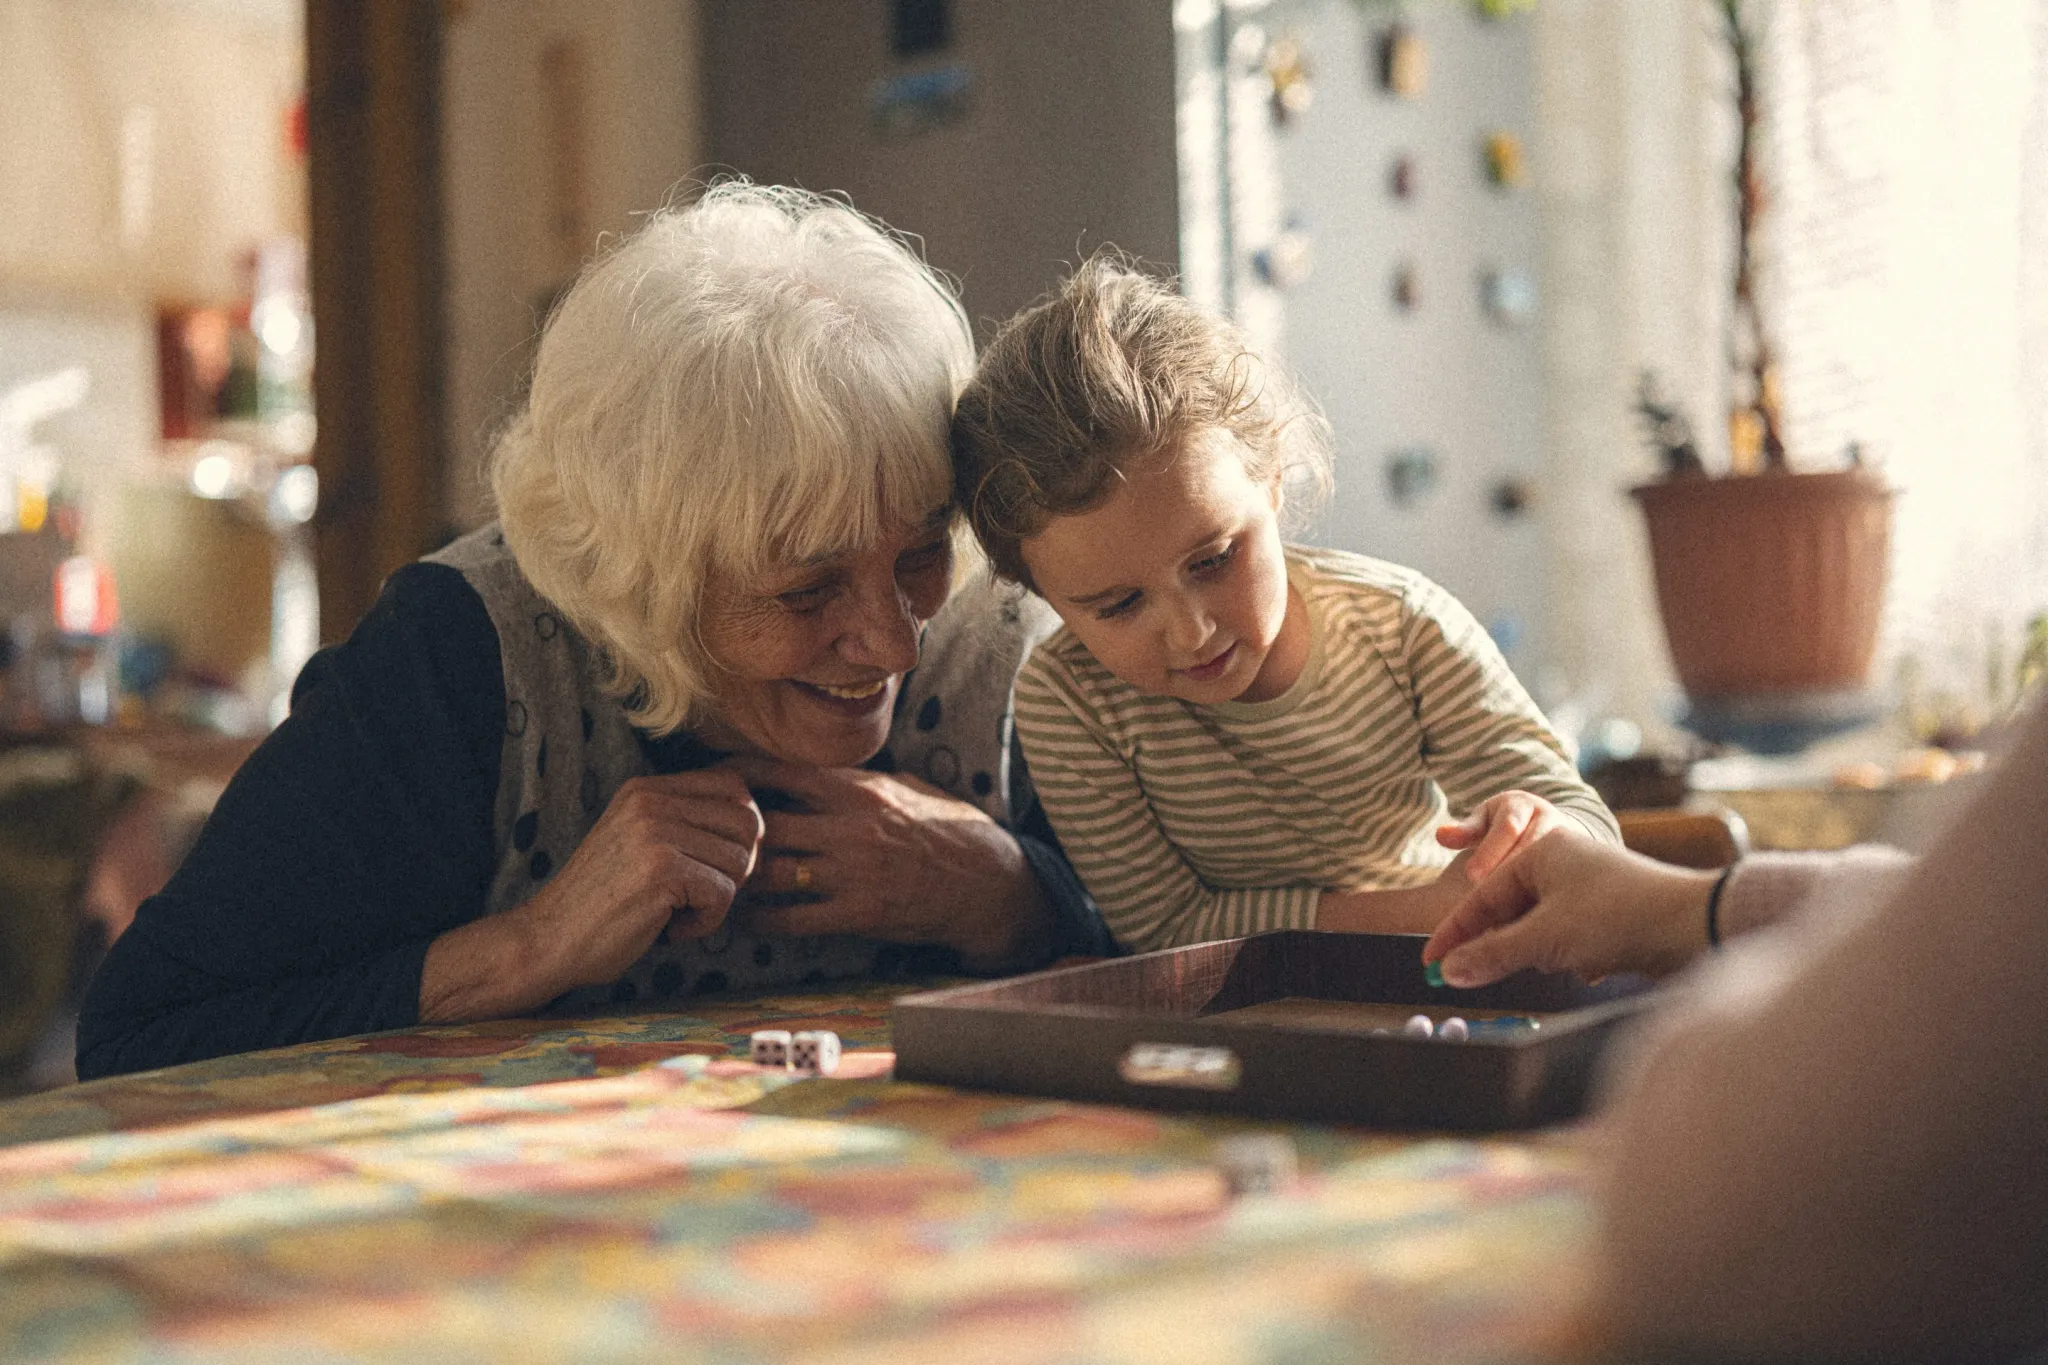
Across American households, a quiet economic reshuffle is underway. Rather than relying on government programs, employer benefits, or the anticipated Great Wealth Transfer, millions of younger parents are turning to their own parents — and grandparents are becoming an indispensable pillar of the nation’s childcare infrastructure.
According to the BMO Real Financial Progress Index, nearly two in five parents with young children expect financial assistance from older relatives within the next year. But the dependency runs deeper than cash. Among those expecting help, 43% rely on grandparents to provide childcare, while 26% count on family-funded 529 plans or savings accounts to secure their children’s educational futures.
The scale of the affordability squeeze driving this shift is staggering. American parents now spend an average of roughly 20% of their annual income on childcare, per Care.com’s 2026 Cost of Care report — nearly triple the 7% threshold the U.S. Department of Health and Human Services defines as affordable. About one in five parents exceeds $30,000 annually on childcare alone. The U.S. has no federal childcare subsidy program comparable to those in most other high-income nations, a gap that has persisted for decades.
The consequences extend well beyond household budgets. Care.com’s research found that 80% of parents say they are mentally consumed by caregiving responsibilities, and the number of parents reporting thoughts of suicide or self-harm has risen 5%. Brad Wilson, CEO of Care.com, warned that continued pressure could push parents out of the workforce entirely, compounding both financial strain and emotional distress.
“Parents are being pushed well beyond their limits by the demands of caregiving,” Wilson said. “If this continues, care pressures risk pushing more parents to cut back or step away from their careers.”
This is not simply a childcare story — it is a housing story as well, and one deeply tied to intergenerational wealth. BMO’s research found that 60% of Gen Z homeowners and 57% of Millennial homeowners say they could not have purchased a home without financial help from family. Among Gen Z adults overall, nearly six in ten expect to ask for or receive financial assistance from older relatives.
The pattern reflects a broader structural reality: while the federal government has invested heavily in homeownership incentives — mortgage interest deductions, FHA loans, tax-advantaged accounts — those benefits disproportionately favor higher earners. First-time buyers facing elevated mortgage rates and constrained inventory increasingly depend on family transfers to bridge the gap.
The timing of this generational reliance coincides with an unprecedented concentration of wealth. Cerulli Associates estimates that $124 trillion will transfer through 2048, with nearly $100 trillion originating from baby boomers and older generations. Yet Federal Reserve data from Q2 2026 shows the top 1% of households hold roughly 30% of total assets, while the bottom half holds about 5%. The wealth exists — but it is concentrated, and its distribution will shape which families benefit from the transfer.
Proximity has emerged as a decisive factor in whether families can access this informal support system. BMO found that 45% of Americans with young children live close enough to family to receive help. These parents reported saving an average of $1,915 per year on childcare and $1,443 on groceries compared with parents lacking nearby family support.
But that lifeline carries a steep cost. Roughly 70% of parents receiving family support are also responsible for the financial or emotional well-being of their aging parents, compared with 45% of those without nearby family. About seven in ten parents living near relatives who provide childcare identify as part of the “sandwich generation” — simultaneously supporting children and aging relatives.
Robin Growley, BMO U.S. Head of Consumer Products, captured the tension: “Most people make decisions to live near family with their hearts, not their spreadsheets, but those choices carry real financial consequences. Having a grandparent help raise your kids can be one of life’s greatest gifts, but family caregiving is often a reciprocal arrangement — and it can be a lot when you’re already stretched thin.”
The shift represents a fundamental departure from how American families have historically managed economic pressure. The Great Wealth Transfer was long framed as a future event — a once-in-a-generation windfall waiting to arrive. But for millions of younger families, the transfer is already happening, in real time, through grandparent-provided childcare, shared housing, and direct financial contributions. It is happening not as a single inheritance, but as a daily, ongoing subsidy that keeps household budgets afloat.
Whether this informal system can absorb the mounting pressures of childcare costs, housing unaffordability, and an aging population remains an open question. What is clear is that American families have already begun answering that question — one family decision at a time.
For parents navigating these pressures, financial planners increasingly recommend structured approaches: establishing formal agreements for family-provided childcare, setting up dedicated education savings vehicles, and creating clear boundaries around financial support to prevent caregiver burnout.
One Comment