

AI Boom Raises Bubble Risks and a Wealth Divide
Wall Street weighs AI bubble risks as technology gains concentrate wealth
The massive influx of capital into artificial intelligence infrastructure is intensifying debate across Wall Street over whether the technology sector is repeating historical boom-and-bust cycles. The debate also extends to widening disparities in wealth distribution as AI-related equities appreciate.
On the Bloomberg Billionaires Index, nine of the world’s 10 wealthiest individuals derive the bulk of their net worth from technology companies leading AI investments. The group includes Tesla and SpaceX chief executive Elon Musk, Amazon founder Jeff Bezos, and Alphabet co-founder Larry Page.
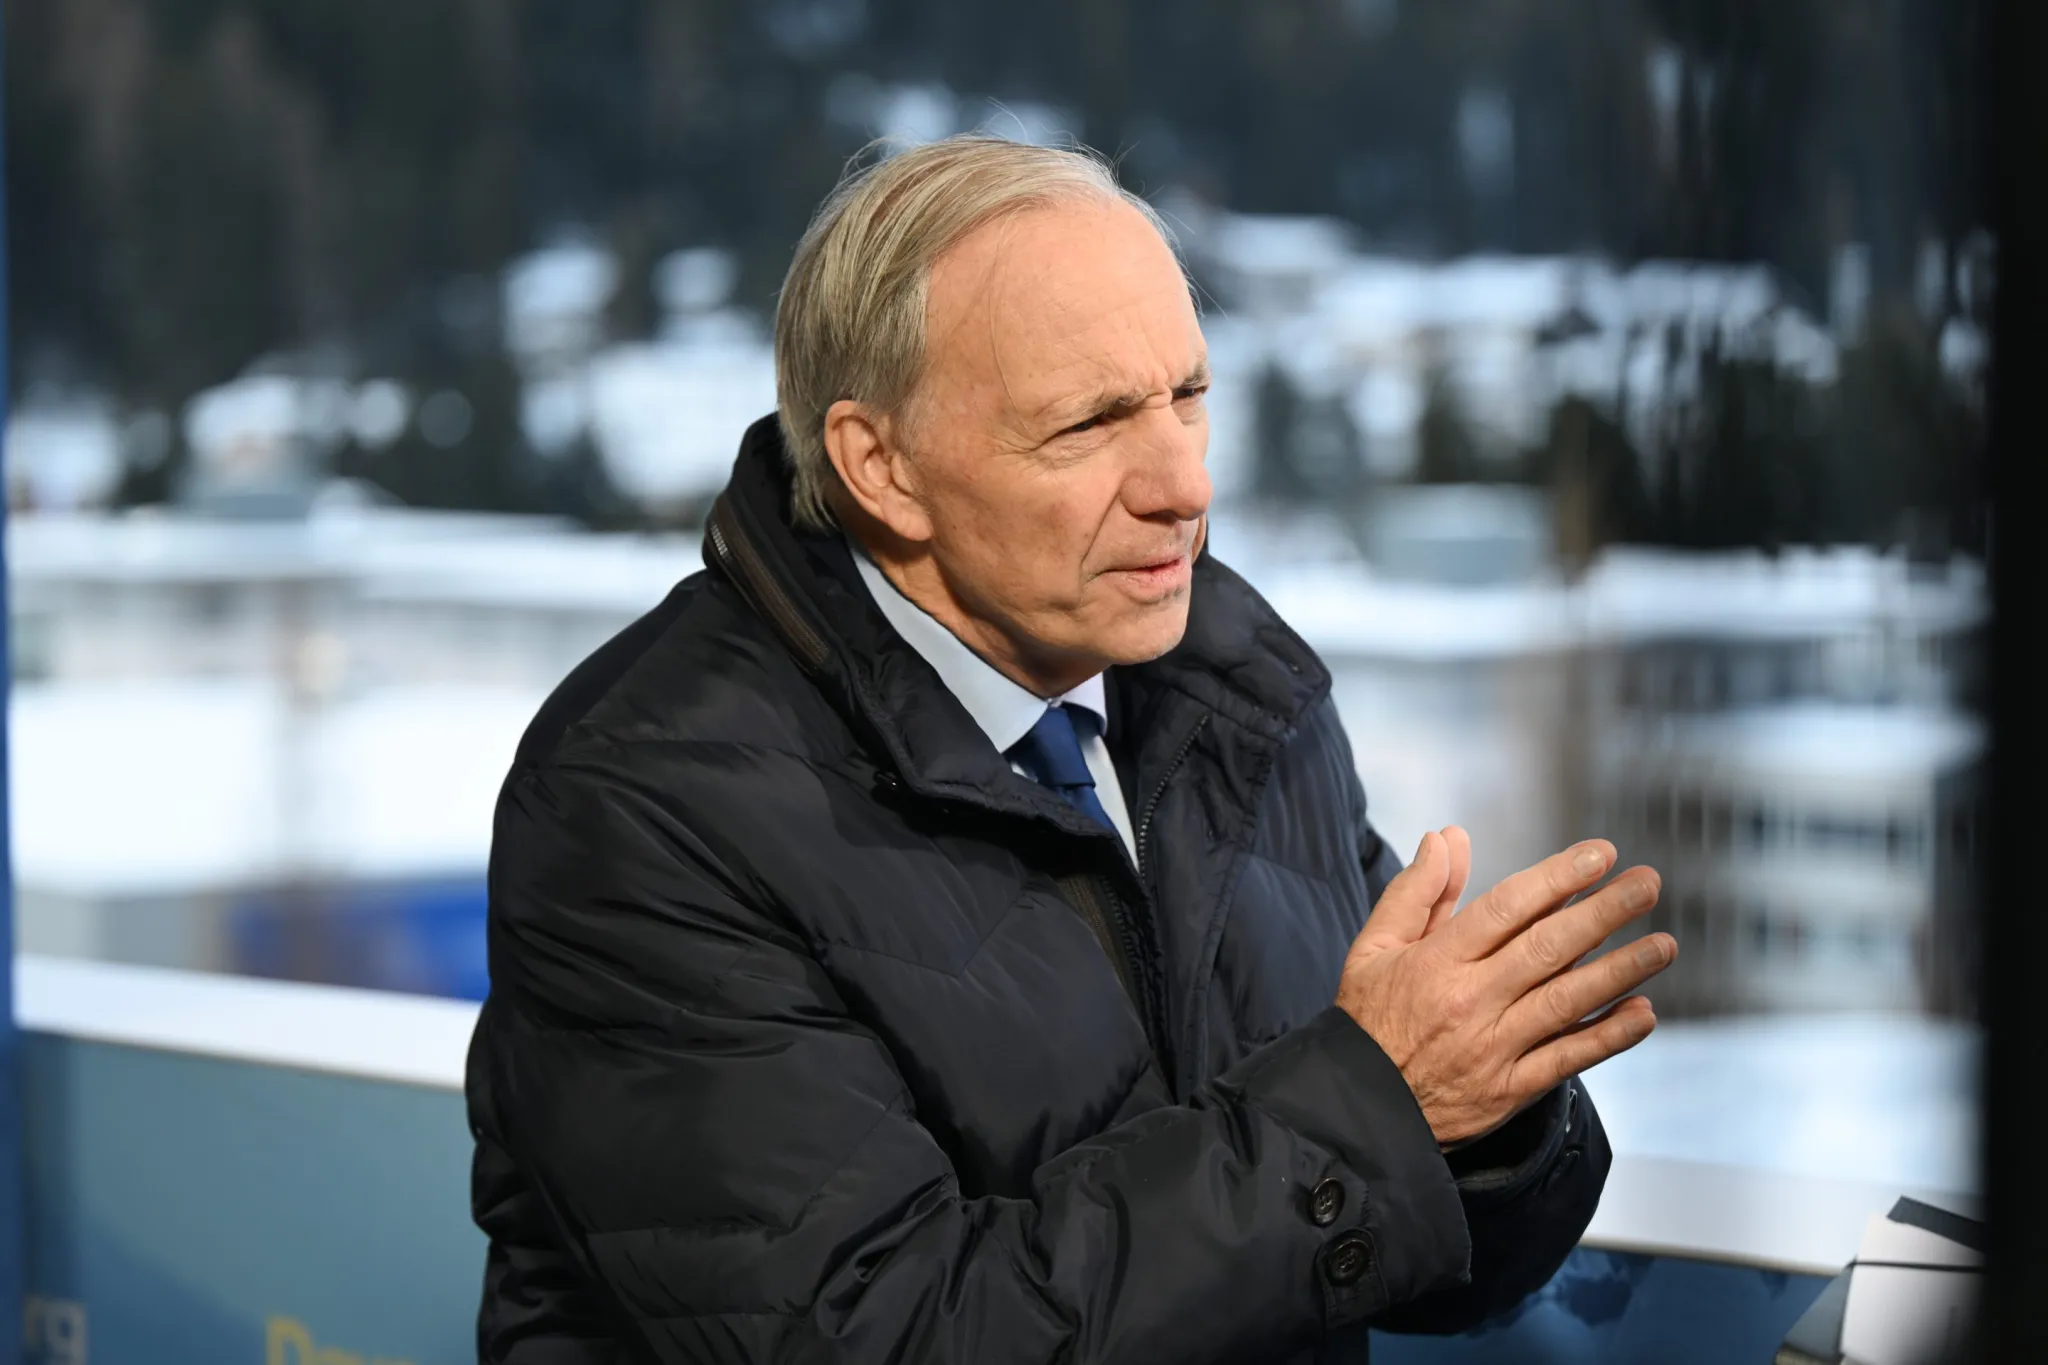
Bridgewater Associates founder Ray Dalio warned in remarks presented to the World Economic Forum that generative AI is moving through the classic stages of past speculative market cycles. Transformative technologies, he said, consistently deliver substantial long-term economic productivity, but the rush to fund them typically produces speculative asset bubbles through over-investment and debt accumulation.
The current cycle has also drawn scrutiny from JPMorgan Chase Chief Executive Jamie Dimon. He has indicated that artificial intelligence has legitimate broader economic potential, while specific segments of the AI supply chain and software ecosystem have entered speculative bubble territory.
The dynamic resembles the late-1990s dot-com era, when commercial adoption of the internet drove unprecedented equity valuations before a sharp contraction. In 1999, the tech-heavy Nasdaq Composite index surged 86% before peaking in March 2000. By October 2002, the index had plunged roughly 77%, erasing trillions of dollars in market capitalization even though the underlying technology later fundamentally reshaped the global economy.
Financial analysts remain divided over whether today’s AI-driven equity valuations carry the same systemic vulnerabilities as earlier technology bubbles. Some institutional strategists argue that current market leaders have much stronger fundamental metrics than the unprofitable internet startups of the late 1990s.
Conrad DeQuadros, head of economics at Citi Wealth, pointed to corporate balance sheets as a buffer against macroeconomic volatility. “Contrary to the corporate profit margin squeeze seen during prior investment bubbles, aggregate margins today are holding near all-time highs,” DeQuadros noted. “U.S. corporations enter this investment cycle from a position of profitability and balance sheet strength.”
Dalio described the technology’s economic potential alongside the disruption that could follow a correction. “There’s a process in which great new technologies are something that everybody wants to invest in because they’re going to change the world, and then they over-invest in them, and they create debt, and they go through a certain dynamic, in a sense, that creates a bubble, that creates a bust,” Dalio said. He added that the transition will simultaneously act as “one of the biggest productivity-enhancing, changing-the-world forces” while producing disruptive fallout as the market corrects.
The concentration of gains is visible beyond billionaire fortunes. Federal Reserve data on the distribution of U.S. household assets shows that the bottom 50% of Americans hold approximately $370 billion in corporate equities and mutual fund shares. The top 10% of households, in contrast, control more than $40 trillion of the asset class, while the top 0.1% alone account for over $16 trillion.
Dalio emphasized that distributing economic gains remains the critical challenge of the current technological wave. “People who come up with great ideas to invent productive things receive capital that enables them to do that,” Dalio said. “And then as a result of that, that produces very large differences in wealth. While a lot of people are benefiting from these miraculous, productivity-enhancing [technologies], most people are not benefiting adequately from that.”
Some technology-sector leaders have acknowledged the widening gap. Jensen Huang, founder and chief executive of semiconductor manufacturer Nvidia, whose market valuation has surged on demand for AI accelerator chips, has publicly stated that tax frameworks provide an essential mechanism for distributing corporate gains, describing taxation as a “great way for us to contribute back to society and the economy.”

One Comment