Broadcom CEO Warns AI Investors Are Gambling, Not Investing
Despite record chip sales, Broadcom's chief questions whether AI labs and enterprise buyers can generate enough revenue to justify billions in spending.
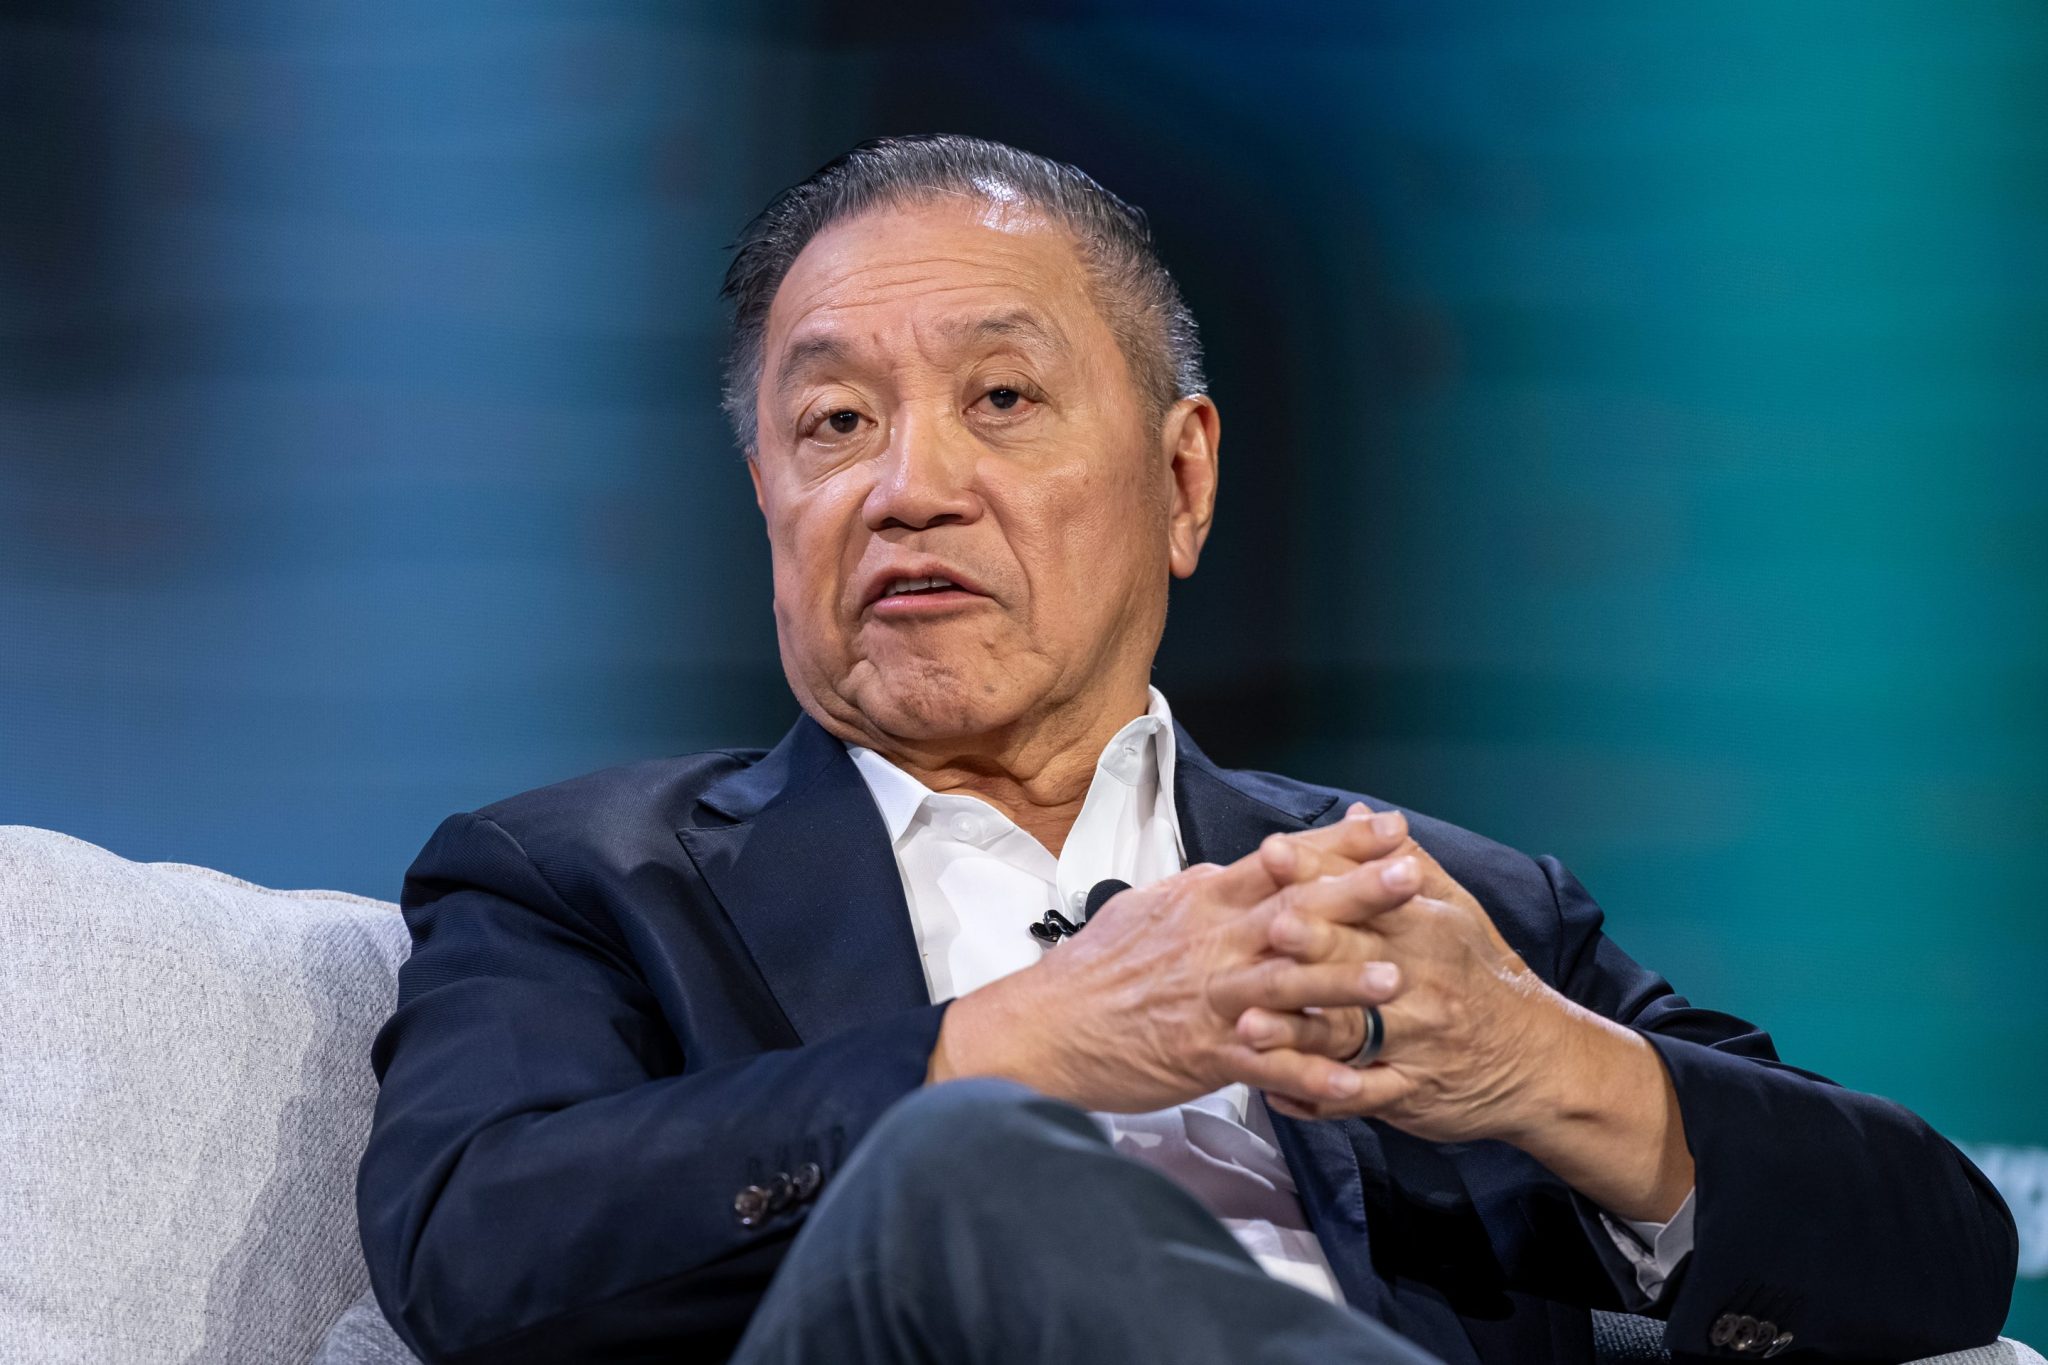
Broadcom Chief Executive Hock Tan delivered a stark assessment of the artificial intelligence economy this week, warning that capital markets are treating frontier model development like a casino while enterprises burn through computing tokens without generating measurable returns.
The critique arrives at an inflection point for the semiconductor industry. Broadcom has captured roughly $68 billion in AI chip revenue since late 2023 by manufacturing custom silicon architectures for hyperscalers building massive data center clusters. During its fiscal third quarter ended Aug. 2, that segment alone generated $16.7 billion, more than tripling year over year. Yet the company profiting directly from the hardware buildout is now publicly questioning whether the software layer purchasing those chips can sustain the spending.
Speaking at the DBS Asia Future Forward Conference in Singapore on Monday, Tan drew a sharp distinction between selling infrastructure and operating it profitably. He characterized much of the current investment flowing into AI startups as uninformed speculation driven by extreme expectations rather than unit economics.
That skepticism targets the financial architecture of leading AI laboratories. OpenAI reported reaching a $50 billion annualized revenue run rate by the end of September, a milestone often cited as proof that generative AI has achieved commercial viability. Annualized figures project a current sales pace across 12 months but do not reflect cash collected or account for operating costs. OpenAI expects to spend more than $25 billion solely on model training this year, meaning top-line growth does not currently translate to profitability.
“For now it’s still losing money because they’re spending a lot on training,” Tan said. “So frankly, it doesn’t tell anything at this point except that there is a lot of potential revenue growth out of providing frontier generative AI models.”
The economics of large language models differ fundamentally from traditional software-as-a-service businesses. Training a frontier model requires thousands of specialized accelerators running continuously for months, consuming vast amounts of electricity. Unlike standard cloud applications where marginal costs drop as user bases scale, every inference query processed by an AI lab incurs direct compute expenses. This structure forces companies to raise enormous capital rounds just to maintain operations while searching for pricing models that customers will accept.
Tan identified funding exhaustion, rather than physical supply chains, as the primary threat to the industry’s trajectory. While analysts have tracked concerns over high-bandwidth memory availability, advanced packaging capacity at foundries, and power grid limitations near data center hubs, Tan argued that a lack of investor capital “might be the biggest constraint” facing AI expansion.
Public markets are already showing signs of fatigue. Firmus, an Australian data center operator backed by Nvidia, withdrew its planned initial public offering on Oct. 9 after failing to attract sufficient demand at its targeted share price, according to Bloomberg.
Physical hardware shortages, however, remain acute. Intel CEO Lip-Bu Tan, who appeared on the same panel in Singapore, projected that AI computing hardware could stay in short supply for another two to three years. That timeline reflects the reality that fabricating advanced nodes and assembling complex server racks operates on multi-year cycles independent of software monetization challenges.
Beyond the labs building foundation models, Broadcom’s chief executive also criticized how corporate buyers are deploying the technology. He compared enterprise AI adoption to children feeding coins into arcade machines, burning through API tokens on experimental workflows that produce no financial return.
“When you are a kid you go to a video arcade, you play. Your parents give you $10 of tokens, you finish it in 10 minutes and you haven’t learned anything,” he said. “That’s what’s happening in enterprises today.”
Corporate spending patterns support the analogy. An August McKinsey survey examining AI return on investment found that while 80% of respondents reported personal productivity gains, only 37% said the technology contributed to their organization’s earnings before interest and taxes. Approximately one in five respondents indicated that AI-related operating expenses, including token consumption fees charged by model providers, had actively constrained their ability to use the technology.
This gap between individual utility and corporate profitability creates friction for hyperscalers attempting to justify continued capital expenditure. Cloud providers such as Amazon Web Services, Microsoft Azure, and Google Cloud purchase Broadcom’s custom application-specific integrated circuits to lease compute capacity to enterprise clients. If those clients cannot demonstrate hard financial returns from AI workloads, pressure will eventually transfer up the stack to the infrastructure owners funding the chip orders.
Broadcom continues to secure long-term agreements with major cloud operators designing proprietary processors, insulating its near-term revenue stream from software-layer volatility. The company remains scheduled to report its fiscal fourth-quarter earnings in December.