Ripple National Trust Bank Won Its Charter While a Lawsuit Seeks to Void It
The charter arrived while the rule behind it is on trial — and the stablecoin law's deadline is 83 days away.
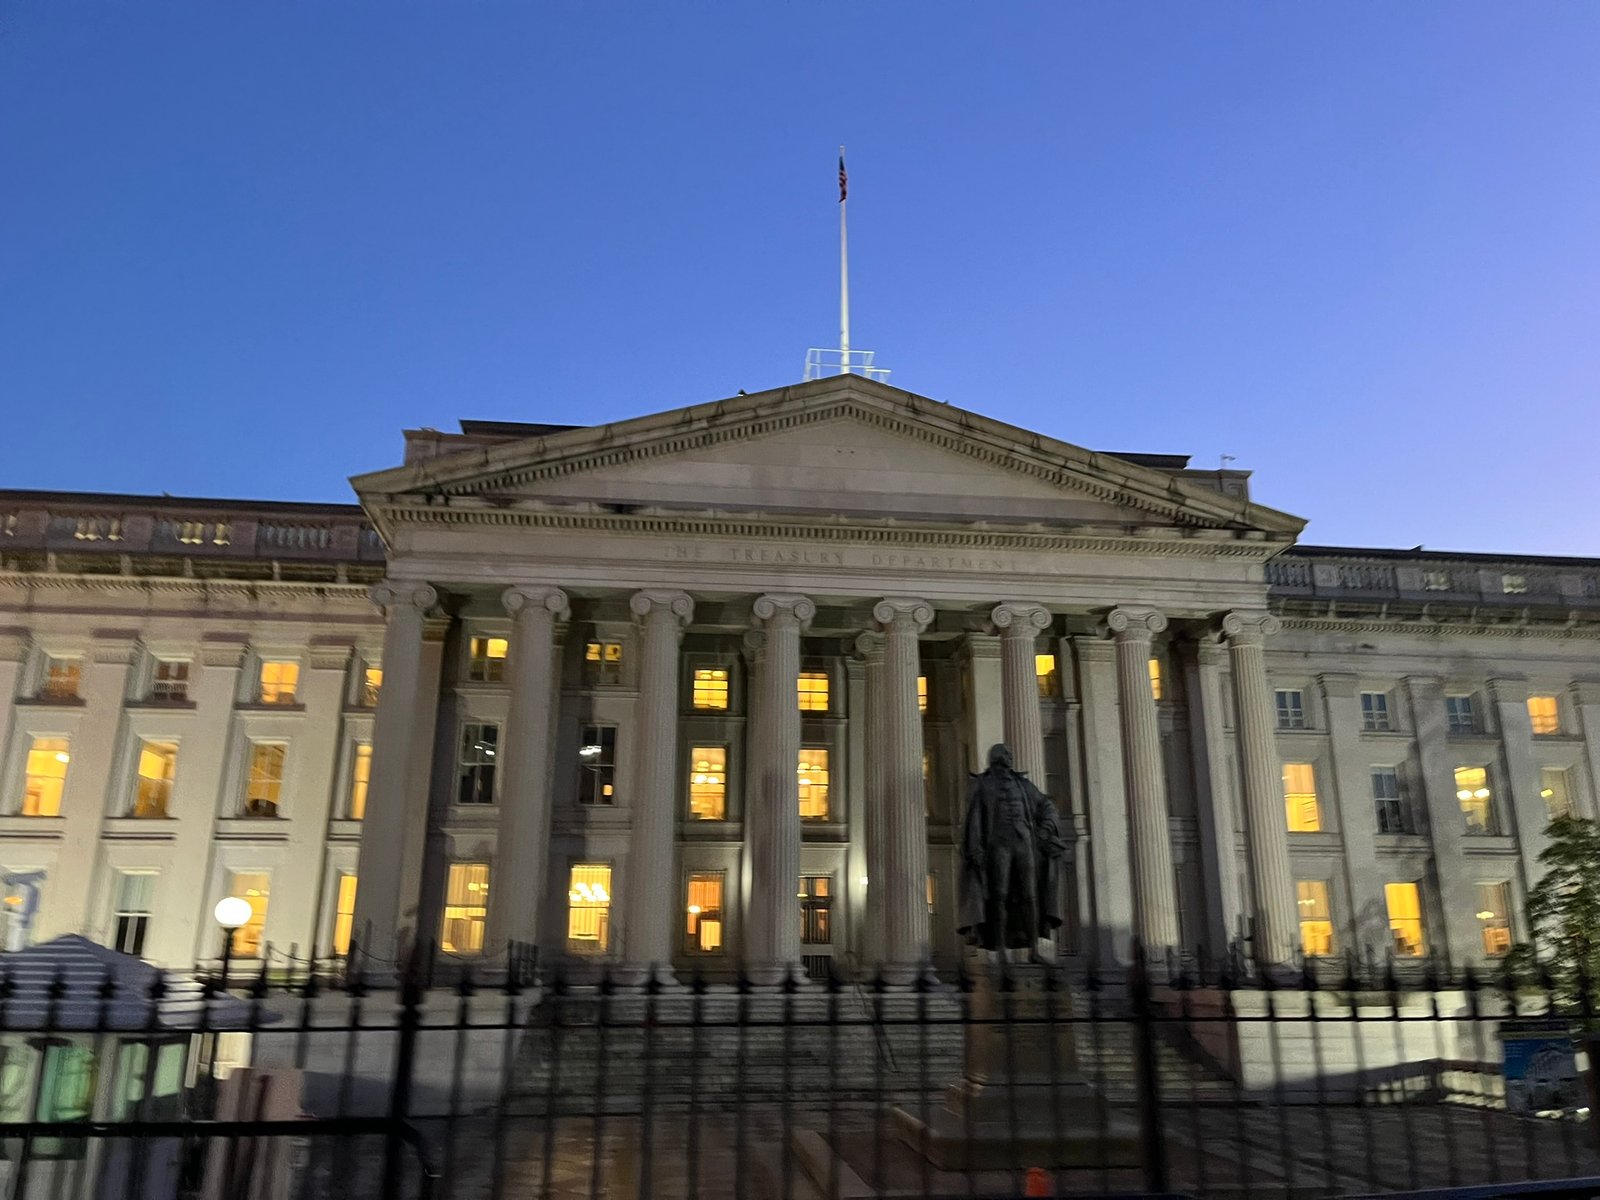
Twenty-four days separated them. The Independent Community Bankers of America had sued the Office of the Comptroller of the Currency on October 2 in federal court in Washington, asking a judge to find unlawful the rule under which crypto firms get national trust charters. On October 26, the OCC granted Ripple final approval for Ripple National Trust Bank.
Under the approval, the bank will manage the segregated reserves behind Ripple’s RLUSD stablecoin, act as collateral trustee over those reserves for token holders, and offer fiduciary custody of digital assets to enterprises once it opens. It does not let Ripple take deposits or make loans, and the bank carries no federal deposit insurance. Ripple has not said when the bank will open.
The lawsuit, filed in the U.S. District Court for the District of Columbia as case 1:26-cv-03441, targets the OCC’s March 2, 2026 final rule related to Interpretive Letter No. 1176, a January 2021 letter that stretched the trust charter to non-fiduciary business. The community bankers want the court to find both the rule and the letter unlawful, and to vacate the conditional charter the OCC gave Protego Holdings in February 2026. Rebeca Romero Rainey, the group’s president and chief executive, said in the group’s October 2 statement: “Congress did not create the national trust charter as a side door into the banking system for crypto firms seeking the credibility of a federal bank charter without the Community Reinvestment Act obligations, consolidated supervision, capital and liquidity standards, and FDIC insurance that apply to insured depository institutions.”
The complaint, as reported, counts 21 trust-bank charters the OCC has approved or conditionally approved, at least 13 of them tied to digital assets, which is why a ruling against the agency would reach past one company. The bankers’ core claim is that Congress never authorized a national bank that neither takes deposits nor performs fiduciary work: before the recent influx, the group says, the OCC had never chartered one, and the agency has not managed an uninsured bank receivership in nearly a century. Comptroller Jonathan Gould answered that line in December 2025, when he told a Blockchain Association audience that national trusts have handled non-fiduciary custody for decades and that barring it would disrupt well over a trillion dollars in traditional trust business. “There is simply no justification for considering digital assets differently,” he said.
Ripple was one of five crypto firms the OCC conditionally approved on December 12, 2025. Circle‘s First National Digital Currency Bank got the other newly built charter, while BitGo, Fidelity Digital Assets and Paxos converted state charters into national ones, joining 60 existing national trust banks. Circle reached final approval on July 10, 2026. BitGo was already there. That leaves Ripple as the second newly built bank from the group to finish the process. The queue behind Ripple was already long before the lawsuit: Crypto.com and Stripe’s Bridge won conditional approval in February 2026 and Coinbase followed in April. Rain applied for a charter in October, after the suit was filed.
The GENIUS Act‘s stablecoin rules take effect on January 18, 2027. The OCC’s Bulletin 2026-51, dated October 21, says issuing a payment stablecoin in the United States without approval after that date carries criminal penalties, and that issuers already operating here with a substantially complete application pending can generally expect a waiver of up to 12 months. Applications are not open yet. The agency will start taking them only after the White House budget office approves its forms, and it has promised a decision on completeness within 30 days and action within 120 days of that determination. On October 26, the same day Ripple’s approval landed, the OCC used its X account to recruit the plaintiffs’ own members into the new system, writing: “Interested community banks are encouraged to consider applying to become, or for a subsidiary to become, a permitted payment stablecoin issuer, as applicable.”
Three different hands will hold pieces of RLUSD’s backing. Standard Custody & Trust Company, Ripple’s New York-regulated trust company, keeps issuing the token. Ripple National Trust Bank will manage the segregated reserves and act as trustee over them for holders. Ripple names BNY as the primary reserve custodian. It holds most of those reserves. Standard Chartered opened a competing custody lane on October 12, offering institutional custody of RLUSD from its Dubai branch, with plans alongside Ripple and LMAX Group to let clients post the token as trading collateral.
In January 2021 the OCC conditionally approved Anchorage Trust Company’s conversion into Anchorage Digital Bank, the first crypto-native national trust bank, and Protego and Paxos had conditional approvals of their own within months. Anchorage stayed the only crypto firm to hold such a charter until the December 2025 round, and the community bankers’ opposition was already on the record in a joint trades letter on Interpretive Letter 1176 in May 2021. Brad Garlinghouse, Ripple’s chief executive, framed the October approval on X as proof of his long argument that crypto and banks work better together: “The revolution isn’t happening outside the system. It’s happening from within it.”
The most recent monthly attestation put 2,325,969,308 RLUSD outstanding against $2,446,312,864 in reserves, a cover of 105.17%. A September dashboard snapshot put circulation at $2.409 billion against $2.5315 billion in reserves, with about 61% of the supply on Ethereum and 39% on the XRP Ledger. Supply has grown about 86% since January, from roughly $1.38 billion to $2.57 billion, while XRP fell about 37% over the same span, from $2.08 to $1.31.