U.S. Debt Service Costs Surge $95 Billion Per Percentage Point as Bond Market Signals Fiscal Tipping Point
Each percentage point adds $95B in annual interest as bond markets price in fiscal risk premium
The U.S. government now spends $95 billion more each year on interest payments for every single percentage point the Federal Reserve raises rates, according to Bank of America analysts. The calculation lays bare a mechanical trap: with $40 trillion in outstanding debt, even modest rate shifts rewrite the federal budget on a scale that dwarfs most discretionary spending programs.
Treasury interest costs topped $2 trillion for fiscal year 2026, the department confirmed last week. That figure exceeds the entire GDP of Italy and represents a compulsory transfer from taxpayers to bondholders that no appropriations bill can alter.
The Congressional Budget Office modeled two scenarios through 2036. If rates run 1.5 percentage points above current projections, deficits swell by $6 trillion and net interest costs jump $4.9 trillion. A half-point increase still adds $1.9 trillion to projected debt and $1.6 trillion in extra interest. The difference between the two scenarios — $3.3 trillion in additional interest expense — exceeds the projected cost of the entire 2017 Tax Cuts and Jobs Act over a decade.
“Higher yields compound into materially greater interest expense and Treasury financing needs over time,” wrote BofA analysts Meghan Swiber, Stephen Juneau, Mark Cabana, and Ralph Axel. “Debt spiral starts when interest costs exceed nominal growth.”
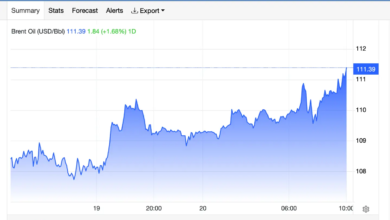
Moody’s chief economist Mark Zandi argues the spiral may already be engaging. The 10-year Treasury yield has climbed roughly one percentage point this year — among the sharpest moves of any major economy. Countries carrying the heaviest interest burdens have generally seen the largest yield increases, Zandi noted over the weekend, suggesting global investors are pricing in a fiscal risk premium unique to the United States.
“A vicious cycle threatens to take hold,” Zandi wrote. “Higher rates adding to the interest payments and debt load, which in turn pushes rates up even more.”
BofA’s team reached a similar conclusion: an unchanged deficit picture is becoming a “bigger financing problem” as elevated yields feed through to the debt stock. Interest expense compounds, financing needs rise, and the fiscal trajectory becomes “less sustainable” — their phrase — independent of any policy choices Congress or the White House might make.
The mathematics are indifferent to political pressure. President Donald Trump and his team have lobbied the Federal Open Market Committee aggressively for lower rates, targeting Chairman Kevin Warsh much as they did his predecessor Jerome Powell. But the bond market’s verdict arrives in daily auction results and yield curves, not in policy statements.
Mortgage rates, tied to long-dated Treasuries, have risen alongside the 10-year yield, undermining the administration’s stated goal of improving housing affordability. The same dynamic that increases government borrowing costs filters directly into consumer credit, auto loans, and corporate debt.
Historical context sharpens the concern. In the post-war era, the U.S. has never carried a debt-to-GDP ratio above 120% while simultaneously facing positive real interest rates. The current combination — debt exceeding 120% of GDP with the 10-year yield above 4.5% — places the fiscal arithmetic in uncharted territory.
The CBO’s baseline already assumes rates normalize toward historical averages. The alternative scenarios demonstrate how fragile that baseline is: a persistent 150-basis-point surprise doesn’t just add cost linearly. It changes the denominator of debt sustainability by slowing growth while accelerating the numerator.
“Even if primary deficits remain largely unchanged, the growing interest burden materially increases the government’s financing needs,” the BofA analysts emphasized. The word “materially” does the work of understatement: the interest bill alone now exceeds Medicaid spending and approaches the defense budget.
Foreign holders of U.S. debt have reduced their share of Treasuries to roughly 30%, down from 43% a decade ago. Domestic banks, money-market funds, and the Federal Reserve itself have absorbed the difference. That shift concentrates refinancing risk within the U.S. financial system, where regulatory capital rules and liquidity requirements create their own feedback loops.
The next Treasury refunding announcement, due in November, will test whether demand at current yields matches the torrent of new issuance required to roll over maturing debt and fund fresh deficits. Primary dealer take-down rates and bid-to-cover ratios will offer the market’s real-time judgment on whether the fiscal trajectory has crossed from difficult to unsustainable.