IMF Warns U.S. Growth Cannot Fix $40 Trillion Debt Crisis
Interest payments now consume 20% of federal revenue as Treasury officials clash with global economists over growth-based solutions.
Net interest payments now consume roughly 20% of all federal revenue, a fiscal burden that has forced the International Monetary Fund to publicly challenge the core economic strategy of the current U.S. administration.
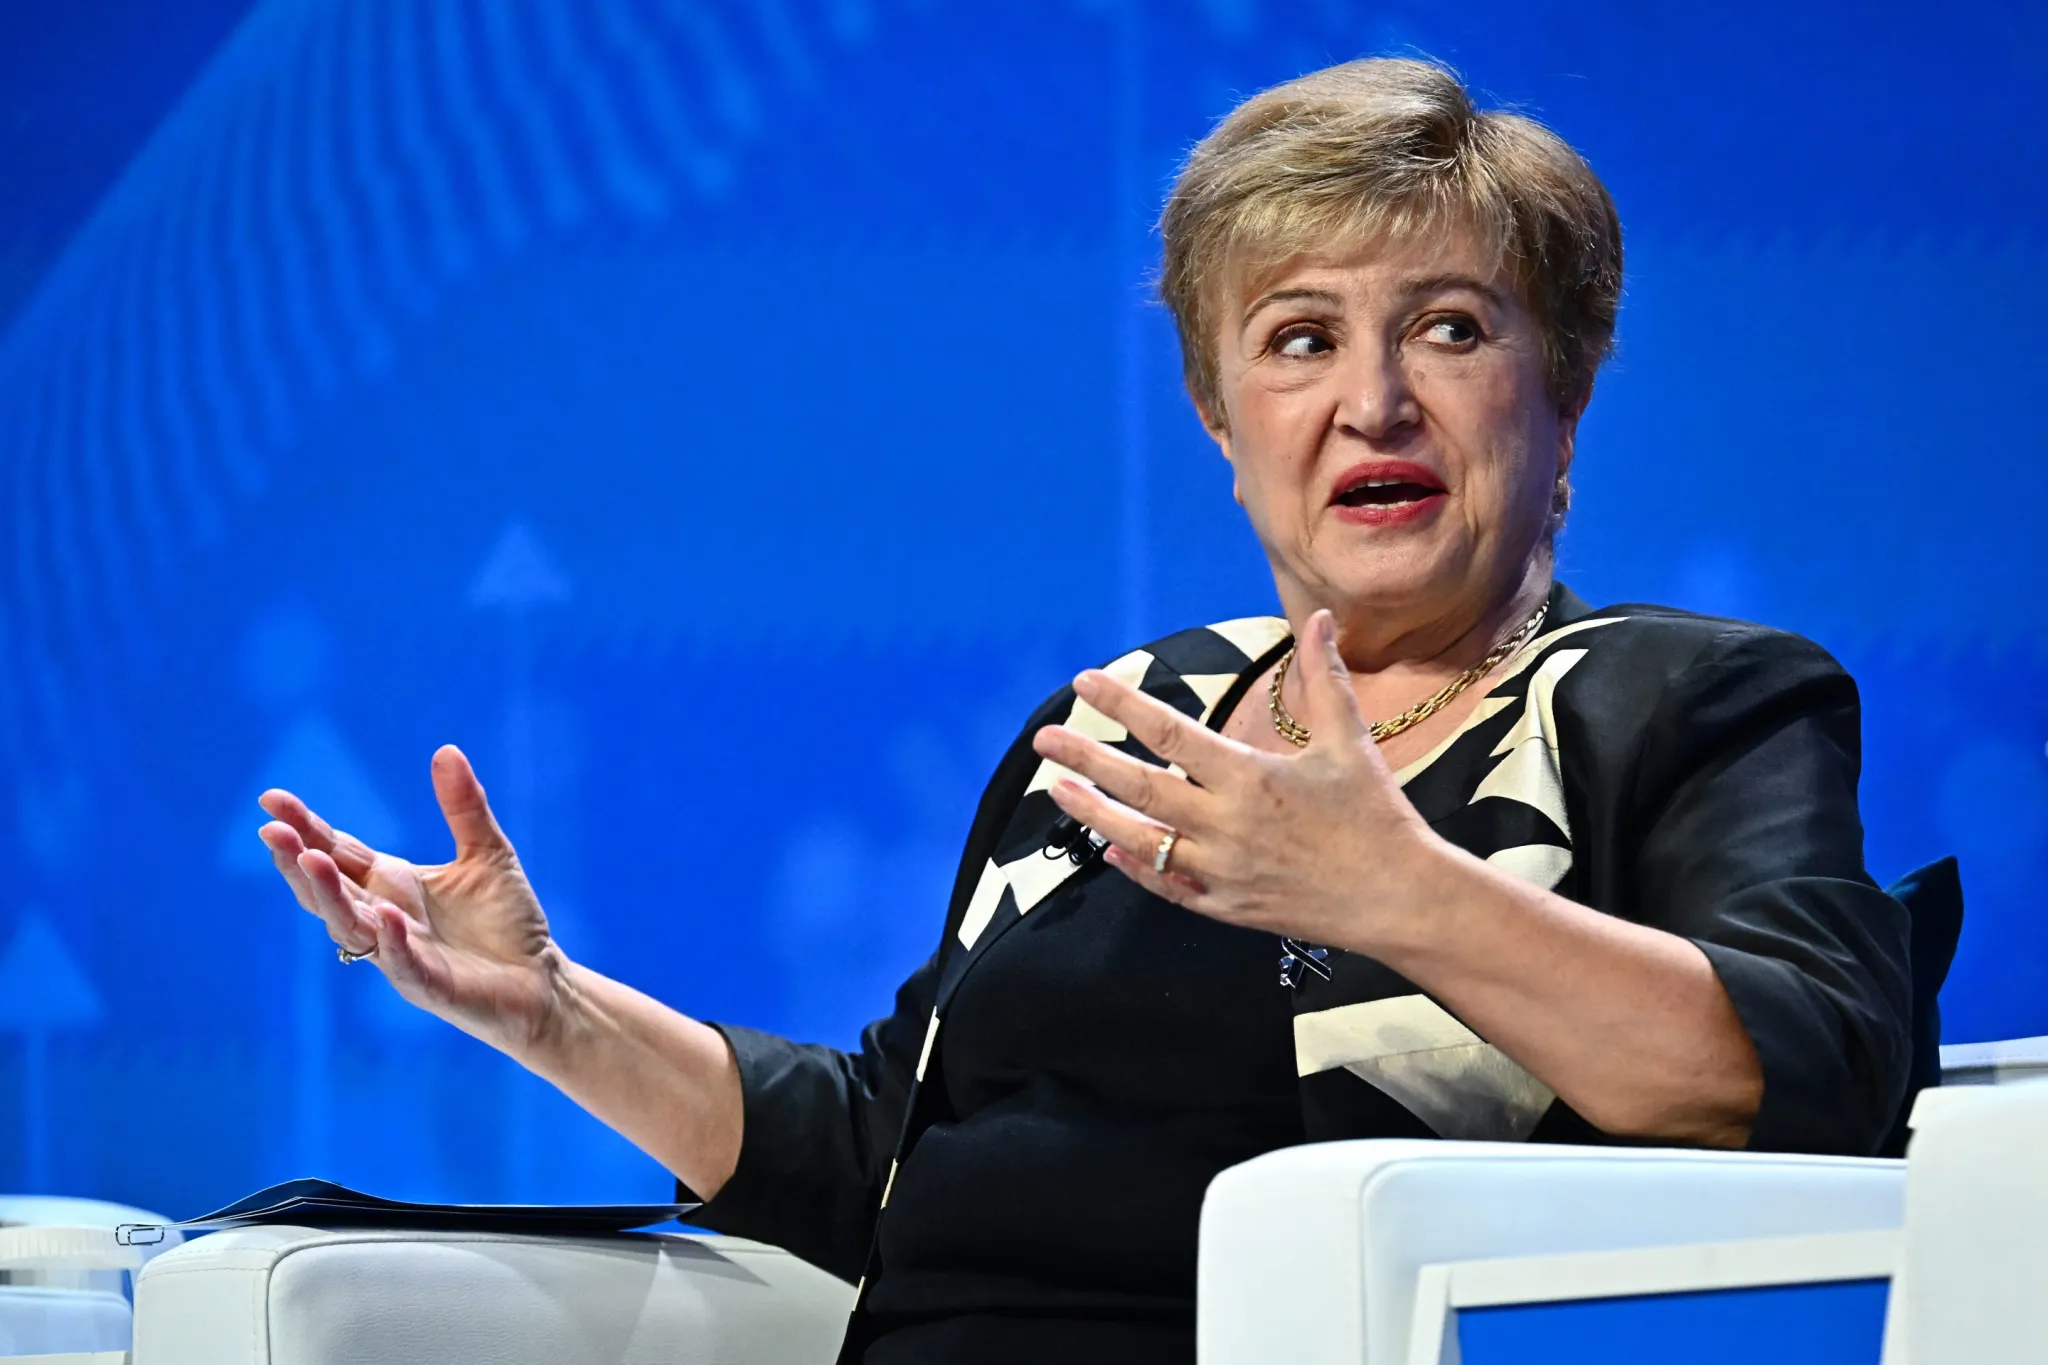
Speaking at the IMF’s annual meetings in Bangkok this week, Managing Director Kristalina Georgieva dismissed the premise that accelerating gross domestic product can resolve a national debt that has reached $40.3 trillion. While acknowledging that expansion eases debt loads, she stated the budget deficit must contract through direct policy adjustments rather than relying on economic momentum alone.
The Treasury Department responded by attacking the credibility of the institution issuing the warning. David Zervos, counselor to Treasury Secretary Scott Bessent, pointed to the IMF’s failure to anticipate the 1997 Asian financial crisis and the 2008 global collapse as evidence that its forecasting models are unreliable.
This clash exposes a widening gap between Washington’s fiscal optimism and the mathematical realities tracked by independent budget analysts. The U.S. gross debt-to-GDP ratio stands at approximately 126%. Publicly held debt, which excludes intragovernmental holdings like the Social Security trust fund, sits at 100% of GDP — levels unseen since the immediate aftermath of World War II, according to the Committee for a Responsible Federal Budget.
Secretary Bessent has consistently argued that sustained 3% annual growth, driven partly by artificial intelligence adoption, will stabilize the ledger. “There’s nothing magic about the $40 trillion number,” Bessent said in August. “And we can grow our way out of that.”
Historical data contradicts this target. The U.S. economy has achieved 3% calendar-year growth only five times over the past two decades, most recently in 2019. Current projections estimate 2.2% growth for 2026, following a 2% expansion in 2025.
Congressional Budget Office Director Phillip Swagel recently quantified exactly why organic expansion falls short. Stabilizing the debt trajectory through growth alone would require real GDP expansion of 5% to 6% annually — a pace the modern U.S. economy has never sustained during peacetime. Swagel concluded that structural changes to taxation and spending remain the only viable path.
Without those changes, the mechanics of compounding interest threaten to overtake the broader economy. The Committee for a Responsible Federal Budget projects that by fiscal 2031, the average interest rate on federal debt will exceed the nation’s economic growth rate. When borrowing costs outpace GDP expansion, each new dollar borrowed generates less economic output than the interest it accrues, creating a self-reinforcing cycle that historically forces sudden, severe austerity measures.
The consequences of this trajectory extend far beyond domestic appropriations. U.S. Treasuries serve as the foundational collateral and risk-free benchmark for global financial markets. In an April review of the American economy, the IMF’s executive directors warned that the current fiscal path creates a “financial stability tail risk” for the entire international system, given the centrality of the Treasury market to global liquidity.
Bessent and White House budget director Russ Vought have indicated they are developing a comprehensive deficit-reduction framework with President Donald Trump. No legislative text or specific targets have been released.
As of mid-October 2026, the Treasury reports the total outstanding public debt at $40.3 trillion.