US Inflation Forecast to Hit 3.6% as War and AI Costs Mount
Gas shocks from the Iran conflict and AI-driven semiconductor costs push consumer prices higher as the Fed weighs further rate hikes.

U.S. consumer prices are expected to have accelerated sharply in September, driven by a surge in gasoline costs tied to the Iran war and rising electronics prices fueled by the artificial intelligence infrastructure buildout. The Labor Department is scheduled to release the Consumer Price Index on Wednesday morning, with economists surveyed by FactSet forecasting a 3.6% annual increase, up from 3.4% in August.
The monthly jump is projected at 0.6%, which would mark the steepest one-month increase since April. Gasoline prices alone surged roughly 9% between August and September, acting as the primary engine for the broader inflationary spike. Pump prices averaged $4.34 per gallon nationwide on Tuesday, according to AAA data, remaining elevated despite ticking slightly lower in recent weeks.
This energy shock has begun migrating into adjacent sectors. Airfares have climbed approximately 23% over the past year as jet fuel costs rise. The ripple effects are now hitting grocery aisles. PepsiCo announced last week that it will raise prices on snack foods including Doritos, Ruffles, Sun Chips, and select sodas, explicitly citing higher expenses for fuel, aluminum, and food ingredients.
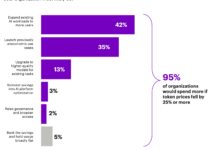
Beyond energy and groceries, a separate inflationary pressure is emerging from the technology sector. The massive capital expenditure required to build out artificial intelligence data centers has strained global supplies of semiconductors, computer equipment, and electrical components. Manufacturers are passing these elevated input costs directly to consumers. Nintendo raised the price of its Switch 2 gaming console by 11% to $499.99 on Sept. 1. Apple’s iPhone 17 launched at roughly 10% more than its predecessor, reflecting both new capabilities and tighter component pricing.
Core inflation, which strips out volatile food and energy categories to reveal underlying price trends, is forecast to have risen 2.5% annually in September, edging up from 2.4% in August. Monthly core prices are expected to show a modest 0.2% gain. While closer to the Federal Reserve’s 2% target, core inflation has remained largely stagnant near this level since January, just before the outbreak of the Iran conflict in late February.
The persistence of these price pressures complicates monetary policy. Fed Chairman Kevin Warsh oversaw the central bank’s first interest rate hike in three years last month, lifting the benchmark short-term rate to approximately 3.9%. Warsh stated at the time that summer inflation reports showed no meaningful improvement in underlying trends.
However, traditional rate hikes are a blunt instrument against supply-driven inflation. Higher borrowing costs can dampen consumer demand and cool wage growth, but they cannot resolve geopolitical disruptions to oil markets or semiconductor shortages caused by the AI boom. Several Fed officials have signaled a preference for patience. Markets broadly expect the central bank to hold rates steady at its Oct. 27-28 policy meeting, with policymakers projecting only one additional hike before the end of the year, potentially in December.
The economic strain carries immediate political consequences ahead of the midterm elections. An Associated Press-NORC Center for Public Affairs Research poll found that only 17% of U.S. adults approve of President Trump’s handling of the cost of living. His overall approval rating on the economy fell to 26%, marking a new low for his administration.