France Sovereign Default Risk Rises as Bond Yields Hit 2002 High
Political polarization drives CDS pricing above UK and EU peers as 2027 election looms
French sovereign debt is facing its most severe credibility test in over a decade as credit default swap (CDS) pricing has surpassed that of every other major European economy and the United Kingdom. The cost to insure against a French government default reached 81 basis points early Friday, signaling that traders are no longer viewing fiscal deterioration as a distant theoretical risk but as an immediate market reality driven by political paralysis.
This repricing coincides with 10-year OAT yields climbing to 4.989%, their highest level since 2002. The spread between French and German benchmark bonds widened to 152 basis points, a gap not seen since the height of the eurozone sovereign debt crisis in 2011. While these metrics have retreated slightly from intraday peaks, the structural drivers remain intact. Unlike the 2011 crisis, which was largely triggered by external contagion from Greece, current stress is idiosyncratic to France’s domestic political dysfunction and inability to pass credible budgets.
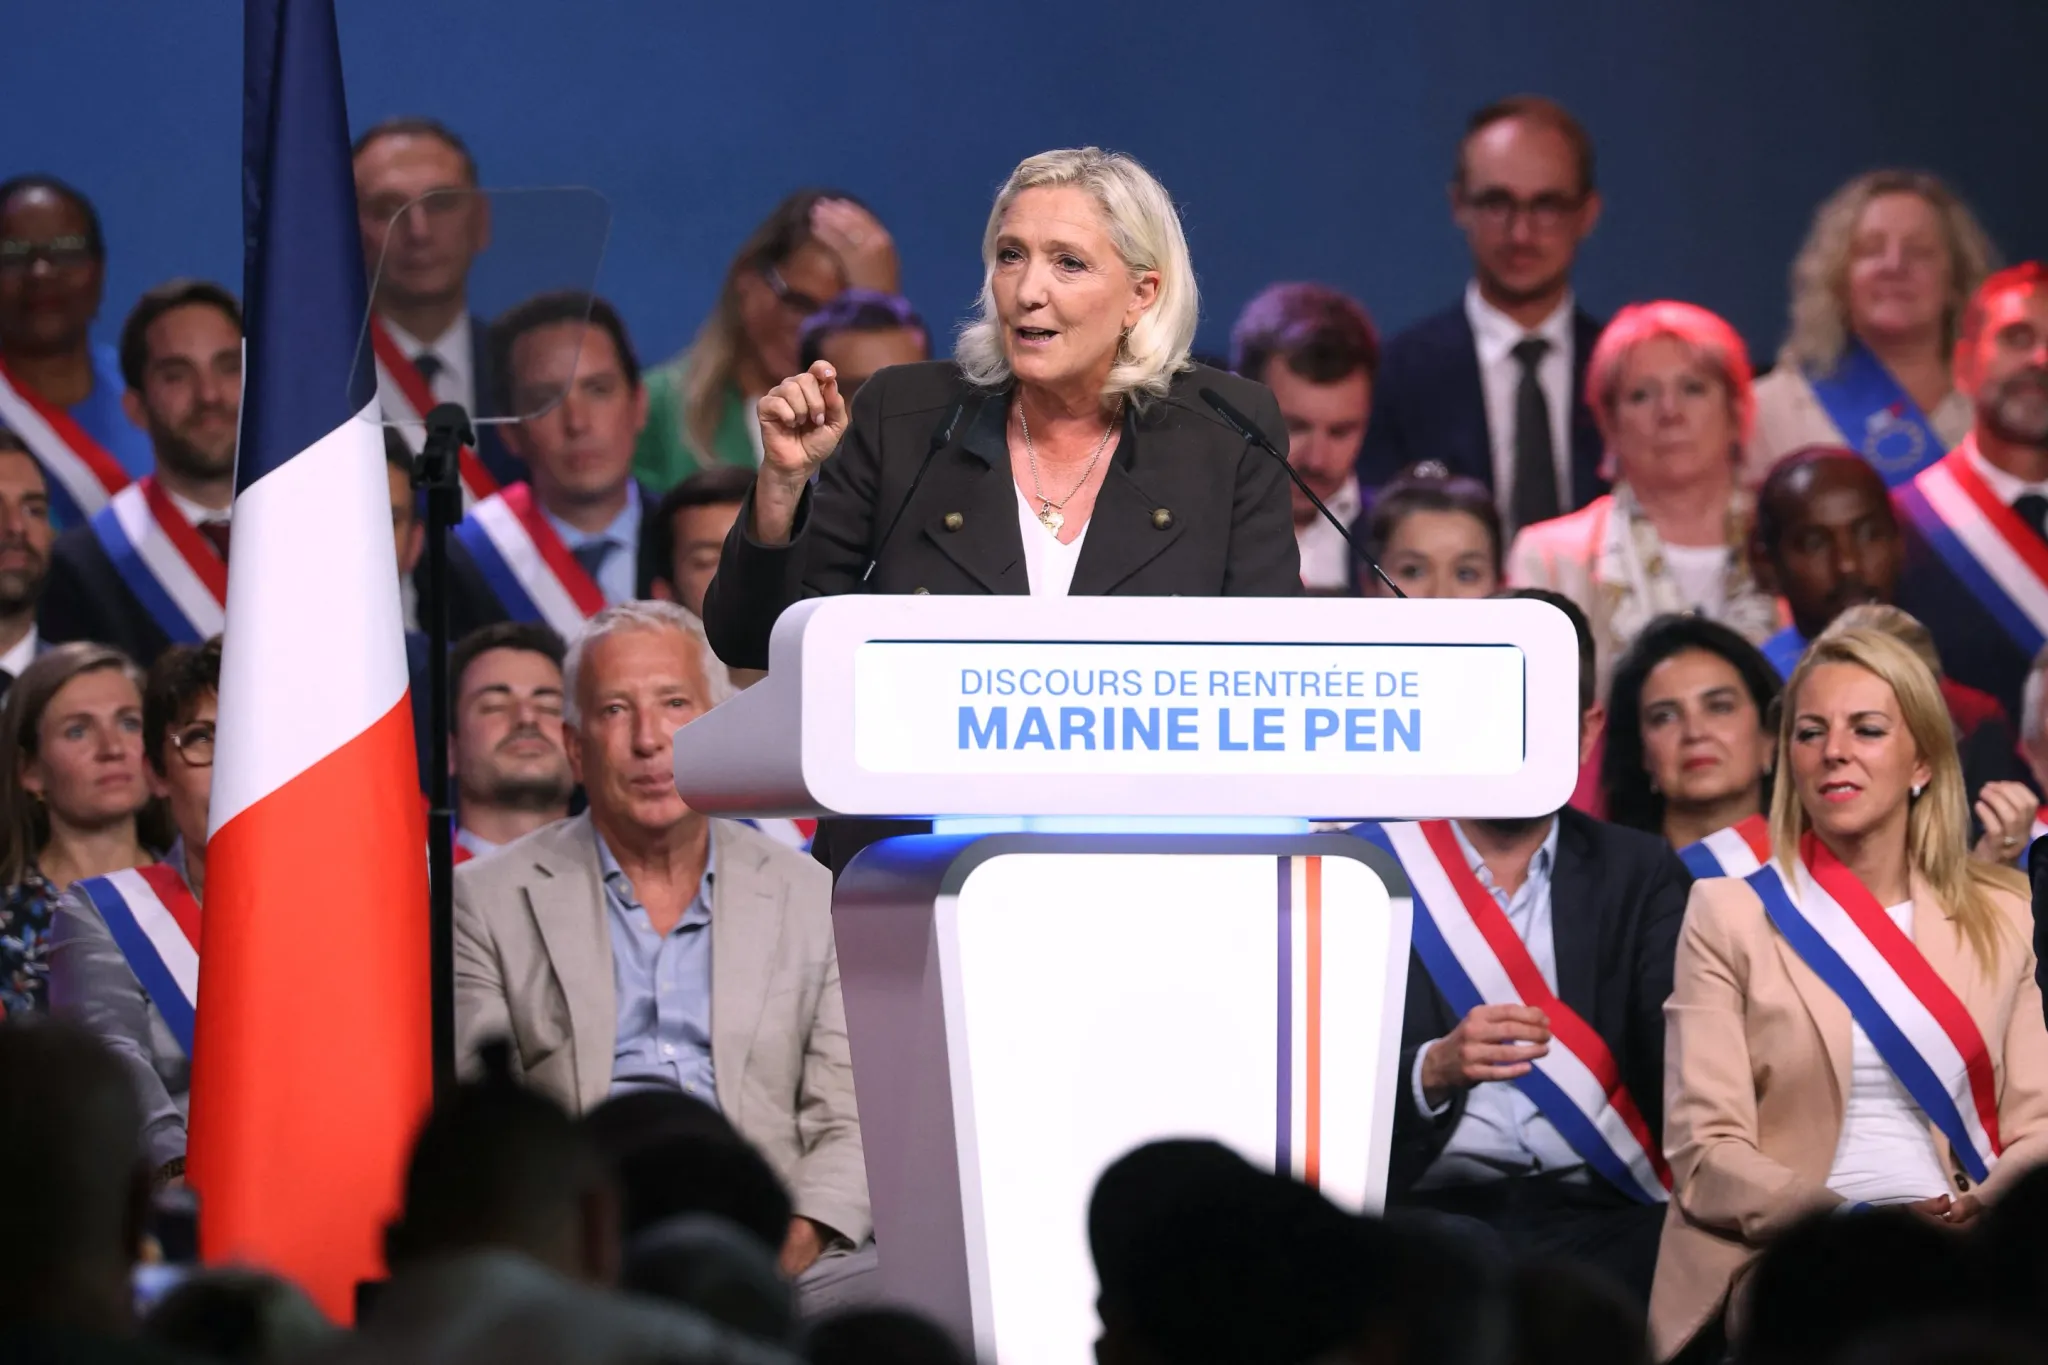
The bond market’s verdict reflects a collapse in confidence regarding fiscal consolidation ahead of next year’s presidential election. Polling suggests a likely runoff between far-right leader Marine Le Pen and far-left candidate Jean-Luc Mélenchon, neither of whom prioritizes deficit reduction. Le Pen, whose National Rally party currently leads in surveys, has proposed lowering the retirement age to 60 and implementing tax cuts despite pensions already consuming roughly 14% of GDP. Conversely, Mélenchon has campaigned on having the central bank cancel its holdings of French debt, a proposal that directly challenges ECB statutes and eurozone monetary architecture.
Macquarie Group strategist Thierry Wizman assessed the probability of a National Rally-led presidency adversely impacting 2028 budget perceptions at nearly 50%. This political uncertainty creates a feedback loop where higher borrowing costs make debt stabilization mathematically harder, further eroding investor confidence before any new administration takes office.
France’s vulnerability stems from a lack of economic buffers available to other high-debt nations. While Japan maintains a debt-to-GDP ratio exceeding 200%, it benefits from deep domestic savings and captive institutional buyers. The United States carries similar leverage but sustains stronger nominal growth and reserve currency status. France projects only 0.5% GDP growth this year while planning to issue more than $380 billion in medium- and long-term debt next year. With the deficit estimated at 5.4% of GDP and the debt ratio expected to reach 122% in 2027, there is minimal margin for error.
Credit rating agencies have begun formalizing this downgrade cycle. Scope Ratings cut France to A+ last month, matching Fitch and S&P Global Ratings, citing persistent political fragmentation that complicates necessary fiscal adjustments. Vanguard’s head of international rates, Ales Koutny, characterized France as a “long-term degrading credit,” warning that demand for sovereign paper can evaporate quickly when geopolitical or domestic political risks dominate market narratives.
The immediate pressure point remains the 2027 budget formulation process. Any failure to present a credible deficit trajectory during the upcoming campaign season risks accelerating the widening of risk premiums well before voters cast ballots, potentially forcing emergency fiscal measures or EU intervention discussions.