

U.S. crypto regulators move after Senate blocks Clarity Act in 49–50 vote
SEC relief, CFTC actions and stablecoin proposals put agency rules at the center of digital asset oversight

WASHINGTON — The SEC, CFTC, Federal Reserve and Office of the Comptroller of the Currency launched separate digital asset initiatives within 48 hours of the Senate’s failure to advance the Clarity Act. Their exemptive orders, administrative rulings and proposed regulations shift the immediate fight over U.S. cryptocurrency market standards from Congress to federal agencies and the executive branch.
The Senate halted the market-structure bill on a 49–50 procedural vote, short of the 60 votes needed to proceed. Three Republicans joined unified Democratic opposition after negotiations deteriorated over ethics provisions concerning business conflicts of interest, specifically digital asset commercial ventures affiliated with President Donald Trump. Developed over more than a year, the bill would have formally divided digital asset oversight between the Securities and Exchange Commission and the Commodity Futures Trading Commission.
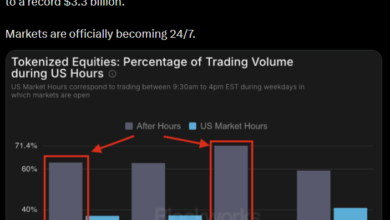
SEC Chairman Paul Atkins unveiled a digital asset “innovation exemption” allowing qualifying trading platforms to list and settle tokenized shares of U.S. public corporations on public and permissioned blockchains without standard registration as national securities exchanges. Atkins cited the stalled legislation as the reason to use existing statutory powers to create practical compliance channels for institutional blockchain integration.

The CFTC, meanwhile, issued staff no-action relief for developers of non-custodial software, decentralized interfaces and passive digital asset wallets. Under the letter, developers who write code connecting users to regulated derivatives markets without handling client funds need not register as introducing brokers or futures commission merchants under the Commodity Exchange Act.
Senator Cynthia Lummis, the Wyoming Republican who was the Clarity Act’s principal sponsor and chief negotiator, acknowledged after the vote that the measure had reached an impasse and would not return during the current legislative session. The SEC’s use of discretionary exemptive authority marks a departure from its approach under former Chairman Gary Gensler: during the Biden administration, the commission relied primarily on enforcement actions to bring crypto trading platforms, staking providers and token issuers into compliance with the Securities Act of 1933 and the Securities Exchange Act of 1934. It asserted that the vast majority of digital tokens were investment contracts under the Supreme Court’s 1946 Howey test.

The Federal Reserve Board proposed strict prudential standards for payment stablecoin issuers under its supervision, advancing a separate mandate under the GENIUS Act, the federal stablecoin law Trump signed in 2025. Bank and non-bank issuers would have to back tokens in circulation dollar-for-dollar with direct U.S. Treasury obligations, central bank reserve balances or reverse repurchase agreements, while maintaining mandatory capital reserves against operational and cyber risks.
The CFTC also sent a comprehensive proposed market-structure rule to the White House Office of Information and Regulatory Affairs for interagency review. Its text remains restricted pending publication in the Federal Register, but the package outlines oversight parameters for spot commodity token markets, clearing mechanisms and registered market participants.
At the OCC, rulemaking continues on domestic chartering guidelines for stablecoin issuers ahead of a mandatory January implementation deadline. The agency plans to issue final regulatory standards by November governing national bank digital custody and payment token issuance. Digital asset advocacy groups and financial institutions have shifted their Washington strategies toward the agencies; Kristin Smith, president of the Solana Policy Institute, said market participants had redirected resources to regulators, viewing agency rulemaking as the most viable operational route to commercial standards while Congress remains divided.
Administrative measures have limits that statutes do not. Regulations, guidance and exemptive orders require formal notice-and-comment cycles under the Administrative Procedure Act, often taking 12 to 24 months to finalize. Agency rules also face legal challenges following the Supreme Court’s 2024 ruling in Loper Bright Enterprises v. Raimondo, which overturned Chevron deference and ended judicial deference to agency interpretations of ambiguous statutes. Unlike permanent statutory legislation, which requires another act of Congress to repeal, administrative actions and exemptive orders can be challenged by outside interest groups or withdrawn unilaterally by an incoming presidential administration.

One Comment