South Korea Weighs Pushing Crypto Tax to 2029
Lawmaker ties proposed capital gains levy to OECD data-sharing timeline, pushing implementation back two more years
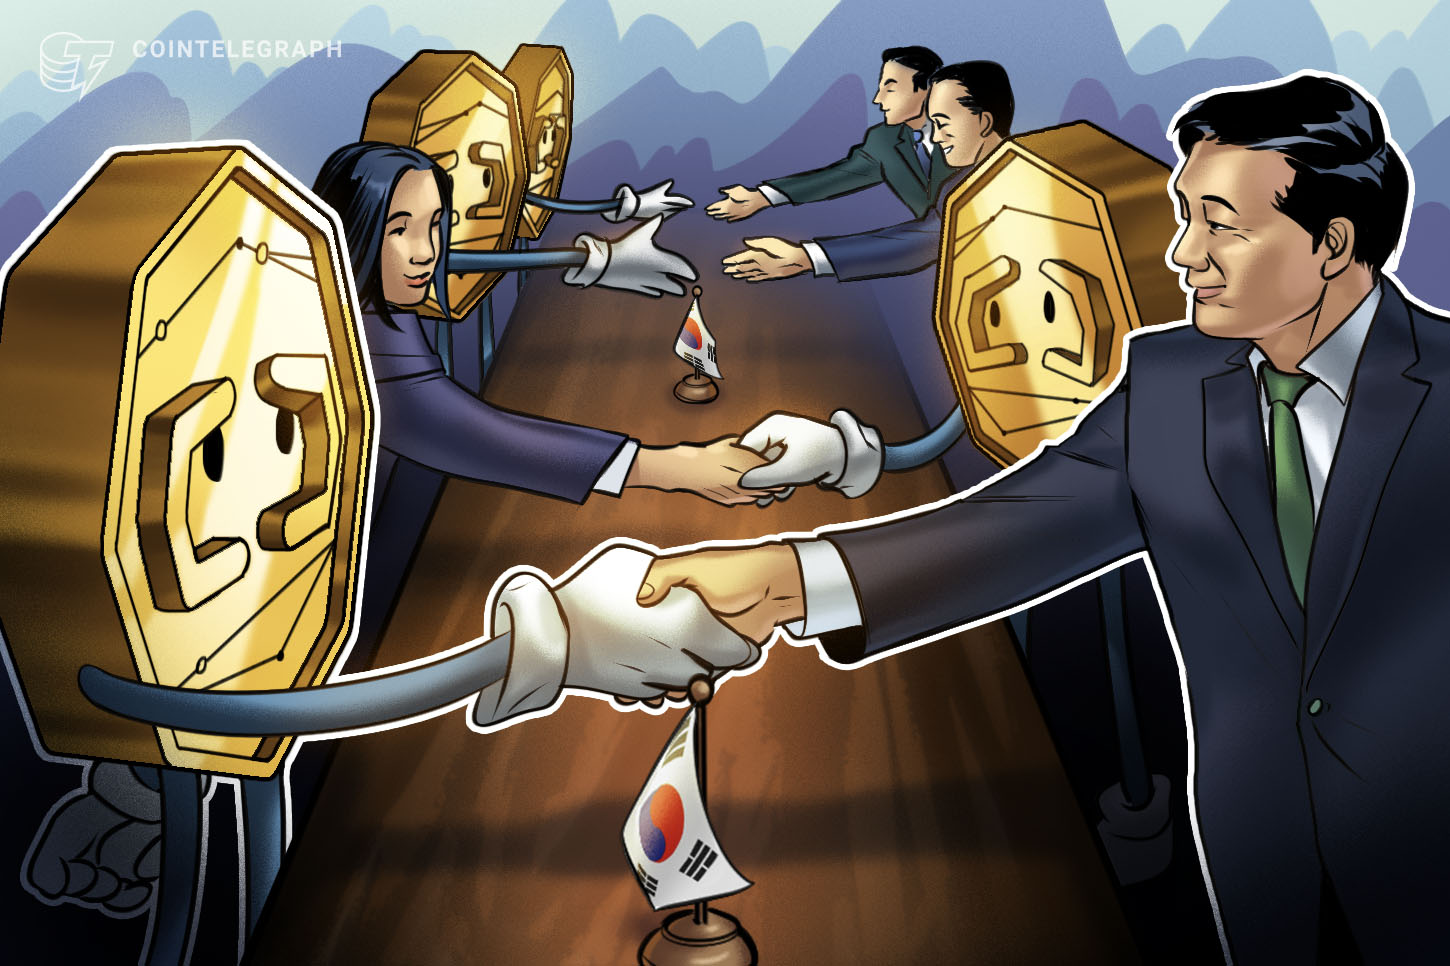
South Korean finance officials will meet executives from the country’s five largest cryptocurrency exchanges Tuesday as lawmakers push to delay a long-stalled crypto tax until at least 2029. The consultation marks the government’s first direct engagement with trading platforms since Democratic Party of Korea lawmaker Park Min-gyu introduced legislation Friday tying any capital gains levy to international data-sharing timelines.
First Vice Minister of Finance and Economy Kwon Dae-young and Financial Services Commission digital financial policy director general Yoo Young-jun will lead the government delegation, according to Yonhap. Representatives from Upbit, Bithumb, Coinone, DigitalX and Gopax are scheduled to attend alongside executives from the Digital Asset Exchange Alliance (DAXA), the industry trade group representing the platforms.
Park’s bill would postpone taxation until Jan. 1 of the second year after South Korea begins exchanging information under the OECD’s Crypto-Asset Reporting Framework (CARF). With the first CARF data exchange expected in 2027, that formula pushes the effective start date to 2029.
The proposal is the latest attempt to resolve a political standoff that has already forced three postponements. Seoul originally planned to tax cryptocurrency capital gains starting in 2022. Lawmakers pushed the deadline to 2023, then 2025, and most recently to 2027 following disputes over a 2.5 million won ($1,800) tax-free threshold that critics argued was too low compared with the 50 million won exemption applied to domestic stock investments.
Exchange operators argue they still lack the technical specifications required to comply. “Standards for different transaction types have not yet been finalized, and time is running short for practical preparations on the infrastructure side,” an unnamed exchange official told Yonhap on Sunday. “There is a shared view in favor of postponing the start of taxation.”
South Korea processes roughly $50 billion in daily cryptocurrency trading volume across its major platforms, according to industry estimates, making compliance infrastructure a significant operational challenge. Unlike traditional brokerage systems that have tracked cost basis for equities for decades, crypto exchanges must build new tracking mechanisms for decentralized wallet transfers, peer-to-peer transactions and cross-chain swaps that do not fit conventional reporting categories.
The OECD adopted CARF in 2022 to close gaps in global tax enforcement created by digital assets moving outside traditional banking channels. More than 50 jurisdictions, including the United States, Japan and members of the European Union, have committed to implementing the framework. South Korea’s decision to link domestic taxation to CARF participation reflects a broader strategy among developed economies to avoid unilateral rules that could drive trading activity offshore.
Tuesday’s meeting follows a separate government initiative announced earlier this month to overhaul cybersecurity standards across the financial sector after a series of attacks targeted banks and crypto firms.