Goldman Surges on Equities as JPMorgan Misses in Rare Bank Earnings Split
A 72% equities surge at Goldman offset fixed-income weakness, while rising rates and geopolitical tensions stall the record-setting 2026 IPO pipeline.
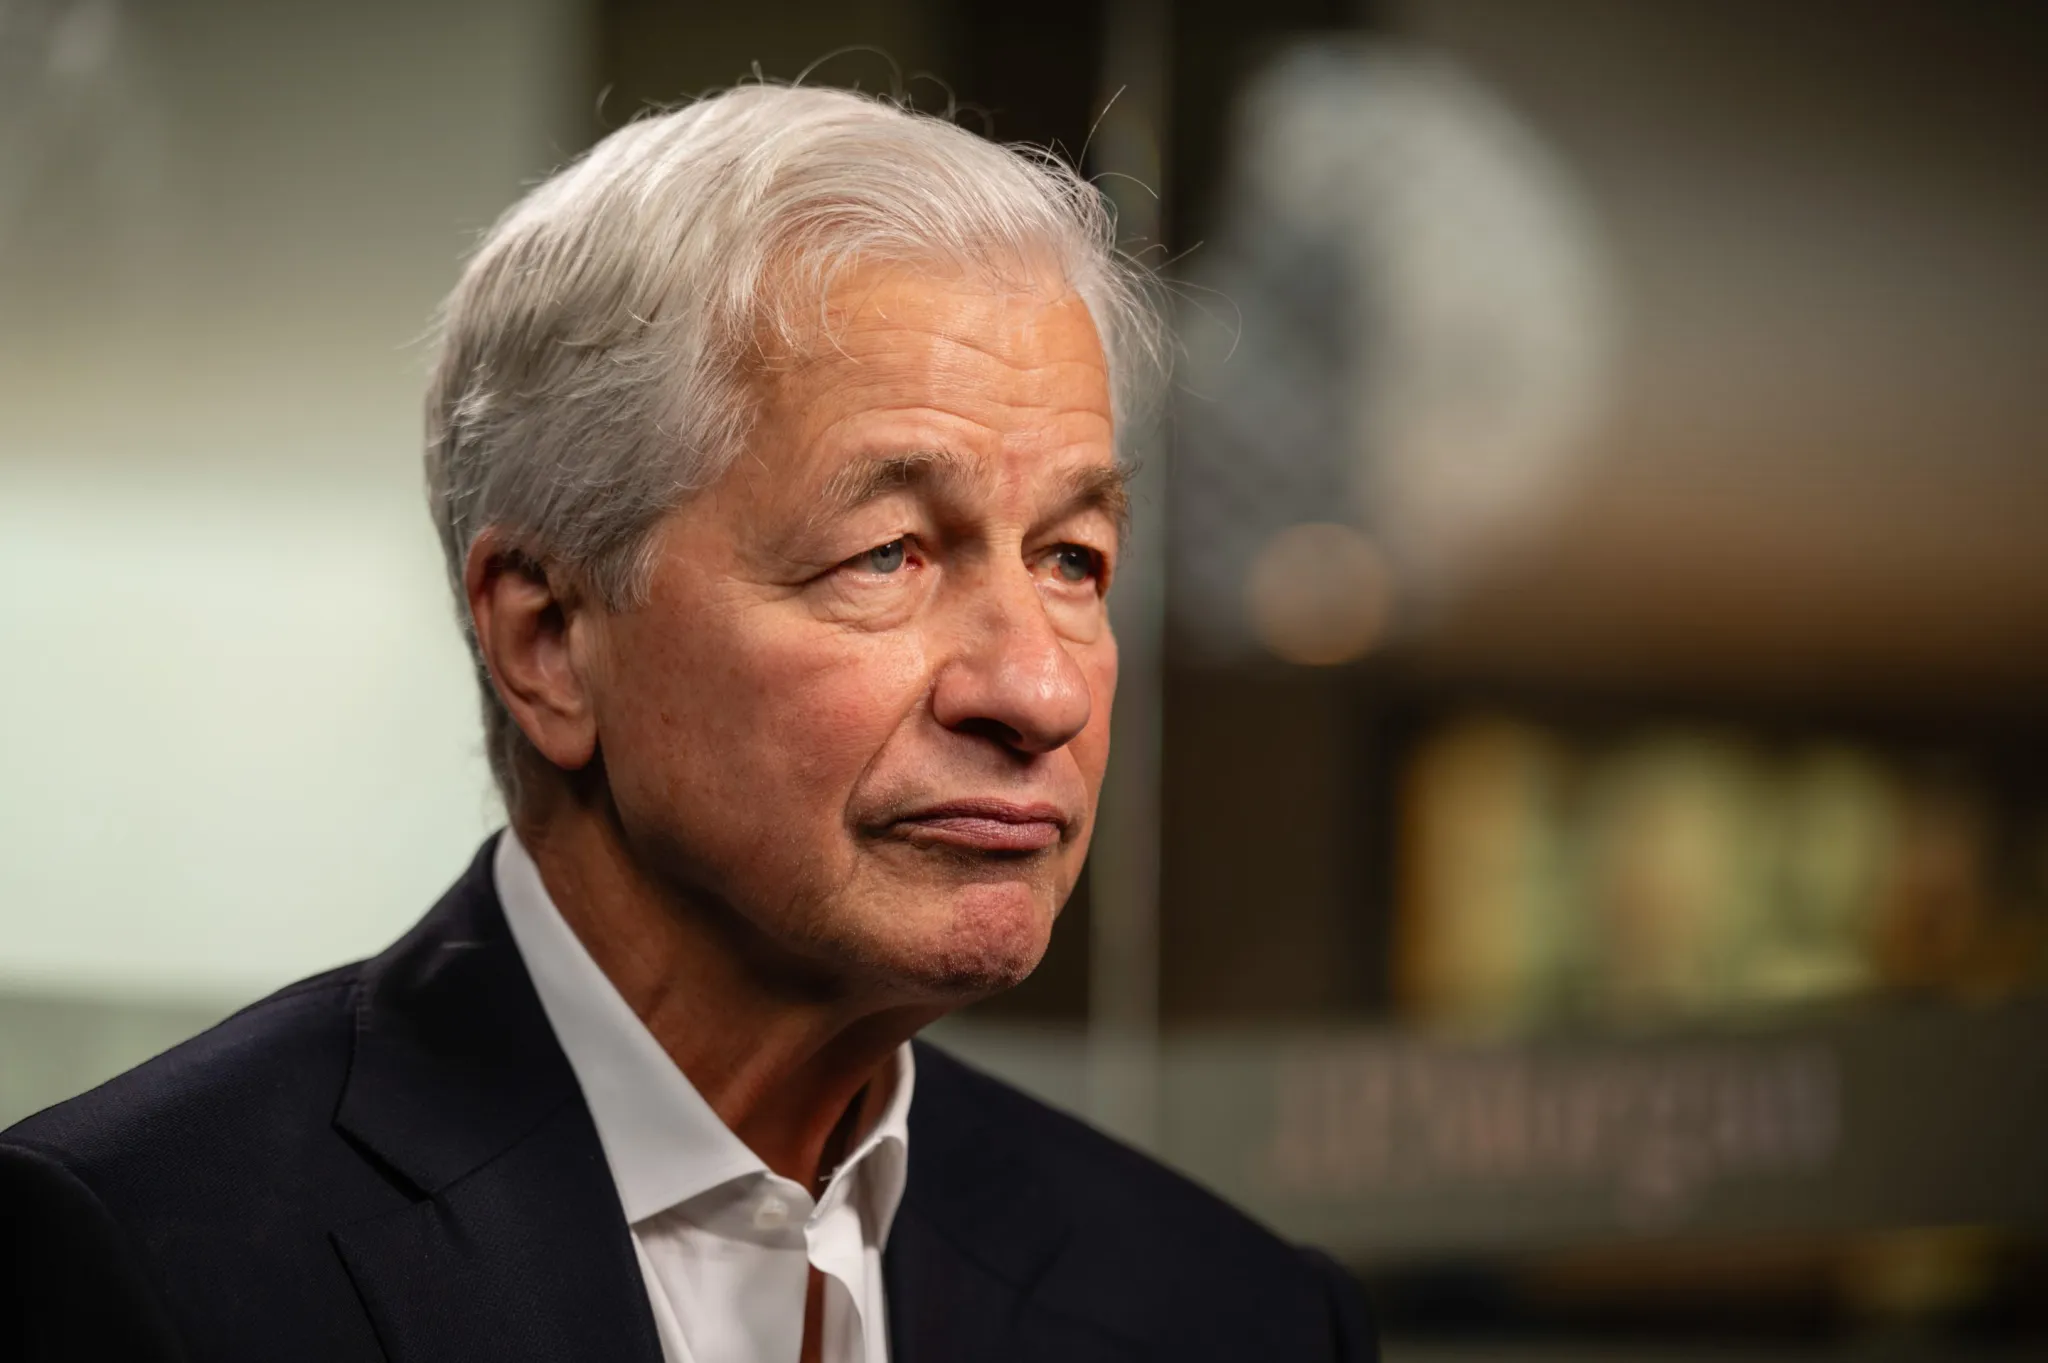
Goldman Sachs delivered a sharp earnings beat driven by a 72% surge in equities revenue, while JPMorgan Chase posted its first quarterly miss in nearly three years, exposing a widening performance gap between Wall Street’s two dominant investment banks during the third quarter of 2026.
The divergence underscores how structurally different the firms have become despite frequent comparisons. JPMorgan, the largest U.S. bank by assets with a market capitalization near $881 billion, operates primarily as a consumer and commercial lending giant where rising operating expenses carry outsized weight. Goldman remains heavily tethered to capital markets. When fixed-income, currencies, and commodities trading softened across both institutions, only Goldman possessed an equities franchise large enough to absorb the shock entirely.
Morgan Stanley and Citigroup also cleared expectations for both revenue and profit. Bank of America reported a year-over-year decline in third-quarter net income. Wells Fargo generated $21.87 billion in revenue, missing the $22.31 billion consensus estimate and marking the third time in four quarters that the San Francisco-based lender failed to meet top-line projections.
JPMorgan’s stumble carries broader implications because the bank has functioned as a reliable bellwether for the U.S. economy since late 2023, when it consistently began exceeding analyst forecasts following its acquisition of First Republic Bank assets. A simultaneous miss on both revenue and earnings per share breaks a streak that had anchored investor confidence in the financial sector throughout the Federal Reserve’s rate-adjustment cycle.
Rising interest rates are now reshaping activity beyond trading desks. The initial public offering market experienced a sudden pullback in late September after an active summer. Oura postponed its planned listing, following similar delays by Bamboo Insurance and Holtec Nuclear.
Companies are not abandoning their listing plans. They are filing confidentially with the Securities and Exchange Commission, selecting underwriters, and preserving flexibility until pricing dynamics stabilize. In a rising-rate environment, investors apply steeper discount rates to future cash flows, which directly compresses the valuations founders and private equity sponsors are willing to accept. Goldman CEO David Solomon noted that issuers expecting specific valuations balked when market feedback suggested prices 10% to 15% lower.
Matt Kennedy, a senior strategist at Renaissance Capital, attributed the hesitation to a combination of tightening monetary conditions and growing investor skepticism regarding artificial intelligence valuations. Despite the recent friction, 2026 remains on pace to surpass last year’s total IPO deal count and has already established a record for total proceeds raised, a milestone achieved even excluding SpaceX’s June offering.
Geopolitical developments remain a primary variable for the fourth-quarter pipeline. Kennedy identified a potential resolution to the Iran war as a critical catalyst, noting that lower oil prices could ease inflationary pressure, alter the interest rate trajectory, and reopen risk appetite for new issuances. An anticipated November IPO from Anthropic is also being closely monitored as a barometer for whether premium technology listings can successfully clear the current market.
Beneath the public-market volatility, venture capital continued to concentrate heavily on artificial intelligence infrastructure, particularly within healthcare and compliance automation. Suki, a Redwood City developer of clinical documentation software, secured $90 million in Series E funding led by Healthier Capital, Crosslink Capital, and Hercules Capital. London-based Scarlet raised $50 million in a Series B round led by Headline to certify AI-powered medical devices, while New York-based Brellium closed $23 million led by Left Lane Capital and First Round Capital to audit patient records for billing compliance.
Private equity firms maintained steady acquisition volumes across fragmented service industries. Fengate Private Equity took a majority stake in Clinical Research of West Florida, a Tampa-based network of trial sites. Godspeed Capital acquired GreenVest, a Maryland environmental restoration provider. Norwest Equity Partners purchased pop-up canopy manufacturer E-Z UP from Beach Point Capital.